How Did the 1873 Financial Crisis Reshape Money?
TL;DR
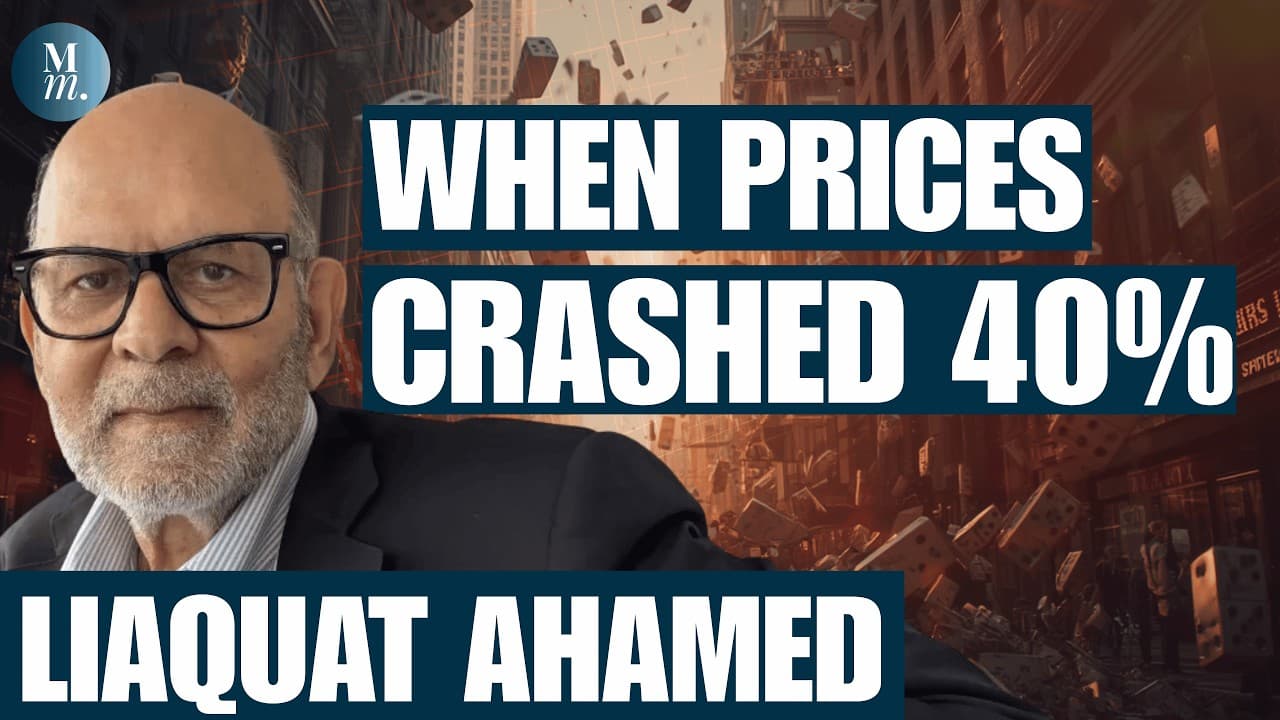
Germany’s abrupt shift from silver to gold during the 1873 financial panic intensified a global scramble for gold, contracted liquidity, and contributed to prolonged deflation. The crisis followed simultaneous bubbles in European stocks, London securities, and American railroads, showing how infrastructure investment, debt expansion, monetary disruption, and fierce competition can turn productive innovation into poor financial returns.
Transcript
In the middle of a financial crisis, everyone tries to hoard precious metals and get out of paper money. You draw any chart of default rates on US corporate investment and it is the highest in our history. It wouldn't surprise me if we got a series of mini booms and busts on in the AI boom. Every private sector infrastructure boom faces these issue... Read More
Key Insights
- The pre-1873 monetary system was based on both gold and silver, with France and the United States absorbing changes in precious-metal supplies. This balancing mechanism kept the monetary base relatively stable and supported stable prices through much of the nineteenth century.
- Germany’s rapid move from silver to gold in 1873 was intended to hurt France after its military defeat. Instead, Germany also harmed itself because other European countries panicked, sold silver, sought gold, and intensified a contraction in liquidity during an existing financial crisis.
- A scramble for precious metals contracts money under a metal-based monetary standard because banks and the public exchange paper claims for scarce reserves. During a panic, central banks need to accommodate that demand, but the shift toward gold instead restricted the available monetary base.
- The investment boom beginning around 1850 was initially rational and productive. Expanding bond markets channeled savings from Britain and France into railroads, ports, undersea cables, and communications projects worldwide, creating useful infrastructure without obvious early excesses.
- The Franco-Prussian War unexpectedly accelerated speculation rather than ending the boom. France’s indemnity fueled markets in Germany and Austria, capital seeking safety boosted American railroad construction, and London became a speculative venue for small companies and unfamiliar sovereign borrowers.
- Three simultaneous bubbles emerged between 1870 and 1873: stocks and real estate in Berlin and Austria, railroad investment in the United States, and speculative securities issuance in London. By late 1872, observers were already warning about excessive fundraising and impending trouble.
- Railroad expansion became financially fragile because much of it relied on bonds rather than equity. Debt-funded infrastructure can produce severe losses when many competitors build at once, demand disappoints, or revenues cannot cover the fixed obligations created during optimistic markets.
- The modern AI and data-center boom may experience repeated smaller booms and busts because competing firms are investing heavily to become leaders. Ahamed expects the underlying technologies to improve productivity, yet warns that intense competition can still produce poor returns across the industry.
- More videos from this channel:
- More from this channel: The Monetary Matters Network
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: Why did Germany’s move to gold worsen the 1873 crisis?
Germany began selling silver and moving toward gold after defeating France, partly to damage France, which held substantial silver reserves. Other European countries reacted by dumping silver and seeking gold as well. Because this happened during a financial panic, when banks and investors were already hoarding precious metals and leaving paper money, the resulting scramble for gold contracted liquidity and the money supply instead of stabilizing them.
Q: How did the gold and silver monetary system work before 1873?
For roughly fifty years, the monetary system relied on a combination of gold and silver. Britain and part of the financial world used gold, while countries including Germany, China, India, Turkey, and Mexico used silver. France and the United States accepted both metals, acting as balancing forces that absorbed changing supplies. This arrangement kept the monetary base relatively stable despite alternating gold and silver discoveries.
Q: What caused the prolonged deflation after the 1873 panic?
The shift from silver toward gold created a broad monetary contraction. European countries sold silver and competed for gold just as new gold discoveries were slowing dramatically. Ahamed says movements in silver prices relative to gold closely matched movements in commodity prices, identifying the monetary disruption as the most important cause of the deflation that continued from 1873 into the 1890s.
Q: What created the global investment boom before 1873?
The boom began around 1850 and was supported by a major expansion of bond markets, with the Rothschilds serving as important architects of that expansion. Growing savings in Britain and France were directed into infrastructure projects around the world. Railroads, ports, undersea cables, and communications networks attracted funding because they represented genuine opportunities, making the early phase of the boom rational rather than purely speculative.
Q: How did the Franco-Prussian War fuel financial bubbles?
The war disrupted normal capital flows and transferred a large indemnity from France to Germany. The payment was about one billion dollars at the time, described as roughly 1.2 to 1.3 trillion dollars when adjusted for the relative size of modern economies. The transfer fueled speculation in Germany, while displaced capital also accelerated American railroad construction and encouraged risky securities issuance on the London Stock Exchange.
Q: Which markets formed the three major bubbles before 1873?
The first bubble appeared in Berlin and Vienna, where Germany’s receipt of French money helped drive stock and real-estate speculation. The second emerged in the United States, where capital escaping European conflict accelerated an already established railroad boom. The third developed in London, where small companies and sovereign borrowers could issue stocks and bonds to buyers who often knew little about the businesses or countries involved.
Q: Why can productive infrastructure booms produce poor returns?
Infrastructure booms can begin with genuine technological opportunities while still becoming financially destructive. When many competitors simultaneously seek leadership, each has an incentive to build aggressively, but their combined investments can create excess capacity and weak returns. The American railroad boom was especially vulnerable because much of its expansion was financed with bonds, leaving projects with fixed debt obligations when the boom collapsed.
Q: How is the nineteenth-century railway boom similar to the AI boom?
Both involve large private-sector investments in infrastructure tied to promising technologies. Railroads, communications networks, AI systems, and data centers can raise productivity, yet competition encourages companies to spend heavily in pursuit of leadership. Ahamed argues that these collective efforts may generate poor returns even if the technology succeeds, and he would not be surprised to see a series of smaller booms and busts during the AI expansion.
Summary & Key Takeaways
-
For decades, gold and silver jointly supported a resilient monetary system, with France and the United States acting as balancing forces. Germany disrupted that arrangement in 1873 by selling silver and moving rapidly toward gold, prompting other European countries to follow and creating a damaging contraction in money and liquidity.
-
The crisis followed a long, initially rational investment boom supported by expanding British and French savings and the Rothschilds’ development of bond markets. Capital funded railroads, ports, undersea cables, and communications, but disruptions after the Franco-Prussian War helped produce simultaneous speculative bubbles in Germany, Austria, Britain, and the United States.
-
The railway boom offers a comparison with the modern expansion of AI and data-center infrastructure. Competition can encourage every participant to invest aggressively, even when the collective result is excess capacity and poor returns. Ahamed expects technological productivity gains but warns that investors could experience repeated smaller booms and busts.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from The Monetary Matters Network 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator