How did Minna de Oya-san stay afloat with 288B insolvency
TL;DR
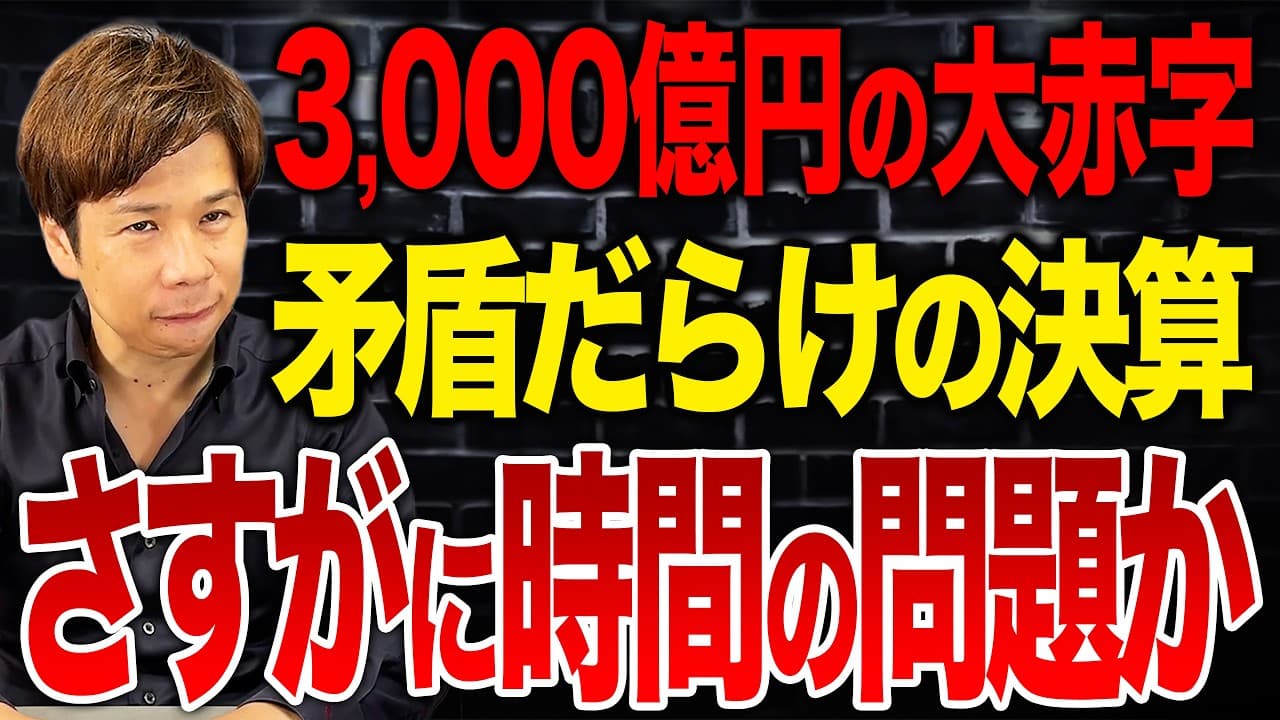
The video explains a 288.1 billion yen insolvency for Minna de Oya-san, with assets of 39.1 billion and liabilities of 327.2 billion. It highlights impairment losses of 278.5 billion and questionable accounts receivable, revealing the gap between P&L and cash flow due to non cash write downs and accrued distributions.
Transcript
What is the common term for when net assets are negative? Insolvency. Right, insolvency. It’s 288.1 billion yen in insolvency. They say they’ll sell off their properties. And resolve the insolvency. Who would actually think, "Alright, I can count on that"? Hello. I’m Sugawara, the tax accountant. Mr. Sugawara, about the widely discussed ... Read More
Key Insights
- Insolvency is defined as negative net assets when liabilities exceed assets, which Minna de Oya-san experienced with a 288.1 billion yen shortfall.
- Impairment loss of 278.5 billion yen alone can create huge deficits on the income statement even if cash did not physically leave the company.
- Assets were overstated on a paper basis, with 20.2 billion in accounts receivable potentially unrecovered and 22.5 billion in sales not fully realized.
- Cash at year end was 300 million yen, but prior cash levels were higher, showing a steep cash decline not captured by the deficit alone.
- Distributions of 13.1 billion yen were recorded as expenses but not yet paid, illustrating accrual accounting effects on cash flow.
- The balance sheet showed 327.2 billion yen in liabilities against only 39.1 billion in assets, a classic insolvency signal.
- Doubtful accounts and questionable revenue recognition from the Narita Project generate concerns about real earnings versus reported numbers.
- The video emphasizes the distinction between income statement deficits and cash flow, noting impairment write-downs do not always equate to cash outflows.
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: What does insolvency mean in the Minna de Oya-san case
In this case insolvency means negative net assets, where liabilities exceed assets by 288.1 billion yen. The company has 327.2 billion yen in liabilities and only 39.1 billion yen in assets, leaving a large deficit that cannot be covered by available cash. This description aligns with the balance sheet imbalance disclosed in the presentation.
Q: What caused the 278.5 billion yen impairment
The impairment loss of 278.5 billion yen arises from write-downs in the value of land and buildings, reducing their carrying amount to reflect current appraised values. This write-down is an accounting expense that lowers net assets and increases losses, even if the actual cash outflow is not immediate.
Q: Why is there concern about accounts receivable
Accounts receivable of 20.2 billion yen is questioned because it may include revenue that was never realized or realized only via affiliate arrangements that did not result in real cash collection. The concern is that this creates inflated revenue and misleading asset values, contributing to perceived solvency problems.
Q: How is cash liquidity different from the deficit
Cash liquidity refers to actual cash on hand, which was reported at 300 million yen, much smaller than the total liabilities. The deficit on the income statement can be large due to non cash charges like impairment, while cash flow may differ because some expenses are accrued and not yet paid.
Q: What is the role of distributions in the expenses
Distributions of 13.1 billion yen are recorded as an expense on the income statement but were not actually paid at closing. This creates a liability and reduces net income without a corresponding cash outflow, illustrating how accrual accounting can misrepresent cash health.
Q: Why might sales consolidation be misleading
The Narita Project and affiliate arrangements may have recorded revenue that was not fully realized or collectible, potentially inflating reported sales. If 20.2 billion in receivables are doubtful or unrecoverable, the true revenue contribution is much smaller, worsening the asset and equity position.
Q: What does the ailing balance sheet imply about asset values
The balance sheet shows assets of 39.1 billion against liabilities of 327.2 billion, implying that asset values are overstated or impaired. The large impairment and the questionable asset recoverability signal a poor underlying financial position and raise doubts about ongoing viability.
Q: What does this case illustrate about P&L versus cash flow
It illustrates that an income statement deficit does not always equal cash outflow. Impairment losses and accrued but unpaid distributions can reduce net income while cash remains limited, highlighting the need to examine cash flow statements and real liquidity beyond earnings.
Summary & Key Takeaways
-
Minna de Oya-san faced a massive deficit driven by impairment charges that wiped out asset value, resulting in insolvency. The discussion decodes why the company appeared to survive on paper and what the balance sheet shows about true liquidity.
-
The video walks through the balance sheet to show why negative net assets occurred, including the role of unpaid distributions and doubtful accounts, and contrasts income statement deficits with actual cash flow.
-
The analysis concludes that the accounting treatment, especially impairment losses and accruals, masked real cash constraints and questioned the recoverability of reported sales and assets.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from 脱・税理士スガワラくん 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator