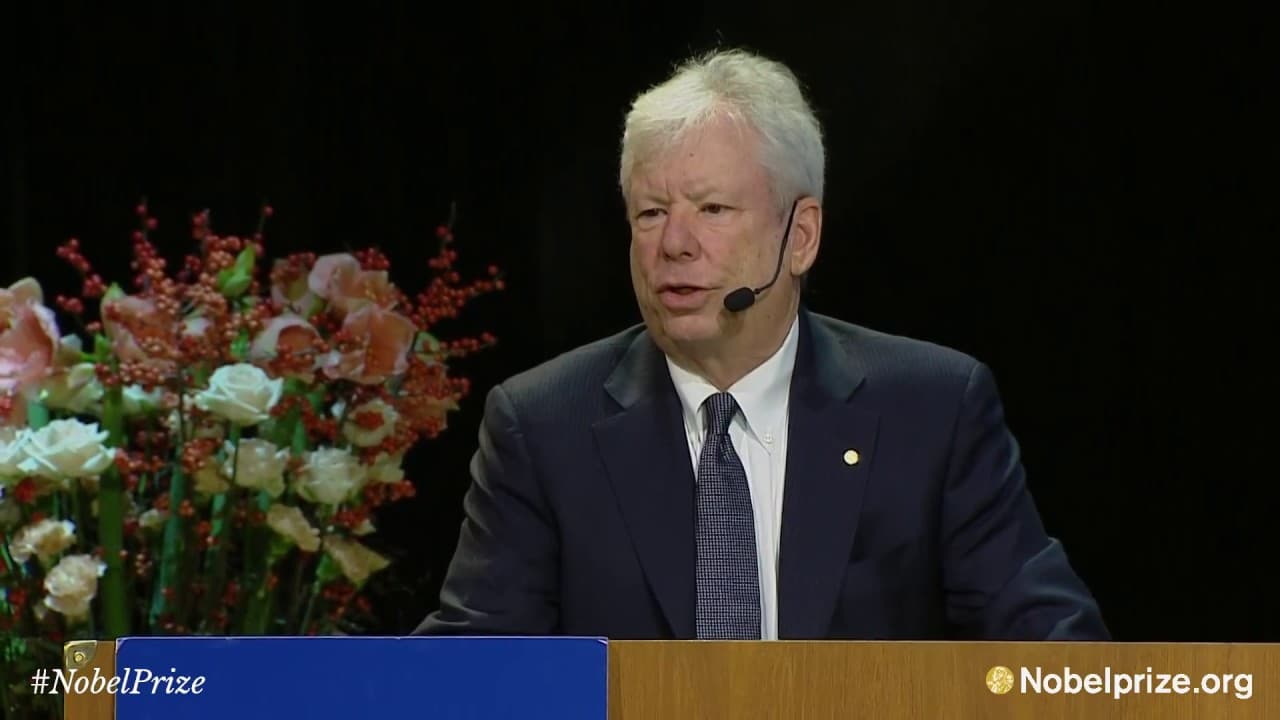
Prize Lecture: Richard Thaler, The Sveriges Riksbank Prize in Economic Sciences 2017
TL;DR
Behavioral economics improves economic predictions by recognizing that supposedly irrelevant factors often change decisions. Choice restrictions can support self-control, ownership can reduce trading through loss aversion and status quo bias, and sunk costs can influence behavior even when they cannot be recovered. Experiments turn these everyday puzzles into evidence about bounded rationality, limited willpower, and systematic bias.
Transcript
thanks Magnus thanks to all the members of the committee and thanks for that great introduction so I've I've been interested in gravitational waves for a long tono so I I began this inquiry really with a series of stories stories and thought experiments and I thought what I would do in the lecture today is give you a sense of the path of behavioral... Read More
Key Insights
- More choice is not always experienced as better because removing temptation can improve self-control. Dinner guests thanked Thaler for hiding a bowl of cashews even though losing access reduced their available choices, contradicting the economic axiom that more choices are always preferred to fewer choices.
- The endowment effect makes ownership relevant to valuation. A wine collector would not pay more than $30 for a bottle, would not sell an owned bottle worth $100, yet might drink it, showing that willingness to consume can depend on whether the person already owns the item.
- Sunk costs can influence present choices even though they cannot be recovered. Thaler's friend believed they would have driven through a snowstorm to attend a basketball game if they had purchased the tickets, although attending would not have restored the money already spent.
- Heuristics can produce systematic bias rather than merely random mistakes. Tversky and Kahneman's work helped Thaler see that boundedly rational people use simple rules of thumb, creating predictable errors that behavioral economics can study and incorporate into explanations of economic decisions.
- Availability bias distorts frequency judgments when vivid or accessible examples dominate reasoning. People asked about United States gun deaths tend to think homicide is more frequent, while the lecture states that deaths by suicide occur about twice as often as deaths by homicide.
- Supposedly irrelevant factors are details that standard economic theory predicts should not matter but that affect actual decisions. Food location, prior ownership, and money already spent are examples, and including such factors can expand the predictive power of economic theory.
- The token market supported the Coase theorem under low transaction costs. After tokens with assigned redemption values were distributed randomly, trading moved them toward participants with the highest values, so the initial random assignment did not determine the eventual allocation.
- The mug market produced about one third as much trading as predicted because owners resisted surrendering their mugs while nonowners showed limited interest in buying. Loss aversion, status quo bias, uncertainty about alternatives, and basic laziness all help explain this reduced exchange.
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: How did the cashew story challenge standard economics?
The cashew story challenged the axiom that more choices are always preferred to fewer choices. Dinner guests could initially choose whether to eat the nuts, but Thaler removed that option by hiding the bowl. They thanked him because removing the temptation protected their appetites. Their relief suggested that restricting choice can make people feel better off when self-control is limited.
Q: What does the wine collector story show about ownership?
The wine collector would not pay more than $30 for a bottle, yet he sometimes drank an old bottle that he had purchased for $4.95 and could later sell for $100. He would neither buy it at the higher price nor sell it, but would consume it. The puzzle suggests that ownership changes valuation through the endowment effect, loss aversion, and status quo bias.
Q: Why should sunk costs not determine a current decision?
A sunk cost is money that has already been spent and cannot be recovered through the current choice. In Thaler's basketball example, attending the game during a snowstorm would not restore the price of purchased tickets. Nevertheless, his friend believed paying for the tickets would create pressure to attend, illustrating how mental accounting can make an irrelevant past expense influence present behavior.
Q: How do heuristics create systematic biases?
Boundedly rational people use simple rules of thumb to make judgments and decisions. Tversky and Kahneman's research showed Thaler that these shortcuts do not produce only occasional or random errors. They can generate systematic bias, meaning that mistakes follow recognizable patterns. This insight made it possible to study departures from economic theory as predictable behavior rather than unexplained noise.
Q: What is availability bias in the gun-death example?
Availability bias occurs when people judge frequency using examples that come readily to mind. In the lecture's example, people tend to believe that United States gun deaths by homicide are much more frequent than gun deaths by suicide. The stated reality is that suicides occur about twice as often, showing how accessible impressions can systematically distort estimates.
Q: What are supposedly irrelevant factors in behavioral economics?
Supposedly irrelevant factors are details that economic theory says can be omitted because they should not affect a decision. Thaler argues that many such details matter in practice. Moving food farther away can reduce consumption, owning a wine bottle can alter willingness to trade it, and paying for tickets can change whether someone feels compelled to attend an event.
Q: What did the token and mug experiments demonstrate?
The assigned-value token market produced the expected trading pattern: participants with the highest redemption values eventually held the tokens, consistent with the Coase theorem under low transaction costs. The mug market behaved differently, producing about one third as much trading as predicted. Owners resisted selling, while participants without mugs were not very interested in buying, revealing ownership-dependent preferences.
Q: Why do people often remain with the status quo?
Status quo bias is the tendency to stick with what one already has or is already doing. The lecture links it to familiarity, uncertainty about alternatives, and basic laziness. Mug owners know and like what they possess, while alternatives are less certain. Similarly, television viewers may keep watching the same station even when switching requires only one thumb click.
Summary
In this video, the speaker discusses the path of behavioral economics and its application in various scenarios. He shares three stories that led to his research in behavioral economics, including the concept of self-control, loss aversion, and the sunk cost fallacy. He also explains how the use of heuristics can lead to systematic bias and the importance of supposedly irrelevant factors in economic theory. The speaker then introduces the concept of choice architecture, where the environment influences decision-making, and nudges as a way to influence choices without forcing anyone to do anything. He provides examples of nudges, such as changing defaults and using choice architecture to help individuals save more for retirement. The speaker also discusses the premium pension system in Sweden and its impact on investor behavior and the lasting effects of nudges.
Questions & Answers
Q: How did the speaker's interest in gravitational waves lead him to study behavioral economics?
The speaker began his inquiry into gravitational waves with stories and thought experiments. These stories and thought experiments eventually led him to the field of behavioral economics, where he explored the impact of supposedly irrelevant factors and the role of choice architecture in decision-making.
Q: What was the main lesson the speaker learned from the story of the economists analyzing the bowl of cashew nuts?
The main lesson from the story of the economists analyzing the bowl of cashew nuts is that having a choice removed can make individuals better off. Despite the economists' initial assumption that more choices are always preferred to fewer, they realized that they were happier without the choice to eat the nuts. This led to the exploration of self-control and its influence on decision-making.
Q: How did the story of the economics department chairman and the bottle of wine lead to further research on the endowment effect and loss aversion?
The story of the economics department chairman and the bottle of wine raised a puzzle for economists. While the chairman was willing to drink one of his old bottles of wine, he was unwilling to buy or sell it at certain prices. This led to the exploration of the endowment effect, loss aversion, and status quo bias, which resulted in a research program on how people value what they own differently from potential gains or losses.
Q: What is the sunk cost fallacy, and how did the story of the basketball game tickets illustrate it?
The sunk cost fallacy refers to the tendency to continue investing time, money, or effort into something simply because we have already invested in it, even if it does not offer value or benefits. In the story of the basketball game tickets, the speaker and his friend decided not to go to the game due to a snowstorm. However, their friend suggested that if they had already bought the tickets, they would feel compelled to attend the game, even if it did not change the fact that they had already spent money on the tickets. This led to further research on mental accounting and the impact of sunk costs on decision-making.
Q: What is choice architecture, and how does it influence decision-making?
Choice architecture refers to the environment in which choices are made, and it can significantly influence decision-making. For example, the structure of a menu or the layout of a store can impact what individuals choose or buy. By understanding how choice architecture influences decisions, behavioral economists can design interventions and nudges to guide individuals to make better choices without forcing them to do anything specific.
Q: What are nudges, and how do they help individuals make better choices?
Nudges are features of the environment that influence human behavior in a particular direction without forcing anyone to do anything. They leverage humans' tendency to be passive or make decisions based on defaults. For example, setting a default option for enrollment in a pension plan can significantly increase participation rates. Nudges can help individuals overcome self-control problems, loss aversion, and inertia to make better choices.
Q: How can nudges be used to encourage individuals to save more for retirement?
One powerful nudge to encourage individuals to save more for retirement is to change the default option in retirement plans. By automatically enrolling individuals in a retirement plan at a higher contribution rate, more people end up saving for retirement. Another nudge is to align saving decisions with future expected raises, so individuals do not perceive their income to be decreasing when saving more. These nudges can help individuals overcome self-control problems and inertia in saving for retirement.
Q: What is the save more tomorrow plan, and how does it leverage behavioral factors to help individuals save more for retirement?
The save more tomorrow plan is a retirement savings plan that invites individuals to save more in the future, leveraging their tendency for self-control to be easier for future commitments. The plan encourages individuals to increase their savings rate when they receive their next raise, reducing the impact of loss aversion. By aligning savings with future expected income increases, the plan leverages inertia to help individuals save more for retirement.
Q: How did the default option and the urging to choose their own portfolios in the premium pension system in Sweden influence investor behavior?
The default option in the premium pension system, known as a p7, became the choice for two-thirds of Swedish investors. The urging to choose one's own portfolio resulted in the remaining one-third of investors making their own choices. However, over time, the number of investors choosing their own portfolios decreased significantly, with almost no one choosing their own portfolios in recent years. This suggests that the default option and inertia play a significant role in investor behavior, while the urging to choose one's own portfolio had temporary effects.
Q: How long can nudges last, based on the premium pension system in Sweden?
Nudges can last for at least 17 years, based on the premium pension system in Sweden. Even after the urging to choose one's own portfolio ended and new entrants to the system did not experience the advertising campaigns, the majority of Swedish investors still remain in the default option. This suggests that the original nudge to choose one's own portfolio had lasting effects on investor behavior.
Takeaways
The speaker's research in behavioral economics demonstrates that supposedly irrelevant factors can significantly impact decision-making and outcomes. By understanding choice architecture and using nudges, such as changing defaults and aligning decisions with future commitments, individuals can be guided towards making better choices. Nudges can help individuals overcome self-control problems, loss aversion, and inertia, improving their financial well-being. Furthermore, the lasting effects of nudges highlight their potential to shape long-term behavior and highlight the importance of choice architecture in influencing decisions.
Summary & Key Takeaways
-
Thaler traces behavioral economics from ordinary puzzles involving cashews, wine, and basketball tickets. These stories challenge predictions that more choice is always better, ownership should not affect valuation, and unrecoverable costs should not affect present decisions. They inspired research on self-control, the endowment effect, loss aversion, status quo bias, and mental accounting.
-
Research by Amos Tversky and Daniel Kahneman gave Thaler a framework for explaining these puzzles. People are boundedly rational and use simple rules of thumb when deciding. These heuristics produce not merely random errors but systematic biases, including availability bias, which distorts judgments when memorable events are mistaken for more frequent events.
-
A market experiment compared assigned-value tokens with Cornell coffee mugs. Tokens traded toward participants with the highest assigned values, as the Coase theorem predicted under low transaction costs. Mug trading reached about one third of the predicted level because owners resisted giving up mugs, illustrating loss aversion, status quo bias, uncertainty, and inertia.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from Nobel Prize 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator