How to Protect Savings From Inflation and Fees
TL;DR
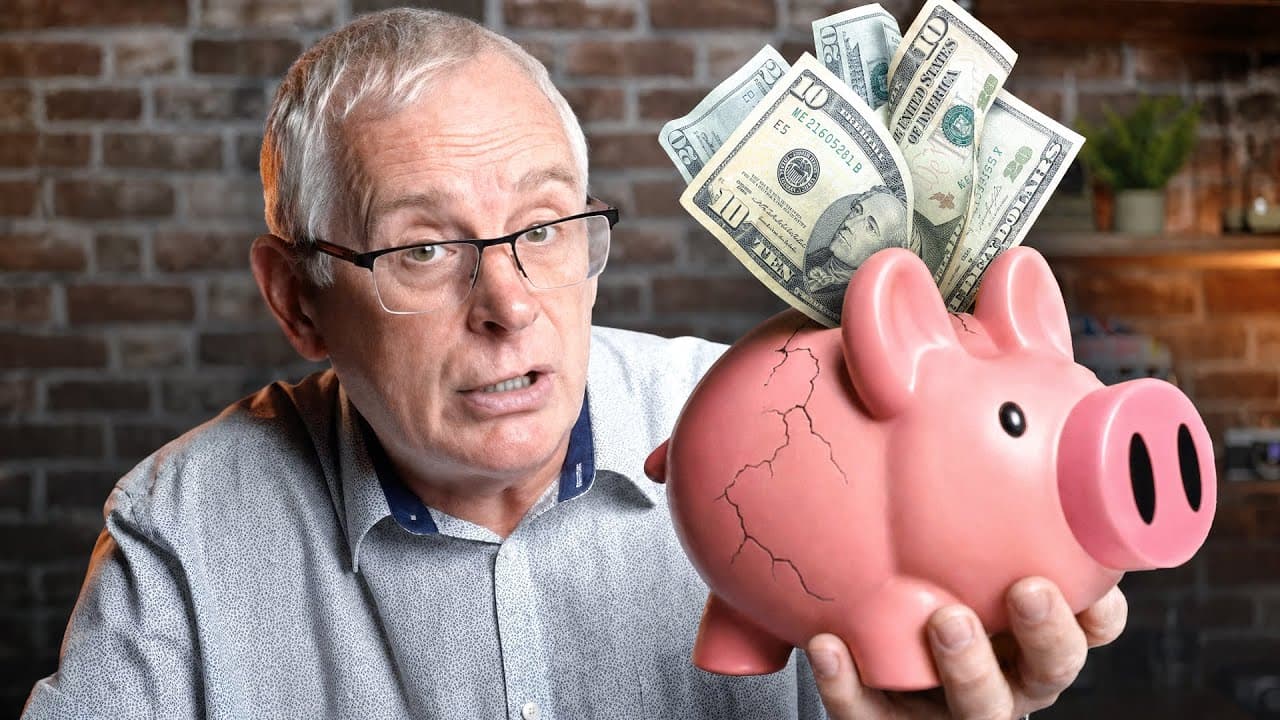
Keep three to five months of living expenses in an emergency fund, then consider putting additional money into assets rather than leaving everything in a low-interest savings account. The central argument is that inflation can reduce cash purchasing power, while low-cost index funds and money market funds may offer greater return potential, although investments can fall and are not guaranteed.
Transcript
- As soon as I left school, I started my first job and I saved every penny I made which made me a multimillionaire and gave me the life I'd always dreamed of. This statement isn't just false. It would've been downright impossible. The trouble is many people that want to get rich are falling for the money saving trap. Why? Because it's exactly what ... Read More
Key Insights
- Low-interest savings can lose purchasing power when inflation exceeds the interest earned. The transcript illustrates this with $10,000 earning 0.5% annually and argues that a larger future balance could still purchase less than the original amount because its real value declines over time.
- Fiat money is government-issued currency that is not backed by a physical commodity. Its accepted value depends on the monetary system, unlike the earlier gold-standard arrangement described in the transcript, which allowed money to be exchanged for gold before that system stopped in 1933.
- Gold and silver are presented as tools for protecting existing wealth rather than maximizing growth. The speaker considers them more suitable for wealthy people seeking security, while suggesting that younger people may prefer assets with more growth potential if they can tolerate the associated risk.
- Inflation can result from demand exceeding supply, rising production costs, or money supply expanding faster than product production. The transcript uses pandemic-era used-car demand, increasing construction costs and wages, and money introduced during lockdown as examples of these three mechanisms.
- An emergency fund should cover three to five months of living expenses. It is intended for genuine emergencies and should be accessed only as a last resort, which preserves short-term financial resilience while allowing money beyond that reserve to be considered for investment.
- Low-cost index funds offer a simple way to participate in the stock market over the long term. The transcript cites historical average yearly market returns of 8% to 10%, while explicitly acknowledging that these returns are not guaranteed and that past performance does not ensure future results.
- Investment fees directly reduce returns and should be examined before choosing a platform. The speaker specifically warns against paying a 1% fee whenever purchasing an ETF and favors transparent pricing, broad stock and ETF access, multicurrency accounts, and interest on uninvested cash.
- Money market funds invest in high-quality short-term debt issued by governments, banks, or corporations. They can offer better interest rates than savings accounts and relatively easy withdrawals, but the transcript warns that they are not insured or guaranteed and may lose value.
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: Why can saving money fail to build wealth?
Saving money can fail to build substantial wealth when the account earns less interest than the rate at which inflation reduces purchasing power. The transcript contrasts low savings rates with the greater return potential of invested assets. It does not argue for eliminating savings entirely, because it recommends keeping three to five months of living expenses available for emergencies.
Q: How does inflation reduce the value of savings?
Inflation reduces savings by increasing the prices of goods and services, meaning the same amount of money purchases less over time. The transcript gives a hypothetical example of $10,000 earning 0.5% annually for 1,000 years. Although the nominal balance would approach $1.5 million, the speaker argues that its purchasing power would be lower than the original $10,000.
Q: What causes inflation according to the transcript?
The transcript names three causes of inflation. Demand-pull inflation occurs when demand rises faster than available supply, as with used cars during the pandemic. Cost-push inflation follows increases in expenses such as construction materials and wages. Monetary inflation occurs when the money supply expands faster than the production of goods, leaving more money competing for limited products.
Q: How much money should an emergency fund contain?
An emergency fund should contain enough money to cover three to five months of living expenses, according to the transcript. This reserve should remain accessible and be used only as a last resort, not for spontaneous discretionary purchases or travel. The recommendation creates a distinction between necessary short-term savings and additional money that might be invested for potential growth.
Q: How can beginners invest beyond a savings account?
Beginners can consider using an investing app to purchase a low-cost index fund, such as one tracking the S&P 500, and hold it for the long term. The transcript says markets have historically produced average yearly returns of 8% to 10%, but it also states that returns are not guaranteed and investments can rise or fall in value.
Q: What should investors check before choosing an app?
Investors should check for transparent pricing, low fees, access to ETFs and money market funds, support for multiple currencies, interest on uninvested cash, and a broad selection of stocks. The transcript specifically warns that a 1% ETF purchase fee can reduce returns. It also favors platforms that allow fractional shares, which remove the need to purchase an entire share.
Q: What is a money market fund and is it guaranteed?
A money market fund invests in high-quality short-term debt from governments, banks, or corporations. The transcript presents these funds as potentially offering better interest rates than savings accounts, with easy access to money and yield paid monthly. However, it clearly warns that money market funds are not insured or guaranteed like protected savings accounts and may lose value.
Q: Why does waiting to invest have an opportunity cost?
Waiting to invest can create an opportunity cost when asset prices rise while cash remains in a low-interest account. The transcript uses Tesla as an example, stating that its stock moved from $700 to nearly $900 between August and October 2021, described as a 35% cost of waiting. Fractional shares allowed participation without buying one complete $700 share.
Summary & Key Takeaways
-
The central argument is that saving alone is unlikely to make someone wealthy while young because bank interest may fail to keep pace with inflation. Fiat currency is not backed by a physical commodity, and banks can use deposited funds for profitable lending and investment activities while paying depositors relatively little interest.
-
Inflation reduces what money can purchase over time. The transcript identifies demand-pull inflation, cost-push inflation, and money-supply growth as three contributing factors. It also distinguishes disciplined saving from consumption, recommending an emergency fund equal to three to five months of living expenses rather than spending every available dollar.
-
The proposed alternative is long-term investment through low-cost index funds such as an S&P 500 fund, alongside money market funds for lower-risk cash management. Investors should examine fees, available assets, multicurrency features, liquidity, and protections. The promoted platform and affiliate relationship create a commercial interest that viewers should recognize.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from Mark Tilbury 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator