How Would a 50-Year Mortgage Affect Homebuyers?
TL;DR
A 50-year mortgage would probably do little to improve housing affordability because lenders would likely charge a higher interest rate for the added risk. Even without that premium, borrowers would build equity much more slowly and pay far more interest, while additional borrowing power could raise home prices in a market constrained by limited supply.
Transcript
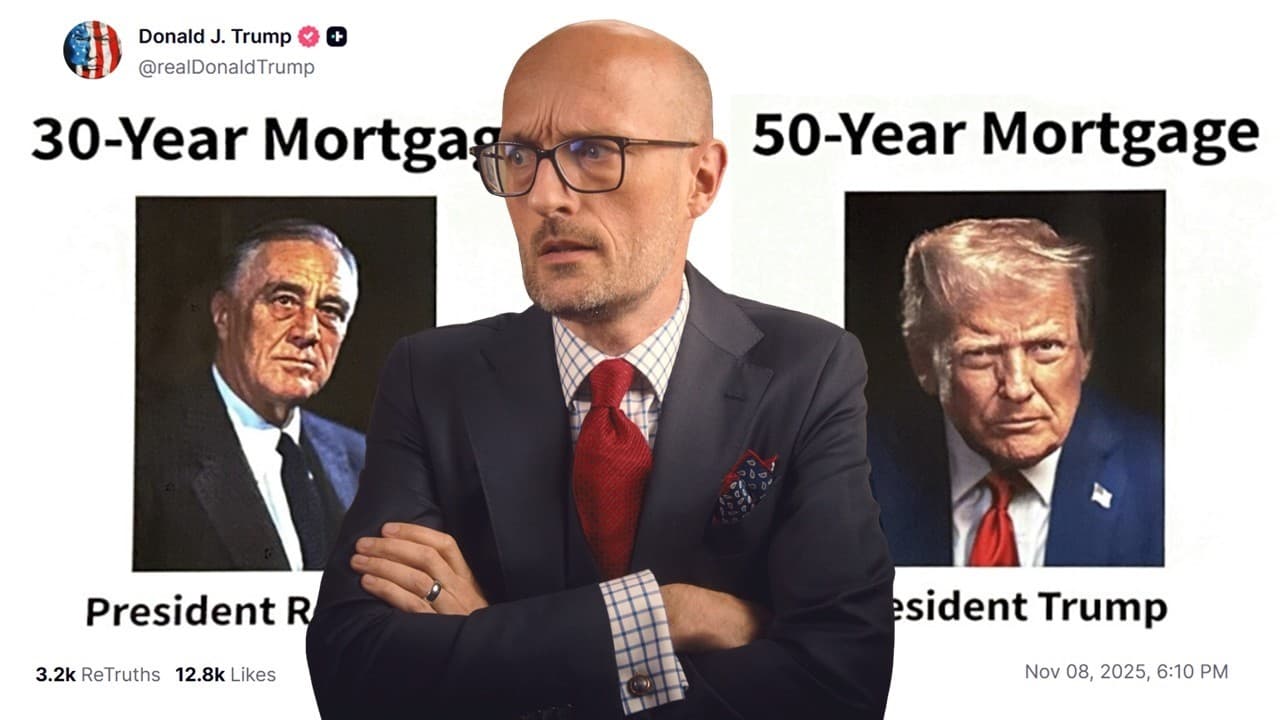
Last weekend, President Trump tweeted the idea of creating a 50-year mortgage as a way to help lower payments for Americans who want to buy a home. Federal Housing Finance Agency Director Bill Pulte called the proposal “a complete game changer.” It might sound clever – but it just isn’t. Let’s look at why stretching debt across half a century wo... Read More
Key Insights
- A 50-year mortgage is unlikely to deliver its advertised payment savings because lenders normally demand compensation for the greater risk of a longer commitment. Analysts estimate that its interest rate could be 75 to 100 basis points above the rate on a 30-year mortgage.
- The apparent monthly saving depends on assuming identical interest rates across mortgage terms. At the same rate, the average American mortgage payment could fall by around $250 a month, but the expected rate premium could erase that reduction or even produce a higher payment.
- Equity builds much more slowly when amortization is stretched across half a century. After a decade, the example estimates roughly $60,000 of equity with a 30-year mortgage but only about $11,000 with a 50-year loan, assuming no house-price appreciation.
- Lifetime interest costs rise dramatically with a longer mortgage term. At an interest rate of 6.4%, the example says the average American would pay around half a million dollars in interest on a 30-year mortgage and more than a million dollars on a 50-year mortgage.
- Housing supply is the central affordability constraint described in the analysis. When additional borrowing power enters a market with too few homes, buyers can bid prices higher, allowing the increased demand to absorb the promised benefit of lower monthly payments.
- The 30-year fixed-rate mortgage emerged from federal intervention during the Great Depression. Government-backed bonds, mortgage insurance, and the secondary market created by Fannie Mae and Freddie Mac helped replace short loans and balloon payments with longer, self-amortizing mortgages.
- The American mortgage system gives borrowers predictable fixed payments and the ability to refinance when rates fall. This arrangement protects existing homeowners, but it can reduce mobility when rates rise because homeowners may be reluctant to surrender favorable loans.
- A 50-year mortgage would require a change in federal law before becoming widely available. The transcript states that qualified mortgages under the Dodd-Frank Act cannot have terms longer than 30 years, making legislation necessary for lenders to offer the product at scale.
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: Would a 50-year mortgage lower monthly payments?
A 50-year mortgage might lower payments if it carried the same interest rate as a 30-year mortgage. Under that assumption, the example presented estimates a reduction of around $250 a month on the average American mortgage. However, analysts expect lenders to charge 75 to 100 additional basis points for the longer term, which could eliminate the saving or make the payment higher.
Q: Why would a 50-year mortgage have a higher interest rate?
A 50-year mortgage exposes lenders and investors to risk for a much longer period, so they would be expected to demand additional compensation. The longer structure would also affect how lenders price mortgages and how investors value mortgage-backed securities. According to the analysis, this risk premium could add 75 to 100 basis points compared with a 30-year loan, undermining the proposed payment benefit.
Q: How would a 50-year mortgage affect home equity?
A 50-year mortgage would build equity much more slowly because early payments would be dominated by interest while only a small amount reduced the principal. The example estimates that after a decade, a borrower with a 30-year mortgage would have roughly $60,000 in equity, compared with about $11,000 under a 50-year mortgage, assuming the home did not appreciate.
Q: How much interest could a 50-year mortgage cost?
The example uses an interest rate of 6.4% to show how extending repayment can sharply increase total interest. It estimates that the average American would spend around half a million dollars on interest with a 30-year mortgage. Stretching the same debt across 50 years would raise the interest expense alone to more than a million dollars, even before considering a likely rate premium.
Q: Why could longer mortgages raise home prices?
Longer mortgages could let buyers qualify for larger loans by spreading repayment across more time. In a housing market where supply is limited, that additional purchasing power would allow buyers to bid more aggressively for the same homes. The analysis argues that sellers and developers could capture the financing benefit through higher prices, erasing much of the improvement in affordability.
Q: What created the 30-year fixed-rate mortgage in America?
The 30-year fixed-rate mortgage developed from federal efforts to stabilize housing during the Great Depression. Earlier loans commonly had terms of 10 years or less, required interest payments, and ended with balloon payments. The government purchased defaulted mortgages, reissued them as longer fixed-rate loans, supported them with insurance, and later expanded the secondary market through Fannie Mae and Freddie Mac.
Q: What legal obstacle would a 50-year mortgage face?
A 50-year mortgage could not simply be introduced at scale within the qualified-mortgage framework described in the transcript. Under the Dodd-Frank Act, qualified mortgages cannot have terms longer than 30 years. Federal legislation would therefore need to change before lenders could broadly offer such a product, adding a major legal and political obstacle to the proposal.
Q: What would address housing affordability more directly?
Increasing the supply of homes would address the constraint identified as the main affordability problem. The analysis argues that Americans are not primarily blocked because loans are too short, but because there are not enough homes available. Expanding credit without expanding supply would mainly increase competition among buyers, push prices upward, and transfer much of the intended benefit to sellers or developers.
Summary & Key Takeaways
-
Extending mortgage terms appears to reduce monthly payments, but the calculation changes once lenders price the additional risk of a much longer loan. Analysts cited in the discussion estimate that the interest-rate premium could eliminate most or all of the expected payment reduction, leaving borrowers indebted for much longer without meaningful monthly relief.
-
The longer repayment schedule would direct a larger share of early payments toward interest and a smaller share toward principal. Compared with a 30-year mortgage, borrowers would accumulate substantially less equity during their likely period of homeownership and could pay more than a million dollars in total interest under the example presented.
-
Housing affordability is fundamentally constrained by limited supply, according to the argument presented. Giving buyers more borrowing capacity without creating additional homes would intensify competition and raise prices. Historical lending programs and longer auto or student loan terms illustrate how easier financing can increase debt burdens without solving the underlying shortage or cost problem.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from Patrick Boyle 📚

Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator