What happens to your finances at every net worth level
TL;DR
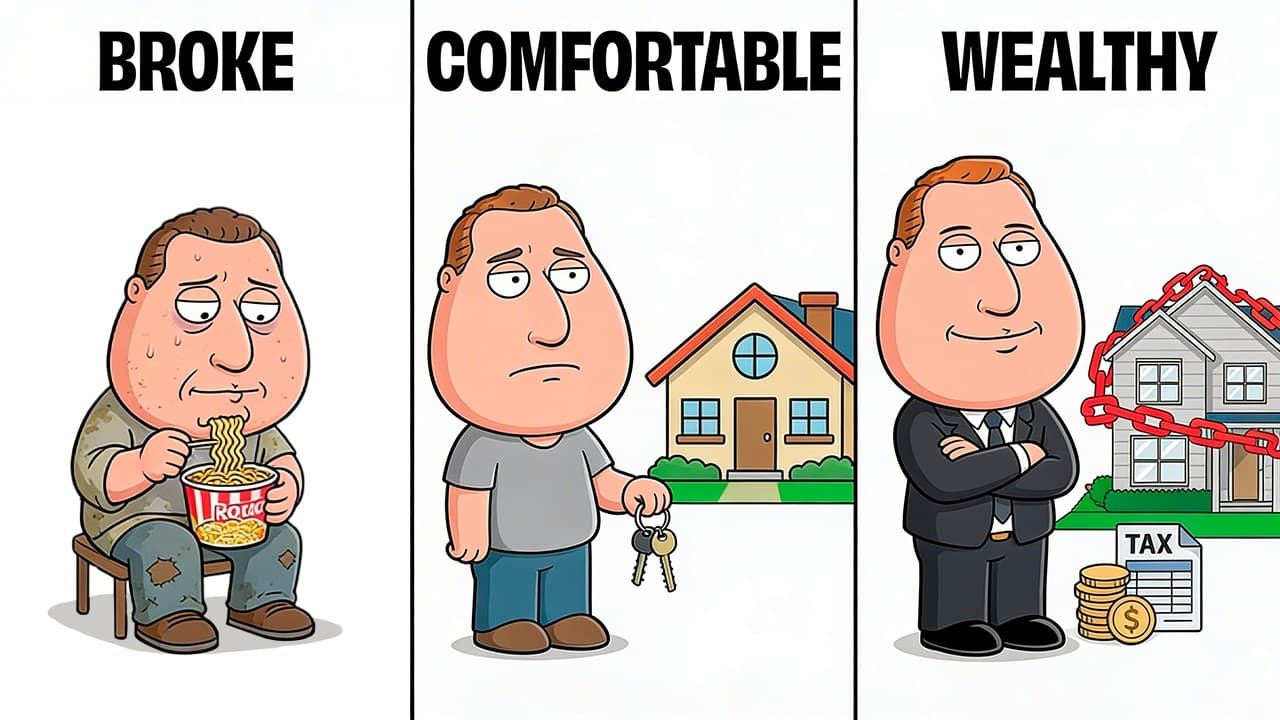
Your net worth reflects life stages, not a single score. Early levels trap people with overdraft fees and high debt, then gradual gains expose lifestyle creep and the real cost of big purchases. The turning point comes from automation and investing, which unlocks meaningful growth beyond mere saving.
Transcript
You're sitting at your kitchen table at 11:00 p.m. on a Wednesday, laptop open, and you're doing something you've been putting off for 3 months. Calculating your actual net worth, not the vague mental estimate you carry around that makes you feel okay. The real number, assets minus debts. What you actually own minus what you actually owe. So, you a... Read More
Key Insights
- Level one is negative net worth and exposes the trap of overdraft fees and payday loans.
- Level two offers a small cushion but teaches that relief can become a spending trap if not managed.
- Level three shows money growing through a brokerage account and the importance of using Roth IRAs and employer matches.
- Level four highlights the house and car squeeze, where depreciation and fixed costs threaten progress even with higher income.
- Level five explains the math of the first $100,000 being the hardest hurdle and the impact of compounding as wealth grows.
- Level six introduces the golden handcuff where high income becomes tied to a lifestyle that is hard to quit.
- Level seven would continue the pattern of traps and automation, emphasizing moving money before it is seen.
- Automation and consistent investing become the exit strategy that separates levels and enables true progress.
- More videos from this channel:
- More from this channel: Nick Invests
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: How does net worth progress relate to daily life at different levels?
Net worth is described as a description of the version of life you are living, not just a number. At Level one, a small crisis feels catastrophic due to fixed expenses and debt. As you move to higher levels, the same income can support different lifestyles, highlighting how debt, spending, and priorities shape everyday life.
Q: What is the trap at Level one for new graduates?
The trap at Level one is the extra charges from a financial system that treats being broke as a risk to the bank. Overdraft fees and payday loan costs create a cycle where small mistakes become costly, forcing early financial instability and long paths toward stability unless bleeding is stopped.
Q: Why is Level three considered a turning point for money working?
Level three introduces the idea that money must work through investing rather than remaining in savings at near zero percent. With an employer match and a Roth IRA, the potential growth becomes real, turning idle funds into compounding momentum and moving toward a healthier long-term trajectory.
Q: What does the mortgage and car squeeze look like at Level four?
At Level four, a higher fixed cost structure with mortgage and car payments competes with take-home pay. Despite a higher gross income, most of the budget goes to housing and transportation, and depreciation further erodes the value of large purchases, creating a risk to progress.
Q: How is the first $100,000 described in Level five?
Level five frames the first $100,000 as a barrier that takes significant time to reach, illustrating that the early accumulation period is the most arduous. The math shows that compounding becomes more impactful after this hurdle, with the next increments growing faster as the base increases.
Q: What is the golden handcuff at Level six?
The golden handcuff occurs when both partners are anchored to a lifestyle scaled to a certain income, making it hard to quit jobs or reduce spending even if better opportunities exist. This trap is subtle because life feels comfortable, yet mobility and true security hinge on changing spending and income structure.
Q: What role does automation play across the levels?
Automation is presented as the exit from many behavioral traps. By moving money before it is seen and increasing savings automatically, you reduce the need for heroic monthly efforts. This shift leverages consistent investing to transform the path from Level one to financial independence.
Q: Why is the 4% rule mentioned and what does it imply?
The 4% rule is used to illustrate how much income a portfolio can safely generate at higher levels. At Level six, $340,000 yields about $13,600 per year, which is not enough for retirement but signals that investments are starting to provide meaningful, reliable income and reduce reliance on active work.
Summary & Key Takeaways
-
Level one shows negative net worth and how overdraft fees and payday loans trap recent grads, setting a harsh starting point for financial progress.
-
Level two introduces a small cushion but warns that relief can become a trap as lifestyle creep quietly drains savings and raises expenses.
-
Level three marks some growth and the realization that money must work through investing, not just sitting in a savings account, to beat inflation.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from Nick Invests 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator