Why Does a $300,000 Net Worth Feel Like Nothing in 2026?
TL;DR
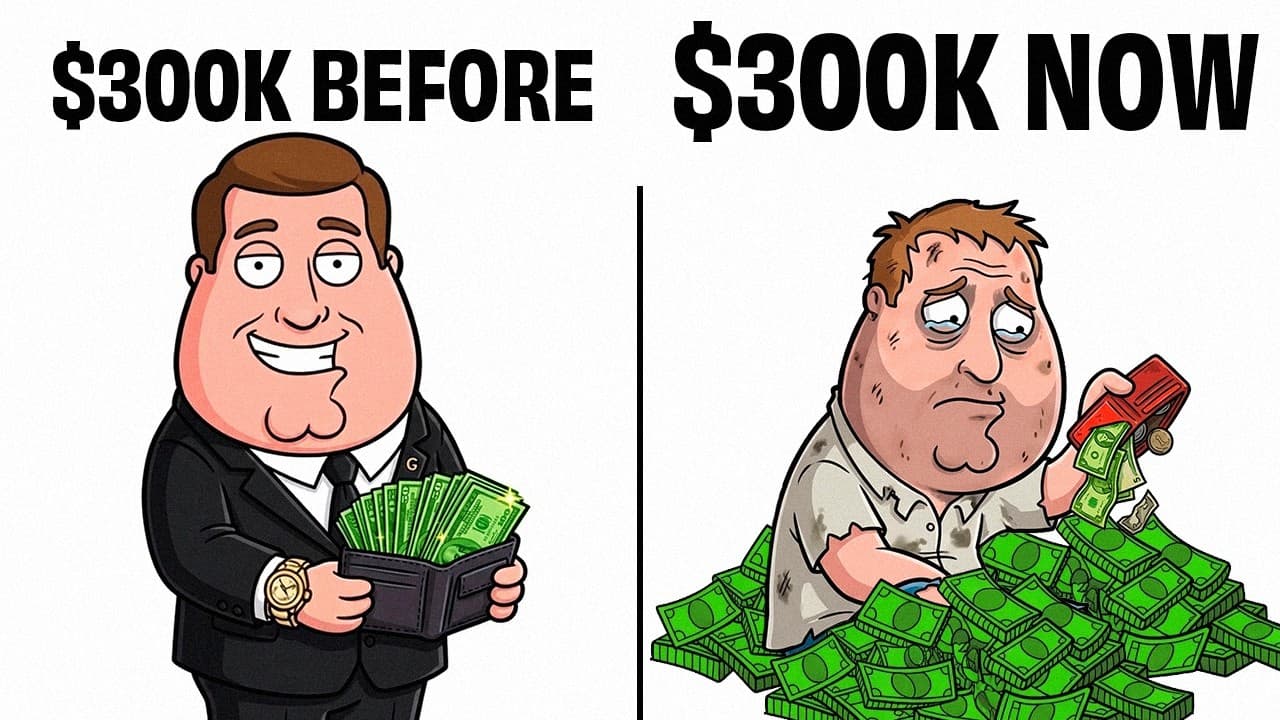
A $300,000 net worth can feel financially fragile because inflation has weakened its purchasing power and a large share may be locked in home equity rather than available as cash. Although that amount puts Marcus and Diane ahead of roughly 60% of American households, rising housing, insurance, and child-rearing costs make the achievement feel less secure. Read on to understand the gap between net worth on paper and money you can actually use.
Transcript
Two guys, same age, same neighborhood, same mortgage payment, same beat up Toyota in the driveway, same Tuesday night habit of watching something on Netflix they'll forget by Thursday. One of them opens his investment app after dinner, sees $300,000 staring back at him, and exhales. Feels like he's getting somewhere, like the years of brown bag lun... Read More
Key Insights
- A $300,000 net worth is above the median household net worth of $192,700 and places a household ahead of roughly 60% of American households. It is therefore substantial by ordinary household standards, even when it does not create a strong subjective feeling of wealth.
- Wealth concentration distorts financial comparisons because the top 1% of American households holds 31.7% of US wealth, while the top 10% controls 67% and the bottom 50% owns 2%. Comparing an ordinary household with the wealthiest households can make genuine progress appear insignificant.
- Inflation has reduced the real meaning of a $300,000 balance because cumulative inflation from 2016 to 2026 was roughly 35%. Today’s $300,000 buys approximately what $221,700 bought ten years earlier, leaving its purchasing power about 26% below what the account balance suggests.
- Essential family costs have risen faster than the general inflation figure. Median home prices increased roughly 77% over the decade, family health insurance premiums rose 49%, and the estimated cost of raising one child through age 18 reached $414,000.
- Home equity is wealth without immediate liquidity because it accounts for roughly 68% of median household net worth. A household with $300,000 in total net worth may consequently have only about $96,000 that is accessible without selling its home or taking on additional debt.
- The 4% rule turns a $300,000 investment portfolio into approximately $12,000 of annual withdrawals, or $1,000 per month. Adding the average Social Security benefit of about $24,900 produces roughly $36,900, compared with average retiree household spending of $61,432.
- Critical mass occurs when annual portfolio growth exceeds annual personal contributions. At a 7% real return, $300,000 generates $21,000 per year, which surpasses Marcus’s annual contribution of $18,000 and allows investment growth to become the larger driver of future wealth.
- Family obligations can consume a substantial portfolio without involving luxury spending. A six-month emergency fund costs $38,640, one child’s four-year education at an in-state public university costs $124,000, and two years of assisted living for one parent costs about $141,600.
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: Why can a $300,000 net worth still feel financially fragile in 2026?
Inflation has reduced what $300,000 can buy, while major household costs have risen sharply. The money may also include substantial home equity that cannot be accessed without selling the home or taking on debt, making the household feel less secure than its net worth suggests.
Q: Is a $300,000 net worth above the typical American household?
Yes. The transcript says $300,000 puts Marcus and Diane ahead of roughly 60% of American households, while the median household net worth is $192,700. It is meaningful progress even if it does not feel like wealth.
Q: How does wealth inequality affect perceptions of a $300,000 net worth?
Extreme wealth at the top distorts comparisons and makes an ordinary household’s progress appear small. The transcript says the top 1% holds 31.7% of US wealth, while the top 10% controls 67%, so comparing $300,000 with highly visible fortunes can create a misleading sense of inadequacy.
Q: How has inflation affected the purchasing power of $300,000?
The transcript states that cumulative inflation from 2016 to 2026 was roughly 35%. It says today’s $300,000 buys what $221,700 bought 10 years ago, so the balance has substantially less real purchasing power than its headline value implies.
Q: Which household costs make $300,000 feel smaller?
Housing, family health insurance, and raising children are identified as major pressures. The transcript says median home prices rose roughly 77% over the last decade, family health insurance premiums jumped 49%, and the cost of raising a child increased sharply.
Q: Why is home equity different from accessible wealth?
Home equity contributes to net worth but is not cash that can be used immediately. Accessing it generally requires selling the home or taking on additional debt, so a household can have substantial wealth on paper while possessing much less readily available money.
Q: How do Marcus and Diane illustrate financial fragility?
Marcus and Diane are 43, have two children, earn a combined household income of $115,000, and recently crossed $300,000 in net worth. Despite saving through their retirement accounts and mortgage, inflation, family costs, and illiquid home equity leave them uncertain about what that milestone actually provides.
Q: What is the main lesson of reaching a $300,000 net worth?
The number should be evaluated by purchasing power, liquidity, and household obligations rather than treated as a complete measure of security. A $300,000 net worth represents genuine progress, but its practical value depends on where the assets are held and what expenses the household must face.
Summary & Key Takeaways
-
A $300,000 net worth places a household ahead of roughly 60% of American households, yet comparisons with extreme wealth and rising perceptions of financial comfort can make it feel inadequate. Americans reported needing $839,000 for comfort and $2.3 million to feel wealthy in the 2025 Schwab Modern Wealth Survey.
-
Inflation and asset composition explain why the headline number can feel disconnected from daily security. Today’s $300,000 has the purchasing power of about $221,700 from 2016, while home equity represents roughly 68% of median household net worth and cannot be accessed without selling property or assuming debt.
-
The long-term value of $300,000 depends heavily on time and investment growth. At a 7% real return, it generates $21,000 in annual growth and can exceed $1.3 million by age 65 without additional contributions. Immediate family obligations, however, can interrupt that compounding process and reduce retirement security.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from Nick Invests 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator