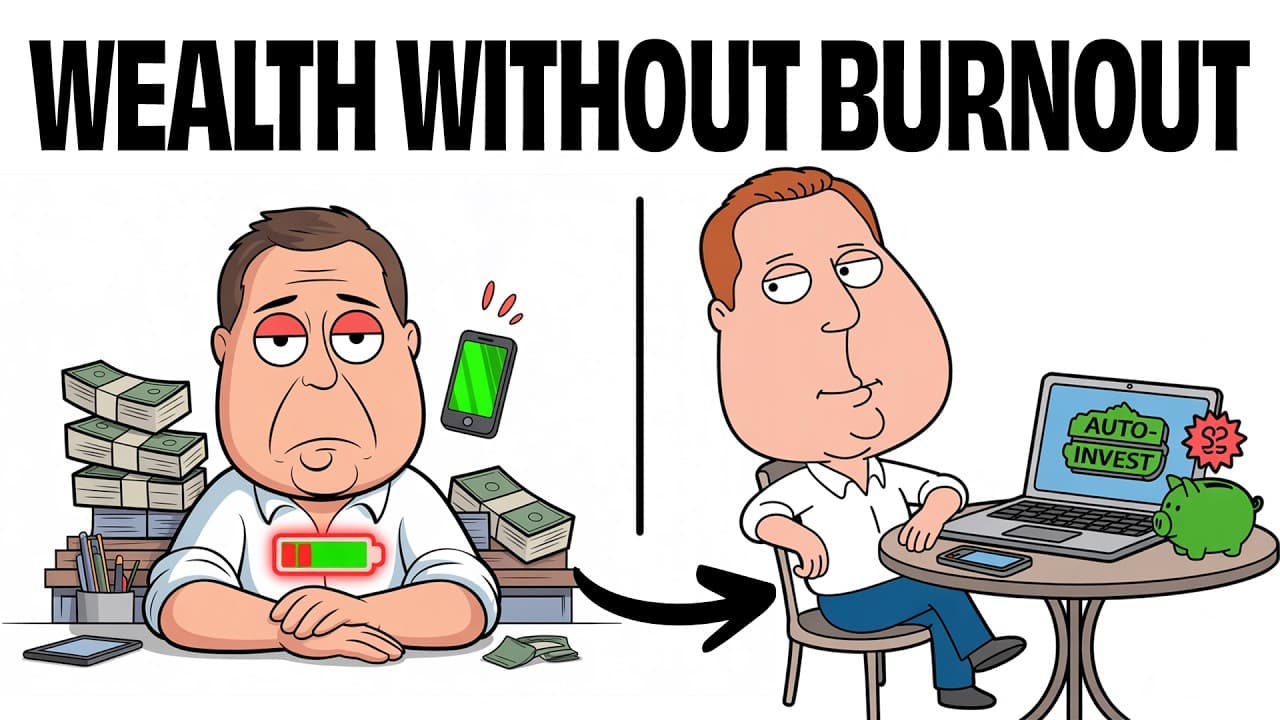
How to Build Lasting Wealth Without Burning Out
TL;DR
Build lasting wealth without burning out by defining clear goals, using a realistic spending plan, and automating savings and investments when each paycheck arrives. Establish an emergency fund before pursuing investment growth, then let compound interest work over time. This sustainable system reduces repeated decisions while preserving room for relationships, hobbies, and enjoyment. Read on for the eight principles that make it practical.
Transcript
You know that feeling when you're grinding at work, constantly thinking about money, but you're absolutely exhausted, your relationships are suffering, you're checking your portfolio obsessively every single day, and if you stop for even a second, you feel like everything falls apart. Sound familiar? Well, what if building real wealth doesn't actua... Read More
Key Insights
- Sustainable wealth is created through a system that can operate consistently without demanding constant attention, emotional energy, or personal sacrifice. The objective is not simply reaching wealth as quickly as possible, but creating a process that remains compatible with health, relationships, hobbies, and an enjoyable life.
- An abundance mindset focuses on increasing income and building assets rather than relying exclusively on expense reduction. Avoiding waste remains important, but continual restriction can create feelings of deprivation, lead to burnout, and eventually trigger spending that undermines previous saving efforts.
- Clear financial goals turn vague hopes into measurable direction. Defining what financial independence means personally, such as retiring at a chosen age, maintaining an emergency reserve, or receiving income from rental properties, makes it possible to work backward and establish a concrete savings strategy.
- A budget is a spending plan that directs money toward intended purposes before it disappears into unplanned purchases. Knowing what is available for housing, food, transportation, entertainment, and savings can make spending feel more liberating because affordability decisions have already been incorporated into the plan.
- Willpower is a limited resource, so a financial strategy that requires repeated manual decisions is difficult to sustain. Automating transfers when income arrives removes recurring choices, converts good intentions into dependable actions, and lets wealth accumulation continue while attention remains available for other priorities.
- Automatic saving reduces the feeling of deprivation because allocated money is moved before it becomes available for everyday spending. People can then adjust their lifestyle to the remaining amount, preserving room for friends, hobbies, and enjoyment while savings and investments accumulate in the background.
- An emergency fund is both a financial reserve and a psychological safety net. It can cover unexpected expenses without forcing the sale of investments during an unfavorable period or creating high-interest debt, helping prevent panic-driven decisions and reducing ongoing financial anxiety.
- Compound interest works when investment returns generate additional returns over time. Starting earlier gives that process more time to operate, which can make timing more important than searching for individual stocks, cryptocurrencies, or supposedly secret strategies intended to produce rapid wealth.
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: How can you build wealth without burning out?
Build a sustainable system that does not require constant attention or repeated willpower. Set clear financial goals, create a realistic spending plan, and automate transfers to savings and investments when each paycheck arrives. This allows wealth to accumulate while preserving time and energy for relationships, hobbies, and enjoyment.
Q: Why is automation important for building wealth?
Automation turns financial intentions into consistent actions without requiring monthly decisions. When a paycheck arrives, predetermined transfers can direct money immediately to savings, retirement accounts, and investments. You then organize everyday spending around what remains.
Q: How should a budget support financial independence?
Treat a budget as a spending plan that assigns money to rent, groceries, transportation, entertainment, savings, and other priorities. Knowing what each category can receive reduces uncertainty about what you can afford. The plan should include enjoyment so that it remains sustainable rather than feeling like constant restriction.
Q: Why can a scarcity mindset undermine saving?
Constantly restricting spending can create deprivation and eventually cause someone to abandon the plan or blow their savings. Avoiding waste remains important, but sustainable wealth building also focuses on earning more and creating income-generating assets. That shift makes the process feel constructive instead of punishing.
Q: What financial goals should you define before saving?
Choose a specific outcome, such as retiring at 50, saving 6 months of expenses, or owning rental properties that generate passive income. Then work backward to determine how much you need to save. This turns a vague desire for wealth into a concrete strategy.
Q: Why should an emergency fund come before investment growth?
An emergency fund covers unexpected costs without forcing you to sell investments during an unfavorable period or rely on high-interest debt. It also provides a psychological safety net that can reduce panic and financial anxiety. With that reserve in place, long-term investments can remain untouched during ordinary disruptions.
Q: How does compound interest help investments grow?
Compound interest allows investment returns to generate additional returns over time. Starting earlier gives that process more time to operate. The transcript therefore emphasizes time over chasing individual stocks, cryptocurrencies, or supposedly secret strategies for rapid wealth.
Q: Should wealth building focus on cutting expenses or increasing income?
It should combine sensible spending with efforts to increase income and build assets. Cutting waste can help, but relying entirely on restriction can cause burnout. The more sustainable approach creates systems that generate income while leaving room for the parts of life that matter.
Summary & Key Takeaways
-
Sustainable wealth building depends on a repeatable system rather than constant effort, deprivation, or obsessive portfolio monitoring. Clear goals define the desired outcome, while a practical spending plan assigns income to living costs, enjoyment, savings, and investments. This structure can reduce financial anxiety by replacing vague intentions with deliberate decisions.
-
Automation turns financial intentions into consistent actions by moving money to savings, retirement accounts, and investments when income arrives. Because the allocated money is removed before it can be spent, the remaining income naturally defines the available lifestyle. This reduces decision fatigue and dependence on limited willpower each month.
-
An emergency fund should come before aggressive investing because unexpected costs can otherwise force an investor to sell assets during unfavorable conditions or use high-interest debt. After establishing that safety buffer, long-term investing can benefit from compound interest, where accumulated returns generate additional returns and time becomes a major advantage.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from Nick Invests 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator