How to Maximize Tax Savings with iDeCo Changes
TL;DR
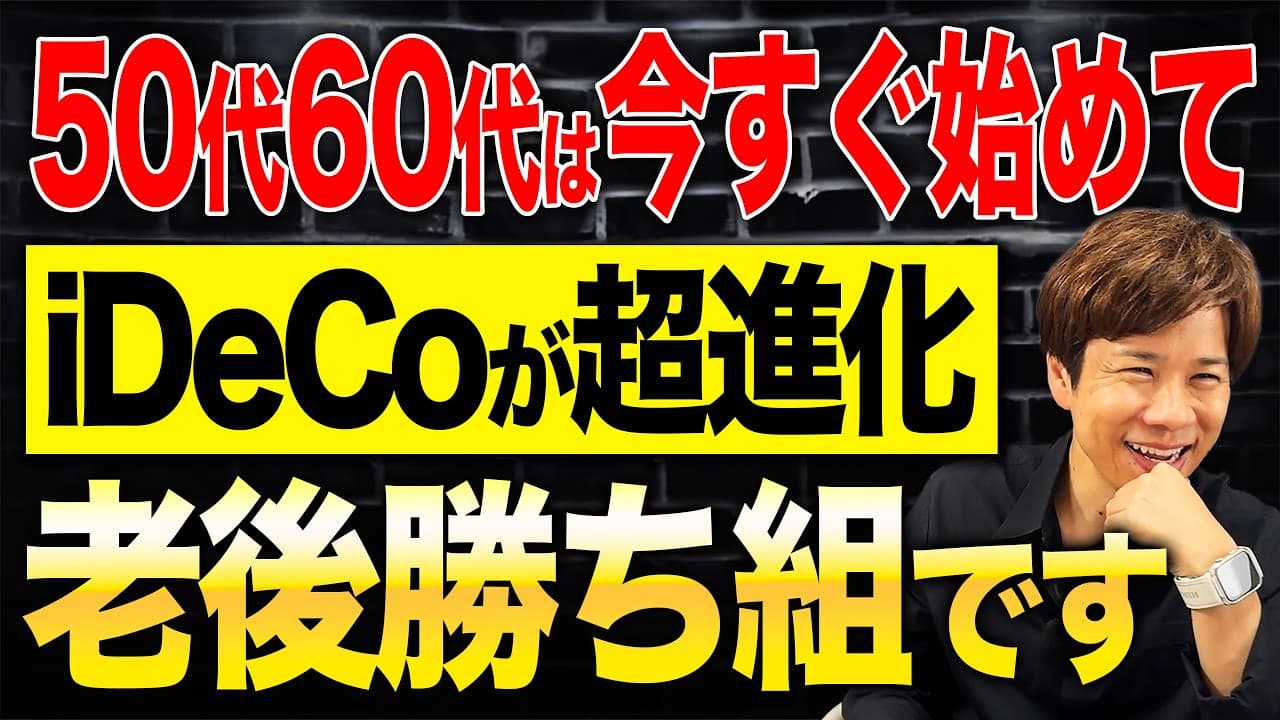
The recent changes to iDeCo increase contribution limits, offering significant tax savings. However, funds are locked until age 60, making it unsuitable for those who may need early access. Compare iDeCo with NISA or mutual funds to decide which best suits your financial goals and life stage.
Transcript
If you save 900,000, your taxes go down by 500,000. If you're not careful, the taxes you pay when you finally withdraw might exceed the tax savings. Hello. I'm Sugawara from the Tax Agency . Mr. Sugawara. iDeCo contribution limits are being raised significantly. What kind of impact will those changes have? Yeah. Well, you can save a lot on taxes . ... Read More
Key Insights
- iDeCo contribution limits are increasing significantly, allowing for greater tax deductions.
- Funds contributed to iDeCo are locked until age 60, which can be a disadvantage for those needing early access.
- The new iDeCo limits vary by category: Category 1 insured persons can contribute up to 75,000 yen monthly.
- Category 2 insured persons without corporate pensions can contribute up to 62,000 yen monthly.
- Category 3 insured persons, such as homemakers, have unchanged limits at 23,000 yen monthly.
- The enrollment age limit for iDeCo has been raised from under 65 to under 70.
- iDeCo offers guaranteed tax savings, but investing in NISA or mutual funds may yield better returns through compounding.
- Balancing iDeCo contributions with other retirement plans is crucial to avoid high taxes upon withdrawal.
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: How do the iDeCo contribution limits change?
The iDeCo contribution limits have been increased significantly. For Category 1 insured persons, the limit is now 75,000 yen per month, up from 68,000 yen. Category 2 insured persons can contribute up to 62,000 yen monthly if they do not have a corporate pension. Category 3 insured persons, such as homemakers, remain at 23,000 yen monthly.
Q: Who benefits most from the iDeCo changes?
Individuals in the highest tax brackets benefit most from iDeCo changes due to the substantial tax deductions. These deductions can significantly reduce their tax burden, making iDeCo an attractive option. However, those in lower tax brackets may find other investment options more beneficial due to iDeCo's fund accessibility limitations.
Q: What are the disadvantages of iDeCo?
The main disadvantage of iDeCo is that funds are locked until age 60, which can be problematic for those who might need early access to their money. Additionally, upon withdrawal, taxes are still applicable, which may offset some of the initial tax savings. It's crucial to balance iDeCo contributions with other retirement plans to avoid high taxes.
Q: How does iDeCo compare to NISA?
While iDeCo offers guaranteed tax savings, NISA allows for tax-free growth on investments, which can result in higher returns through compounding. NISA provides more flexibility, as funds can be accessed more freely, making it a better option for younger investors or those who might need liquidity.
Q: What are the new age limits for iDeCo enrollment?
The age limit for enrolling in iDeCo has been raised from under 65 to under 70. However, even if you enroll at 65, you cannot withdraw the funds immediately; they must be managed for at least five years, which means the funds are effectively locked until age 70.
Q: Why might someone choose NISA over iDeCo?
Someone might choose NISA over iDeCo if they prioritize investment growth through compounding and need more flexibility with their funds. NISA allows for tax-free growth and more accessible funds, which can be advantageous for those who may need to access their investments before age 60.
Q: What should younger investors consider when choosing between iDeCo and NISA?
Younger investors should consider their financial goals, tax bracket, and need for liquidity when choosing between iDeCo and NISA. While iDeCo offers tax savings, NISA might provide better long-term growth through compounding. Evaluating personal financial situations and future needs is crucial in making the right choice.
Q: How does the iDeCo tax deduction work?
The iDeCo tax deduction reduces taxable income by the amount contributed, allowing significant tax savings. For example, contributing 900,000 yen annually can reduce taxes by approximately 500,000 yen, especially for those in the top tax bracket. However, taxes apply upon withdrawal, which should be considered when planning retirement.
Summary & Key Takeaways
-
iDeCo's recent changes increase contribution limits, offering significant tax savings. However, funds are locked until age 60, which may not suit everyone. It's important to compare iDeCo with other options like NISA or mutual funds based on your financial goals and life stage.
-
For those in the top tax bracket, iDeCo offers substantial tax savings, reducing tax burdens significantly. However, those in lower tax brackets may benefit more from other investment options due to iDeCo's limitations on fund accessibility.
-
The decision to invest in iDeCo, NISA, or mutual funds depends on individual financial situations and goals. While iDeCo provides guaranteed tax savings, NISA or mutual funds may offer better returns through compounding, especially for younger investors.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from 脱・税理士スガワラくん 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator