How Income Changes Life From $25K to $25 Million
TL;DR
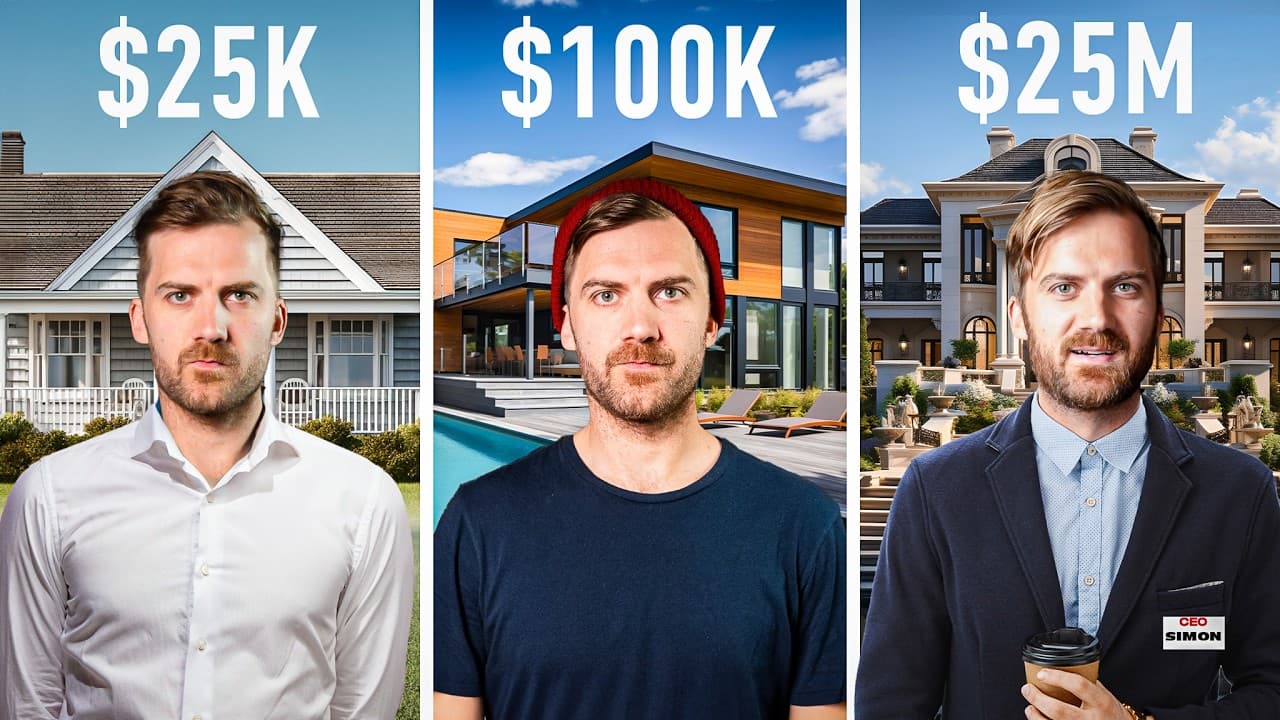
A $25,000 salary can fail to cover basic living costs even when a person works full time above the federal minimum wage. At $40,000, food, housing, healthcare, and modest entertainment become more manageable, but little remains for emergencies, while the comparison argues that widening income inequality produces radically different levels of security and choice.
Transcript
- This is what a $25 million a year salary looks like versus a $25,000 a year salary. About 20% of Americans live on this amount of money or less. I wanna show you the lifestyles of people who make this much money versus this much money and everything in between. The reason I wanna look at these differences is because of this graph, it's going up, ... Read More
Key Insights
- A $25,000 annual salary equals roughly $2,000 per month before taxes and about $1,764 after taxes in the presented Atlanta scenario. Although the security job pays $12.50 per hour, substantially above the stated $7.25 minimum wage, its full-time income still does not cover every modeled expense.
- Housing is the largest modeled expense for the $25,000 earner, consuming about 41 percent of pre-tax income, or approximately $850 per month. That budget pushes the worker outside downtown Atlanta, makes homeownership unrealistic, and may require roommates because many landlords expect income equal to three times the monthly rent.
- Transportation is a required expense in the Atlanta scenarios because the workplaces lack convenient public transportation connections. The $25,000 earner allocates $313 monthly for gas, insurance, parking, maintenance, and repairs while relying on an assumed already-owned 2004 Toyota Solara and limiting unnecessary driving.
- Food is allocated 15 percent of pre-tax income for the $25,000 earner, which equals $313 per month. The budget emphasizes inexpensive groceries such as beans, rice, bread, peanut butter, ramen, freezer meals, potatoes, and cheaper produce, with restaurant meals reserved for rare occasions or value menus.
- Government food assistance is unavailable to the modeled $25,000 earner under the eligibility figures presented. The scenario says savings must remain below $2,000 and income below $19,578, so the worker meets the savings condition but exceeds the stated income threshold despite struggling to cover basic costs.
- Healthcare is modeled at about 10 percent of income for the $25,000 earner, even with government help. Medicine, doctor visits, and care outside insurance coverage remain personal expenses, and the comparison states that people in this income bracket live around seven years less than the richest Americans.
- A $40,000 annual salary produces just under $2,700 per month after federal and state taxes in the modeled budget. It supports a one-bedroom rental, an older purchased vehicle, better grocery choices, employer-subsidized healthcare, a low-cost gym, and modest entertainment, but leaves little dependable savings.
- Emergency resilience remains weak at both $25,000 and $40,000 in the presented scenarios. The lower earner may depend on credit cards, high-interest short-term loans, parents, a second job, Uber, or DoorDash, while the median earner can reach the end of the month near zero after ordinary entertainment.
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: Can a single person live on $25,000 a year in Atlanta?
A single person earning $25,000 in the modeled Atlanta budget receives about $1,764 per month after taxes, but the listed necessities do not fit comfortably within that amount. Housing takes about $850, transportation and food each take $313, and healthcare plus phone, internet, and laundry add further costs. The result is no emergency fund and likely reliance on debt, extra work, or family support.
Q: How much does a $25,000 earner spend on housing?
The modeled $25,000 earner spends about 41 percent of pre-tax income on housing, based on Bureau of Labor Statistics data used in the comparison. That provides approximately $850 per month for rent and utilities. At this level, living downtown is unaffordable, buying a home is not considered realistic, and roommates may be necessary to satisfy landlord income requirements.
Q: Why does transportation strain a low-income budget?
Transportation strains the $25,000 budget because the worker lives outside downtown Atlanta but must commute to a downtown job without useful public transportation. The scenario allocates $313 per month for gas, insurance, parking, maintenance, and repairs. It also assumes the worker already owns a 2004 Toyota Solara, while any major repair could cause a serious financial setback.
Q: What food can someone afford on a $313 monthly budget?
The presented $313 monthly food budget prioritizes groceries rather than frequent restaurant meals. Suggested staples include beans, rice, peanut butter and jelly, Wonder Bread, top ramen, freezer meals, potatoes, and cheaper produce. The worker checks prices, searches for discounts, and rarely eats out because an average McDonald’s order of $7 to $8 would exhaust the budget too quickly.
Q: Why does the $25,000 earner not receive food assistance?
The scenario states that food assistance requires savings below $2,000 and annual income below $19,578. The modeled worker satisfies the savings requirement but earns $25,000, placing the worker above the stated income limit. Consequently, the worker does not qualify even though housing, transportation, food, healthcare, communication, and laundry expenses already exceed or nearly consume available income.
Q: What lifestyle does a $40,000 salary support?
A $40,000 salary gives the modeled single earner just over $3,000 monthly before taxes and just under $2,700 afterward. The budget supports a one-bedroom house, a used 2011 Subaru Forester, about $467 for food, employer-subsidized healthcare, a $10 gym membership, and limited entertainment. However, spending on ordinary needs and leisure can still reduce the monthly balance to approximately zero.
Q: How does life improve from $25,000 to $40,000 a year?
Moving from $25,000 to $40,000 makes several choices more practical in the modeled budgets. The $40,000 earner can live alone, shop at a nearby Kroger, buy better meat or fresh produce, occasionally choose organic food, eat out once or twice, receive employer-subsidized health coverage, join a low-cost gym, and purchase entertainment. The improvement is meaningful, but emergency security remains limited.
Q: Why can full-time workers still fall into debt?
A full-time worker can fall into debt when basic expenses consume more than after-tax income and no emergency savings remain. In the $25,000 scenario, housing, transportation, food, healthcare, laundry, internet, and phone costs leave an unsustainable budget. A car repair or health emergency can then require credit cards or high-interest short-term loans, while extra gig work or a second job becomes necessary.
Summary & Key Takeaways
-
The comparison models how annual income affects daily life across several earnings tiers, beginning at $25,000 and rising through $40,000, $100,000, $1 million, and $25 million. It uses imagined workers, taxes, Bureau of Labor Statistics spending data, local housing, transportation needs, food costs, and healthcare expenses to construct representative budgets.
-
At $25,000, a single Atlanta security guard receives about $1,764 monthly after taxes. Housing, transportation, food, healthcare, laundry, internet, and phone costs consume or exceed that amount. The worker cannot qualify for the food assistance described, has no emergency savings, and may need debt, family support, gig work, or another job.
-
At $40,000, a single event coordinator receives just under $2,700 monthly after federal and state taxes. The worker can rent a one-bedroom house, own an older car, buy better groceries, receive employer-subsidized healthcare, and afford limited entertainment. However, the remaining monthly margin is small, and an emergency could still create debt.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from Johnny Harris 📚

Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator