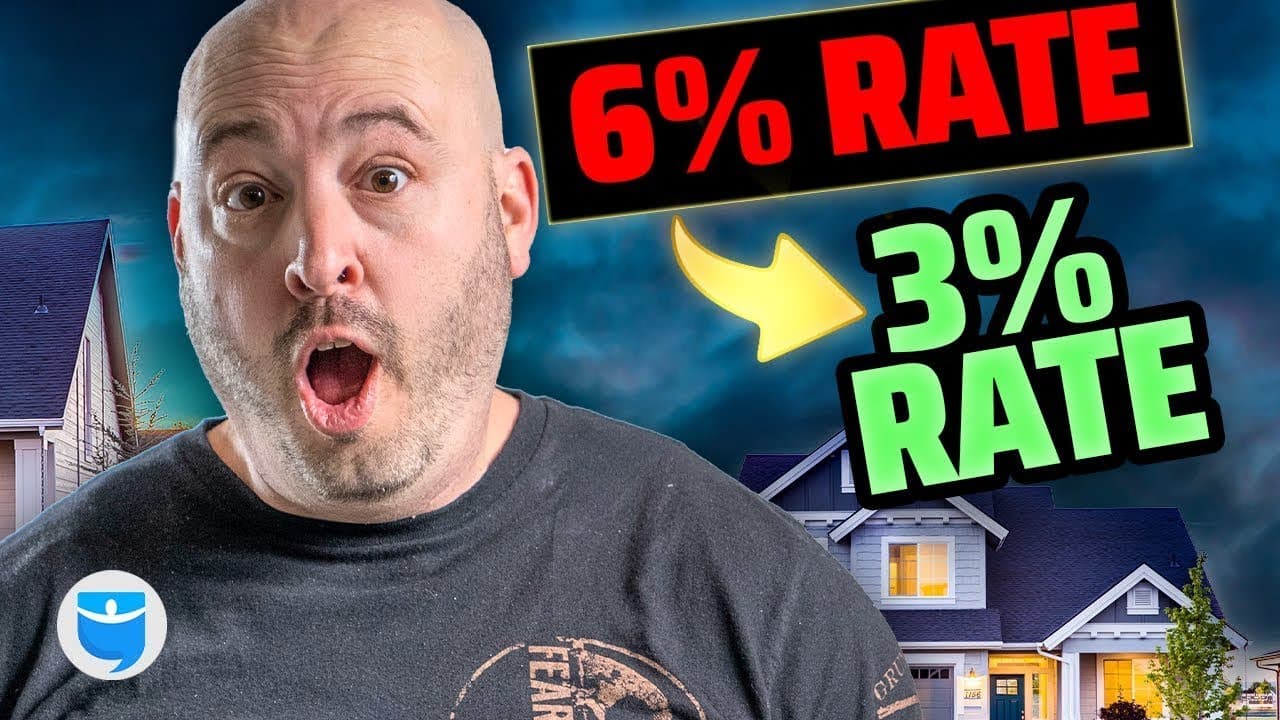
How Can You Get a 3% Mortgage Rate with Seller Credits?
TL;DR
You can temporarily lower your mortgage rate to 3% through a buydown program that utilizes seller credits. This allows you to save significantly on interest payments for the first three years without additional costs. However, this option is only available for conforming loans that meet government standards.
Transcript
we've gotten a lot of questions I know we've done previous episodes but just trying to clear up the misconception that may have arrived in last week's video we talked about how you can get three percent mortgage rates in today's market and today's video is clarification of what that means what that does not mean and a little bit of insight into wha... Read More
Key Insights
- The 3-2-1 buydown program allows buyers to temporarily reduce their mortgage interest rates using seller credits, providing significant savings in the first three years.
- This program is not an adjustable rate mortgage; the seller pre-pays the interest rate reduction, which can be refunded if refinancing occurs within the buydown period.
- Buydowns are only applicable to conforming loans, which adhere to government standards and include FHA, VA, and USDA loans.
- Non-conforming loans, like DSCR loans, cannot use buydown products due to differing underwriting standards and risk assessments.
- Conforming loans offer the lowest interest rates due to strict government underwriting, while non-conforming loans offer more flexibility but come with higher rates.
- The mortgage industry offers a spectrum of loan products, from conforming loans to hard money loans, each with varying levels of risk and interest rates.
- It's crucial for borrowers to work with a knowledgeable broker who has access to multiple loan products to find the best fit for their financial situation.
- BiggerPockets provides a wealth of resources, including forums and calculators, to help investors make informed decisions about their real estate financing options.
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: What is the 3-2-1 buydown program?
The 3-2-1 buydown program allows homebuyers to temporarily reduce their mortgage interest rates by using seller credits. This program provides a three percent reduction in the first year, two percent in the second year, and one percent in the third year, helping buyers save significantly on their monthly payments.
Q: Is the 3-2-1 buydown an adjustable rate mortgage?
No, the 3-2-1 buydown is not an adjustable rate mortgage. Instead, it involves the seller prepaying the interest rate reduction, which is held in escrow. If the borrower refinances within the buydown period, the unused portion can be refunded or applied to the new loan.
Q: Which loans are eligible for the 3-2-1 buydown program?
The 3-2-1 buydown program is eligible for conforming loans, which adhere to government standards. These include FHA, VA, and USDA loans. Non-conforming loans, such as DSCR or hard money loans, are not eligible due to differing underwriting requirements.
Q: What is the difference between conforming and non-conforming loans?
Conforming loans meet government guidelines and offer lower interest rates due to their strict underwriting standards. Non-conforming loans, like DSCR loans, offer more flexibility but come with higher interest rates due to increased risk. They do not conform to government standards and are not insured by the government.
Q: How can borrowers benefit from working with a broker?
Borrowers benefit from working with a broker who has access to multiple loan products, as they can help find the best fit for the borrower's financial situation. Brokers can provide expert advice and navigate the complexities of different loan options, ensuring borrowers make informed decisions.
Q: What resources does BiggerPockets offer for real estate investors?
BiggerPockets offers a variety of resources for real estate investors, including forums for discussions, calculators for running deal numbers, and articles on various financing options. These resources help investors make informed decisions and connect with professionals in the industry.
Q: Can the 3-2-1 buydown be combined with other loan products?
No, the 3-2-1 buydown cannot be combined with other loan products such as DSCR loans, HELOCs, or hard money loans. It is specifically designed for conforming loans that meet government standards and cannot be packaged with non-conforming loan products.
Q: What should borrowers consider when choosing a loan product?
When choosing a loan product, borrowers should consider their financial situation, risk tolerance, and long-term investment goals. It's important to work with a knowledgeable broker who can offer a variety of loan products and provide guidance on the best options for the borrower's specific needs.
Summary & Key Takeaways
-
The 3-2-1 buydown program enables buyers to reduce their mortgage interest rates temporarily by using seller credits. This program helps buyers save significantly in the first three years without the need for additional cash outlay.
-
Conforming loans, which meet government guidelines, are eligible for the buydown program. These loans offer lower interest rates due to their strict underwriting standards, as opposed to non-conforming loans, which carry higher rates.
-
Borrowers should consult with knowledgeable brokers who have access to a wide range of loan products to ensure they choose the best option for their financial needs. BiggerPockets offers resources to assist in making informed real estate financing decisions.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from BiggerPockets 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator