How Big Can the AI Infrastructure Market Become?
TL;DR
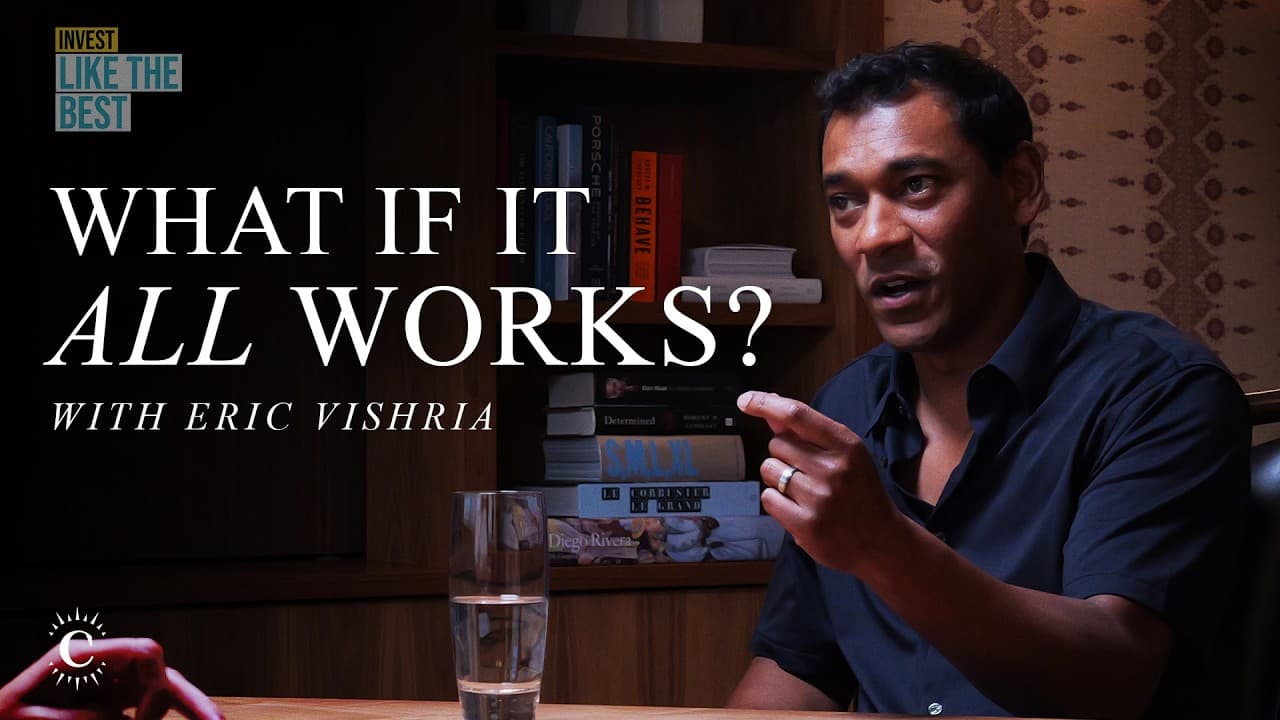
The AI market could support an oligopoly of major platforms plus several smaller companies worth hundreds of billions because demand is expanding too quickly for one provider to serve it all. Enterprise interest is already stronger than it was during early cloud adoption, while specialized model-serving expertise, infrastructure requirements, and energy constraints create room for differentiated businesses.
Transcript
I I'm very dismissive of this idea that like people are going to vibe code their own [ __ ] like and whatever like it that that isn't the issue. The issue with SAS companies is every single day that you are hitting your plan, you are destroying equity value. Like think about that. Our whole careers we learned you lay out a plan, you execute against... Read More
Key Insights
- AI infrastructure is difficult to operate efficiently because enormous models require specialized expertise beyond access to standard hardware and open-source software. Fireworks reportedly achieves about five times the speed performance of cloud providers on comparable models, along with a multiple-times throughput advantage that improves its underlying economics.
- The cloud market is evidence that apparent commodities can sustain durable differentiation. In 2007, investors could easily dismiss AWS as a low-margin utility, yet the later emergence of Azure, GCP, Cloudflare, and specialized infrastructure companies showed that scale did not eliminate every independent opportunity.
- The AI market is likely too large for one company to consume entirely. Eric Vishria expects an oligopoly of major winners alongside smaller companies that could still reach valuations of hundreds of billions, although relative performance and company selection will continue to matter.
- Enterprise demand for AI is stronger at this stage than enterprise demand was during early cloud adoption. Large companies may not yet use AI as deeply as AI-native businesses, but they are actively experimenting, allocating spending, discussing applications, and searching for workable adoption paths.
- The competitive frontier for SaaS has shifted because executing an established plan can now destroy equity value if that plan ignores AI-driven changes. Operating discipline remains important, but companies must reconsider whether their goals, products, and assumptions still fit the changing software market.
- AI scaling depends on physical and technical infrastructure, including energy, power, chips, memory, and algorithms. Rapid demand growth therefore creates opportunities across the stack while also making energy a potential bottleneck to producing and deploying more intelligence.
- The cloud analogy is useful because earlier predictions underestimated both total demand and the number of viable winners. AWS did not eliminate Azure, GCP, Snowflake, Confluent, Elastic, Databricks, Datadog, or Cloudflare, even though it competed across infrastructure and application categories.
- AI investing requires understanding the technology's jagged edge, meaning the uneven boundary between tasks that feel magical and tasks where systems remain unreliable or difficult to deploy. Products such as Sierra and infrastructure providers such as Fireworks reveal different parts of that frontier through their customers and operations.
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: Why could the AI market support many large winners?
The AI market could support many large winners because demand is growing faster than any single company can build and deliver the required capacity. Scaling requires energy, power, chips, memory, algorithms, and operational expertise. Cloud computing followed a comparable pattern, producing three major providers plus valuable specialists, even after investors predicted that AWS would absorb nearly everything.
Q: What does cloud computing teach investors about AI?
Cloud computing shows that investors can underestimate both the eventual market size and the number of durable competitors. AWS became the largest provider, but Azure and GCP also developed into major businesses. Independent companies including Snowflake, Confluent, Elastic, Databricks, Datadog, and Cloudflare created substantial value by specializing rather than surrendering the entire market to one platform.
Q: Why is efficient AI model inference difficult?
Efficient inference is difficult because running models with two trillion, three trillion, or four trillion parameters requires specialized operational knowledge. Fireworks reportedly delivers roughly five times the speed performance of cloud providers using the same open-source models and Nvidia hardware, plus a multiple-times throughput advantage. That gap suggests model serving is not merely commodity resale or simple pass-through infrastructure.
Q: How does enterprise AI adoption compare with early cloud adoption?
Enterprise AI adoption begins with considerably more interest than early cloud adoption did. Several years after AWS launched S3 and EC2 in 2006, traditional enterprises remained highly skeptical of cloud computing. By contrast, large companies now want AI, fund experiments, discuss its uses, and attempt deployments, even though their actual adoption remains less advanced than at AI-native companies.
Q: Why can following an old SaaS plan destroy value?
Following an old SaaS plan can destroy value when the competitive environment has changed faster than the company's objectives. Software leaders were traditionally rewarded for setting a plan and executing it relentlessly. AI alters product capabilities and customer expectations, so repeatedly hitting targets based on outdated assumptions can weaken a company's future position and reduce its equity value.
Q: Will one AI company dominate the entire market?
A single AI company is unlikely to consume the entire opportunity according to the argument presented. Similar claims were made about AWS, yet cloud ultimately supported AWS, Azure, GCP, Cloudflare, and numerous specialized software and infrastructure companies. The expected AI structure is an oligopoly of major platforms accompanied by smaller winners that can still become exceptionally valuable businesses.
Q: What infrastructure constraints could limit AI growth?
AI growth depends on more than model algorithms. Providers must build substantial infrastructure involving energy, power, chips, and memory while also improving the software used to operate models. Energy is identified as a potential bottleneck to intelligence, and the unusually fast adoption curve increases the difficulty of expanding capacity quickly enough to satisfy demand across companies and enterprises.
Q: What should investors examine in an AI company?
Investors should examine where a company sits on AI's jagged edge, how its product converts new technical capability into customer value, and whether its advantages remain meaningful against major platforms. Fireworks highlights model-serving efficiency, while Sierra illustrates AI products for enterprises. Investors must still distinguish relative winners because a large market does not prevent roadkill or guarantee success.
Summary & Key Takeaways
-
Cloud history suggests that rapidly expanding technology markets can support several enormous providers and valuable specialists. Predictions that AWS would consume enterprise infrastructure and applications proved too narrow, as Azure, GCP, Snowflake, Databricks, Confluent, Elastic, Datadog, and Cloudflare demonstrated that meaningful differentiation and scale could exist across multiple layers.
-
AI adoption differs from early cloud adoption because established enterprises already want the technology. They are funding experiments, discussing applications, and trying to understand deployment barriers. Their implementation still trails AI-native companies, but they view AI as both a larger opportunity and a greater competitive threat than cloud initially appeared to be.
-
AI changes the competitive frontier for software companies because faithfully executing an outdated operating plan can reduce equity value. Investors must understand each technology's jagged edge, including where it performs exceptionally and where it fails. Model efficiency, energy availability, specialized chips, enterprise products, and robotics may each produce substantial investment opportunities.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from Invest Like The Best 📚


Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator