How Does the Debt Settlement Industry Trick People?
TL;DR
Debt settlement companies advertise loans, then bait-and-switch callers into stopping payments on their credit cards, charging up to 25% of the settled debt as a fee. Ads use fake photoshopped government headlines and AI-generated testimonial variations microtargeted at veterans, seniors, Christians, and factory workers. The biggest undisclosed risk is being sued: debt collection fills nearly 50% of the US civil case docket.
Transcript
There's a 10 billion dollar industry which praise on poor people is endorsed by celebrities but most people haven't heard of mostly because it goes by so many names. >> I like something called the debt backpack method. >> I recommend national debt relief to anyone who wants to become debtree. It's called [music] the rapid relief method. >> It's cal... Read More
Key Insights
- Debt settlement in its basic form is not a scam: it is an agreement between a debtor and a creditor to close a debt for a lower total amount, and it is sometimes the best move for both parties when the debt is already in default and the creditor would otherwise not get paid.
- The industry being criticized is the one that sells people on not paying their bills as a shortcut out of debt and takes a large fee for it, frequently without disclosing the risks and often tricking people into enrolling in the first place.
- The advertising rotates through invented brand names such as the debt backpack method, the rapid relief method, and the debt clear method, which is a large reason most people have never heard of the industry despite its $10 billion size.
- A recurring ad script claims banks hate this program because qualifying Americans with $10,000 or more in credit card or personal loan debt can settle 40 to 60% of the balance and roll the rest into one payment plan.
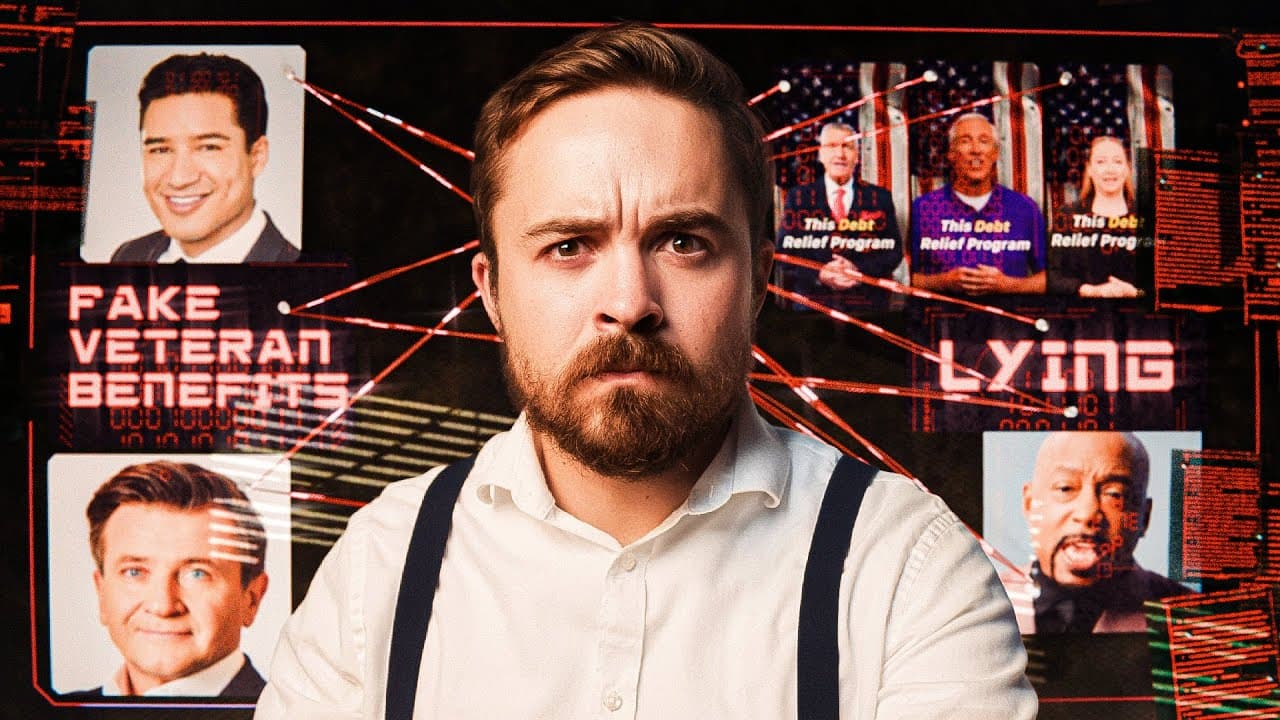
- Some ads used a photoshopped Department of Defense headline claiming the Veterans Administration was handing out debt elimination for all veterans. The real headline says nothing of the kind, and the same fabricated claim was recycled to target seniors on Social Security.
- Dozens of AI-generated variations of the same fake personal debt story, swapping the presenter's gender and race, are run simultaneously so the advertiser can optimize click-through rate. Coffeezilla argues this scale of targeted fakery could not have existed 10 years ago.
- According to sales rep Miller, more than 70% of his clients were not in genuine hardship: they had called about a consolidation loan, home repair loan, or other loan, because loans are what the third-party affiliates advertise, not debt settlement.
- A company script includes a loan killer method for callers who insist on a loan, instructing the rep to say a partner broker ran the name and it came back declined by all lenders, then to pivot into qualifying the caller for a debt resolution option.
- Attorney Clifford describes a pattern where a supposed debt consolidation company pulls the caller's credit, declares them unqualified, and passes the credit report to an affiliated debt settlement company, sometimes the same company, so the consumer never sees the relationship.
- Debt collection accounts for almost half of the entire US civil case docket according to Pew, and in many states it is the single most commonly filed type of lawsuit, which makes being sued after defaulting a routine outcome rather than an edge case.
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: What is the debt settlement bait and switch?
Third-party affiliates advertise loans such as consolidation loans or home repair loans, because loan offers generate calls. Once a caller is warm transferred to the sales division, the rep tells them they do not qualify for a loan and pitches a debt settlement program instead. Sales rep Miller said more than 70% of his clients had called wanting a loan, not debt settlement, and that reps sometimes rushed people into signing contracts while the caller still believed they were getting a loan. Two other sales reps who stayed anonymous described the same practice.
Q: How much do debt settlement companies charge in fees?
Companies charge up to 25% of the debt they settle as their fee, which leaves few if any savings for the consumer. Using a $10,000 credit card debt as an example: if the creditor settles for 50%, that is $5,000 to the creditor plus $2,500 to the negotiator, so $7,500 total against the original balance. That looks like a 25% saving at first glance, but the calculation ignores that the balance kept growing while the account was in default, which erodes the apparent benefit further.
Q: Why is getting sued the biggest risk of a debt settlement plan?
Debt settlement requires you to stop paying your creditors, and creditors have no obligation to negotiate once you do. Sometimes they settle, but sometimes they sue. Attorney Clifford said lawsuits happen quite a bit and are one of the most popular kinds of lawsuits filed. According to Pew, debt collection takes up almost 50% of the entire civil case docket, and in many states it is the number one type of lawsuit filed. Those numbers have only increased in recent years, yet many companies do not disclose this risk.
Q: What is the loan killer method in debt settlement sales scripts?
The loan killer method is a scripted response obtained from one of these companies, used when a client is frustrated and insists they only want a loan or will not give up on the idea of a loan. The script instructs the rep to say it will be very difficult to get a good interest loan and that a partner broker ran the client's name and it came back declined by all lenders. The rep then pivots with a line about why the client has been qualified for a debt resolution option, converting a loan inquiry into a debt settlement sale.
Q: Are the debt relief ads featuring veterans and seniors real?
No. A cluster of ads claimed the Veterans Administration was handing out debt elimination for all veterans and that no one was talking about it. The headline shown was a fake, photoshopped version of a real Department of Defense headline that says nothing of the sort. The same fabricated framing was reused for seniors on Social Security, claiming the government was practically handing out debt elimination. These fake government headlines were used to push veterans and seniors toward debt settlement programs.
Q: Why do debt relief ads go by so many different names?
The industry runs under a rotating set of invented brand names, including the debt backpack method, the rapid relief method, and the debt clear method, each promoted by celebrities as an easy secret way to settle debt. Because the naming keeps shifting and most of the business runs in the dark through paid ads, a $10 billion industry stays largely unknown to the public. Most videos that do explain debt settlement are themselves trying to sell debt settlement, so independent explanation is scarce.
Q: Is debt settlement always a scam?
No. At its most basic, debt settlement is a process where a debtor who owes money and the creditor they owe agree to close the debt for a lower total amount. That is objectively not a scam and is sometimes the best move for both parties, usually when the debt is already in default, the creditor is unlikely to get paid otherwise, and the debtor cannot pay. The criticism targets the industry that sells not paying your bills as a shortcut, takes a large fee, hides the risks, and tricks people into enrolling.
Q: How do fake testimonial ads get optimized for engagement?
A single fabricated story, such as a person claiming they racked up four credit cards to more than $30,000 before getting the debt cancelled, is produced in dozens of AI-generated variations. The variations swap the presenter, for example a woman or a man, a Black or a white presenter, so the advertiser can measure which version produces the highest click-through rate. Thousands of ads run this way, microtargeted at seniors, Christians, factory workers, veterans, and anyone with more than $10,000 in credit card debt.
Summary & Key Takeaways
-
A $10 billion industry markets debt relief under many rotating names, including the debt backpack method, the rapid relief method, and the debt clear method. Celebrity-endorsed ads claim banks hate the program and that anyone with $10,000 or more in credit card or personal loan debt can settle 40 to 60% of what they owe.
-
Thousands of ad variations microtarget vulnerable groups: seniors, Christians, factory workers, veterans, and anyone carrying over $10,000 in credit card debt. Some use a photoshopped Department of Defense headline claiming the Veterans Administration is handing out debt elimination, and the same fabricated framing is reused for seniors on Social Security.
-
Sales reps, including one named Miller plus two anonymous sources, describe a bait and switch: affiliates advertise loans, callers are warm transferred to a sales division, and a scripted loan killer method tells reps to claim the caller was declined for a loan before pitching debt resolution instead.
-
Lawsuits are the main hidden risk. Once you stop paying, creditors have no obligation to negotiate and often sue instead. Fees of up to 25% of the settled debt consume most of the apparent savings, and the balance keeps growing during default, so some people end up paying more than if they had simply paid their creditors.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from Coffeezilla 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator