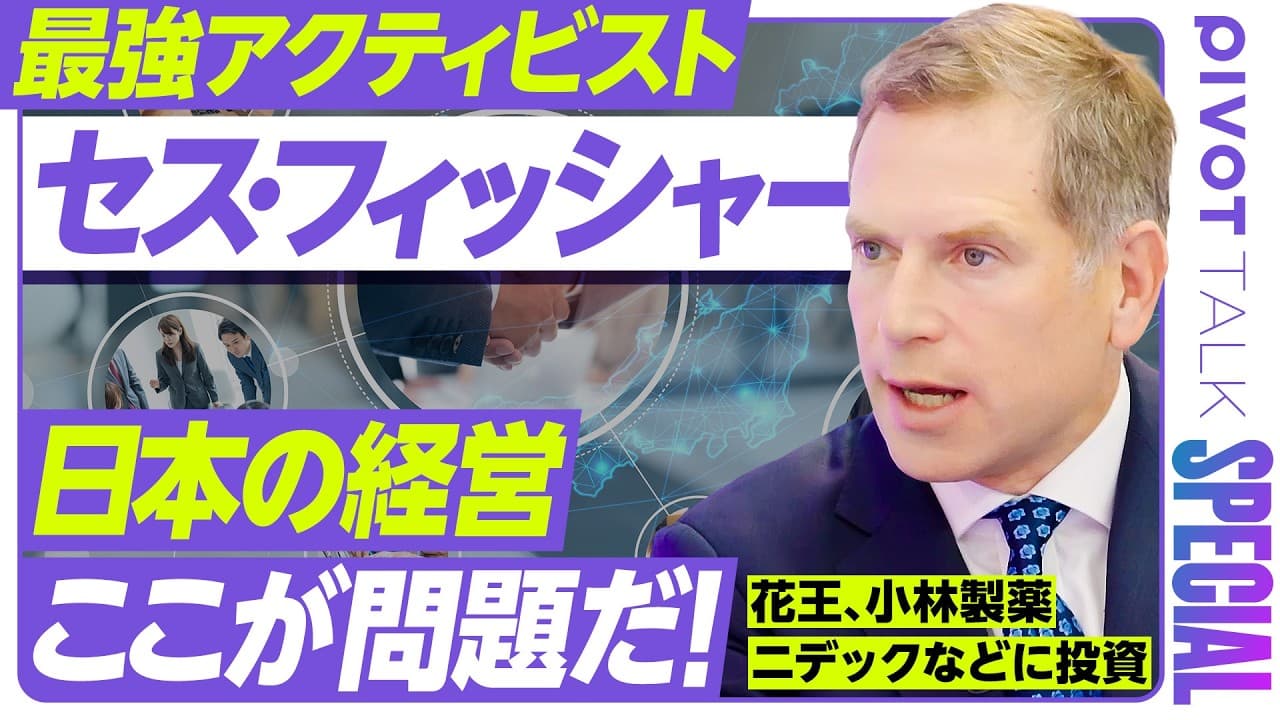
How Can Japanese Corporate Governance Improve?
TL;DR
Japanese corporate governance has improved from nearly zero to about four out of ten, but boards still need greater independence, stronger oversight, and directors willing to challenge management. Companies should redirect excessive internal reserves toward growth, research and development, employee wages, and calculated risk-taking, while treating high-quality activist investors as aligned advisers who can contribute external knowledge and pressure for reform.
Transcript
How U rate the current Japanese corporate governance and I think Japan started at zero and is maybe about a four. What's the reason behind it? Look, Japan started with no outside directors. Japan started with only accountability to Sacho and nobody else knew. They didn't understand fairness and M&A. What actually large Japanese company has done is ... Read More
Key Insights
- Japanese corporate governance is rated at about four out of ten by Seth Fischer, while Kozo Takaoka rates it five if the United States represents ten. Fischer instead places the United States itself between seven and eight, emphasizing that no market has perfect governance.
- Japan has made dramatic governance progress since 2013 because companies now recognize outside directors, accountability, whistleblowing, fair treatment in mergers and acquisitions, and proper boardroom debate. These concepts were previously unfamiliar to many companies, although implementation still remains incomplete.
- A board's central responsibility is to hold management accountable, including evaluating the chief executive and replacing that person when performance is inadequate. Governance fails when directors primarily help current executives preserve their positions instead of independently testing strategy, leadership, and results.
- Strong board oversight requires more than appointing nominally independent directors. Effective directors need relevant industry authority, courage, and a willingness to ask questions or reject management proposals, while nomination and compensation committees should report independently rather than remain controlled by the company president.
- United States board practices provide a benchmark through full-day meetings, monthly financing reports from the chief financial officer, independent committee reports, private discussions about the chief executive, presentations from mid-level employees, external assessments of business lines, and active participation from every director.
- Japan's internal reserves exceed 600 trillion yen, an amount described as nearly equal to the country's gross domestic product. The discussion proposes a 2 percent tax that could produce 12 trillion yen annually, while criticizing companies for retaining cash instead of funding future growth.
- Excessive corporate caution followed an earlier period of excessive debt. Companies kept reducing debt and accumulating cash without recognizing when to stop, producing too little risk-taking and inadequate investment in research and development, business expansion, employee wages, and other sources of growth.
- High-quality activist investors can function as aligned advisers because their success depends on the company's success. They can share knowledge about overseas practices, artificial intelligence, marketing, and alternative business models while pressuring managers to use strong assets and capable employees more effectively.
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: How strong is Japanese corporate governance today?
Seth Fischer rates Japanese corporate governance at about four out of ten, starting from essentially zero, while Kozo Takaoka gives it five when treating the United States as ten. Fischer says the United States is actually only around seven or eight. Japan has improved substantially, but board independence, executive accountability, and the quality of boardroom discussion still require considerable work.
Q: Why has Japanese corporate governance historically been weak?
Japanese companies historically had few outside directors and treated accountability to the company president as more important than accountability to shareholders or other stakeholders. Many businesses were unfamiliar with whistleblowing, fairness in mergers and acquisitions, and rigorous board debate. Main banks were traditionally major shareholders, and shareholder meetings often functioned as short ceremonies rather than effective mechanisms for oversight.
Q: What should an effective corporate board do?
An effective board should hold management accountable, evaluate the chief executive, and replace that leader when performance is insufficient. It should receive detailed financial reporting, examine individual business lines, hear independent committee findings, and seek external perspectives. Every director should participate actively, ask difficult questions, and discuss the chief executive without that executive present when an independent assessment is required.
Q: Why are independent directors important in Japan?
Independent directors can challenge executives, bring outside expertise, and prevent boards from serving mainly to preserve management positions. Their value depends on more than formal independence, however. They need relevant industry authority, courage, and a willingness to say no or demand better answers. The discussion also favors nomination committee structures that require more than half of board members to be independent.
Q: What is wrong with Japanese companies accumulating internal reserves?
Large Japanese companies accumulated more than 600 trillion yen in internal reserves after spending years reducing excessive debt. The problem is that saving continued even after balance sheets became safer, leaving too much cash and too little risk-taking. The speakers argue that companies should instead invest more in future growth, research and development, employees, technology, marketing, and calculated business expansion.
Q: How could better capital allocation support economic growth?
Better capital allocation would direct retained cash toward research and development, business investment, employee wages, and measured risk-taking. Those investments can expand companies, improve their ability to pay workers, and increase taxes paid through stronger performance. One proposal discussed is a 2 percent tax on more than 600 trillion yen in internal reserves, estimated to raise 12 trillion yen annually.
Q: How can activist investors help Japanese companies?
High-quality activist investors can act like advisers whose financial success is aligned with the company's success. They can study a business, introduce knowledge from the United States and Europe, and highlight opportunities involving artificial intelligence, marketing methods, technology strategies, or alternative business models. Their engagement can also pressure conservative managers to invest, take appropriate risks, and use valuable assets more productively.
Q: What distinguishes a good activist investor from a bad one?
A good activist investor focuses on the company's success and contributes research, relevant external knowledge, and practical ideas for growth. Such an investor can be treated as an advisory consultant because both sides benefit when the business improves. The discussion acknowledges that activists vary in quality, so management should engage high-quality investors rather than assume that every activist provides equally useful guidance.
Summary & Key Takeaways
-
Japanese corporate governance has changed dramatically since 2013, when many companies lacked outside directors and familiarity with accountability, whistleblowing, fair mergers and acquisitions, and rigorous boardroom discussion. Seth Fischer rates Japan at about four out of ten, compared with roughly seven or eight for the United States, while Kozo Takaoka gives Japan five.
-
Effective boards must hold chief executives accountable through independent nomination and compensation processes, detailed financial reviews, external perspectives, and candid questioning. Japanese boards still often protect incumbent executives instead. The discussion supports more independent directors, especially people with industry authority and enough courage to oppose management or ask difficult questions when necessary.
-
Large Japanese companies accumulated more than 600 trillion yen in internal reserves after reducing excessive debt, but continued saving instead of investing adequately in growth. The guests argue that businesses should fund research and development, employees, technology, marketing, and calculated expansion. High-quality activist investors can provide useful outside knowledge while applying pressure for better capital allocation.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from PIVOT 公式チャンネル 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator