How to Grow Wealth with Low-Cost Index Funds
TL;DR
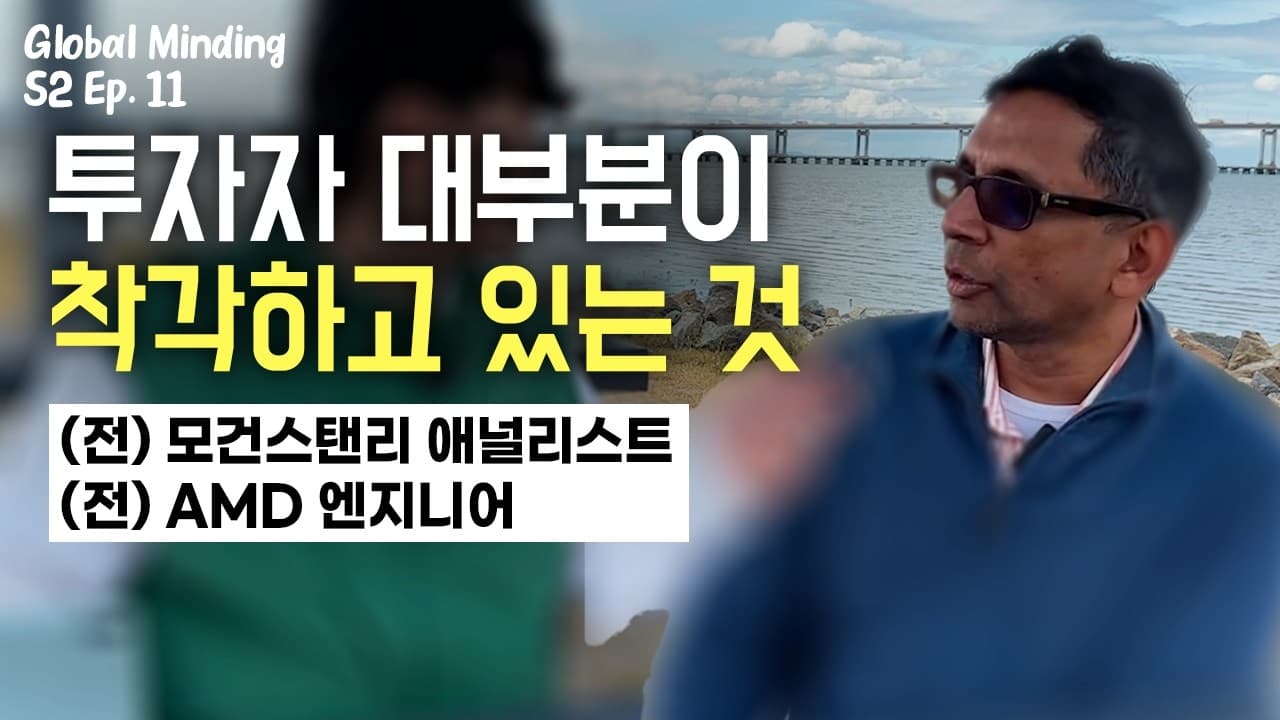
Invest regularly in diversified index funds and give compounding several decades to work. Broad market exposure can provide market-level returns, described as roughly 8% to 10% on average over long periods, while reducing dependence on individual stocks. Avoid reacting to daily fluctuations, approach leverage cautiously, and risk only money you can afford to lose.
Transcript
The human psychology is when you make the money you think it's because of you right even though the market because the illusion everybody faces but when you lose the money then you kind of say oh the market is bad and all that right I have seen some of these investors from very close range and these are so sophisticated investors when you look at a... Read More
Key Insights
- Diversification is the practice of spreading money across multiple stocks instead of concentrating everything in one company. Index funds provide this diversification automatically, making them the interviewee's preferred starting point for younger investors who want broad participation in market returns.
- Long-term market returns are described as averaging roughly 8% to 10% over the past 20 years. Achieving that result while sleeping well at night is presented as a strong outcome, especially because relatively few professional investors consistently outperform the market across extended periods.
- Daily market fluctuations are largely irrelevant to a genuinely long-term investment plan. Investors are advised to remain invested instead of reacting continually to short-term price movements, since compounding requires both market exposure and enough time for gains to build upon previous gains.
- Outperforming the market requires accepting additional risk. Analysts and portfolio managers may beat the market during some periods and fail during others, while matching broad market performance over a long horizon can itself be considered a successful and financially meaningful result.
- Popular stocks can attract investors only after much of their exceptional performance has already occurred. By the time late investors enter, the excitement or fad may be ending, so recent gains alone do not establish that a company will remain an attractive investment.
- Durable trends work by changing user behavior over time. E-commerce through Amazon, mobile television viewing through Netflix, and music streaming through Spotify illustrate shifts that can create long-term opportunities, although identifying a trend does not reveal exactly when its financial payoff will occur.
- Leveraged products and options introduce timing risk because a valid long-term trend may take two years rather than begin tomorrow. Investors who still enter such positions should be cautious, use money they can afford to lose, and decide their profit target or exit plan beforehand.
- Compounding becomes especially powerful when investing begins in a person's early twenties. Starting work and investing at age 23 or 24 can provide about four decades before age 65, giving diversified market exposure considerably more time to accumulate and build on prior returns.
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: How can a young investor begin building wealth with limited capital?
A young investor can begin by consistently buying diversified index funds and remaining invested for the long term. An index spreads exposure across many companies, avoiding dependence on a single stock. Beginning at age 23 or 24 can provide about four decades before age 65 for returns to compound. Daily price changes should not determine decisions made for such a long horizon.
Q: Why are index funds recommended instead of individual stocks?
Index funds are recommended because they provide diversification automatically and allow investors to earn returns comparable to the overall market. Selecting one stock creates greater company-specific risk, while retail investors must compete against professionals who may know far more about that company. The interviewee also emphasizes low fees, broad exposure, and the ability to remain invested without constantly monitoring daily fluctuations.
Q: What long-term return does the interview associate with the market?
The interview describes average market returns of roughly 8% to 10% over a period such as the past 20 years. That figure is presented as a phenomenal long-term outcome rather than a guaranteed annual result. The main argument is that earning market-level returns consistently, while accepting less concentration risk and sleeping well at night, can be preferable to repeatedly chasing outperformance.
Q: Why is consistently beating the market so difficult?
Consistently beating the market is difficult because outperformance requires additional risk, and even sophisticated analysts and portfolio managers alternate between successful and unsuccessful periods. Only a small number maintain superior records over long spans. Retail investors face an additional disadvantage because professional investors often possess much deeper knowledge about individual companies, making direct stock-picking competition particularly demanding.
Q: How should investors evaluate leveraged products and options?
Leveraged products and options should be approached cautiously because they add a timing requirement to the investment decision. An investor may correctly identify a trend but still lose if it develops two years later rather than tomorrow. Any speculative position should use money the investor is willing to lose and should have a predetermined exit plan, such as leaving after a 10% or 20% gain.
Q: How can long-term consumer trends guide stock selection?
Long-term trends can guide stock selection when they produce durable changes in user behavior. The interview cites growing e-commerce activity through Amazon, television consumption on phones through Netflix, and music streaming through Spotify. Investors may try to follow a market leader or hold a basket of potential winners, but they must remain patient because a real trend's timing is uncertain.
Q: Why can buying popular stocks after large gains be risky?
Buying popular stocks after large gains can be risky because investors often arrive after most of the exceptional performance has occurred. The excitement may represent a temporary fad that is already ending. Even established leadership can change over time, as illustrated by Intel's strong semiconductor position 20 years earlier and its later difficulties, so picking one company and forgetting it is challenging.
Q: How does investor psychology contribute to poor decisions?
Investor psychology can create an illusion of personal skill when a trade makes money, even when broader market conditions deserve much of the credit. When a trade loses, the same investor may blame the market instead of examining the decision. This inconsistent attribution can encourage excessive confidence, greater risk-taking, and attempts to compete directly with sophisticated professional investors.
Summary & Key Takeaways
-
Diversified index funds offer a straightforward way to participate in the market without depending on one company. The interviewee considers the S&P 500 a comparatively safe choice because it already contains many stocks, charges low fees, and can deliver market-level performance while allowing investors to worry less about daily price movements.
-
Consistently beating the market requires risk, and even sophisticated analysts rarely maintain superior performance over long periods. Retail investors selecting individual stocks compete against professionals who often possess deeper company knowledge. Instead of trying to produce winning trades, investors can use broad indexes and allow other market participants to make costly mistakes.
-
Young investors possess a valuable advantage because they can leave money invested for decades. Someone beginning work at age 23 or 24 and continuing until 65 has about four decades for returns to compound. Speculative positions should reflect personal risk tolerance, use disposable money, and include a predetermined exit plan.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from 희야기 | HeeChan 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator