Should Investors Choose European or US Stocks?
TL;DR
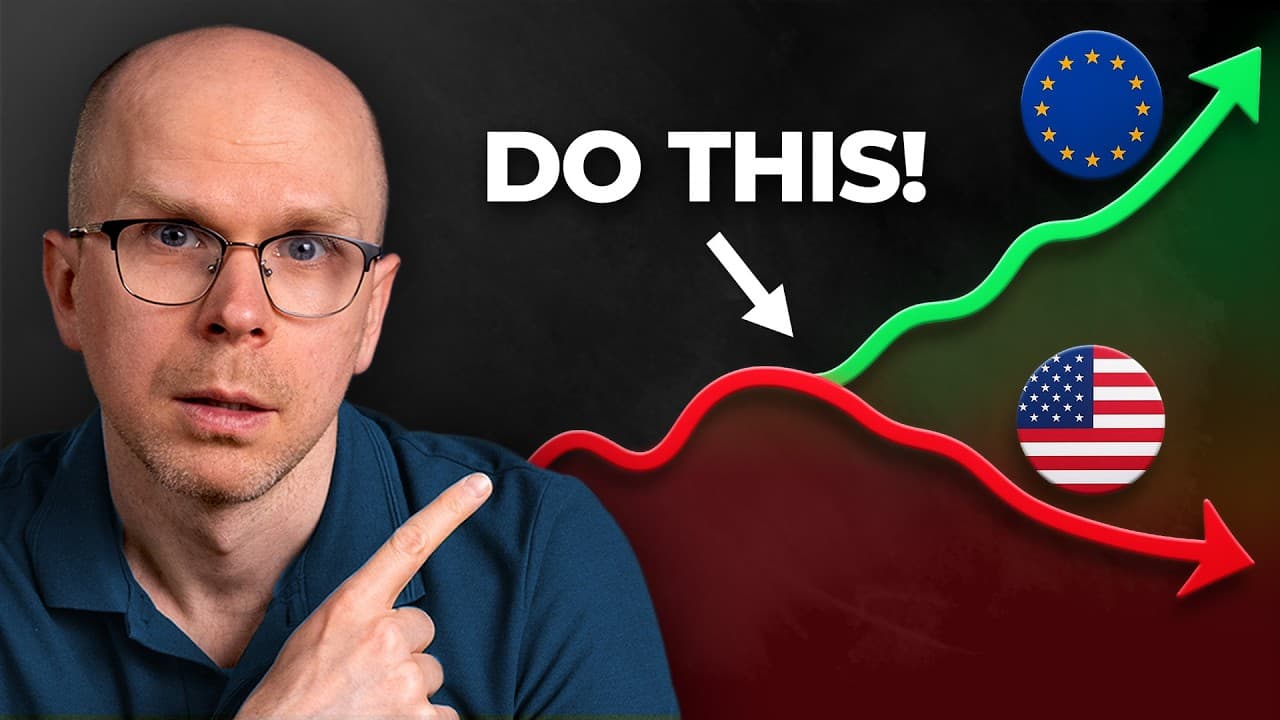
Global diversification is presented as more sensible than abandoning US stocks for Europe, because no one knows which region will lead future growth. European stocks offer lower valuations and potential advantages for eurozone investors, while American markets retain major technology companies, entrepreneurial strength, and a history of recovering from crises. Investors concerned about US concentration could allocate 30–40% to Europe while keeping the remainder globally diversified.
Transcript
Since Donald Trump became president, European stocks have been beating American stocks. Many European investors are asking, should we dump American stocks and invest in Europe instead? Even though I started my career on Wall Street in America, I've spent most of it here in Europe, including my time as CEO of a European investment company, which tod... Read More
Key Insights
- • US stocks represent over 60% of the global stock market even though the United States produces only 25% of world GDP. This mismatch, combined with Europeans frequently treating the S&P 500 as their default investment, creates substantial concentration in one national market.
- • Historical US stock performance was exceptionally strong across the 20th century, producing a 6.7% annual inflation-adjusted return compared with 5.2% for global stocks. Compounding turned $1 into over $700 in America, versus approximately $160 in non-US markets.
- • Recent US outperformance is concentrated in the period since 2010, because European stocks performed slightly better than American stocks between 1970 and 2010. During the following 15 years, American stock valuations also climbed to levels described as among their highest historically.
- • The price-to-earnings ratio measures how much investors pay for each unit of company profit by dividing a stock's price by its earnings per share. A $40 share earning $2 per share has a ratio of 20, and higher ratios indicate more expensive profits.
- • High price-to-earnings ratios are generally associated with lower subsequent investment returns, although they cannot reliably predict future profits. The cited Vanguard paper suggests these ratios explain about 40% of stock return differences over time, supporting the relative valuation case for Europe.
- • European stocks offer exposure to a large, wealthy, and diversified market containing numerous countries and industries. The speaker considers their prices reasonable and notes that investors can obtain broad European exposure through ETFs or index funds without selecting individual companies.
- • American stocks retain important strengths despite elevated valuations and political concerns. The United States has 340 million people, substantial natural resources, immigrant talent, an entrepreneurial culture, and many leading technology and artificial intelligence companies that could benefit from a transformative AI revolution.
- • Global diversification is the speaker's preferred response to uncertainty about which country or region will lead future growth. A global fund spreads investments according to stock-market size, while a 30–40% European allocation can add home bias and limit currency risk for eurozone investors.
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: Should European investors sell US stocks and buy European stocks?
European investors should not necessarily abandon American stocks and move everything into Europe. The speaker considers European equities a sensible investment because their valuations are lower and their market is broad and diversified. However, the United States retains strong entrepreneurial capacity, major natural resources, immigrant talent, and leading technology and artificial intelligence companies. A globally diversified portfolio, potentially with additional European exposure, avoids making an all-or-nothing regional bet.
Q: Why have US stocks historically attracted European investors?
European investors have favored US stocks for three main reasons presented in the discussion. American equities delivered strong historical inflation-adjusted returns, the country developed a reputation for supporting entrepreneurs and shareholders, and many of the world's largest corporations chose American exchanges for their listings. Because numerous S&P 500 companies earn half or more of their revenue abroad, US-listed stocks have also provided indirect exposure to the global economy.
Q: Why might European stocks outperform US stocks going forward?
European stocks could outperform because their valuations remain much lower than American valuations, while higher price-to-earnings ratios have generally been associated with lower future investment returns. Europe may also benefit from closer cooperation in response to the Ukraine war and the Trump presidency, large investments in European defense, and pressure to simplify regulation. These factors create potential upside, although neither valuations nor political reforms guarantee stronger returns.
Q: What does the price-to-earnings ratio show investors?
The price-to-earnings ratio shows how much an investor pays for each unit of a company's profit. It is calculated by dividing the stock price by earnings per share. For example, a $40 stock with $2 of earnings per share has a ratio of 20. A higher ratio indicates that equivalent profits cost more, while a lower ratio indicates a cheaper valuation, but the metric does not reliably predict future profits.
Q: What are the risks of investing only in European stocks?
Investing exclusively in Europe creates regional concentration and depends heavily on European economies, companies, and policymakers succeeding. The speaker is skeptical that Europe will quickly deregulate or become substantially more business-friendly, citing the difficulty of navigating European Union directives, regulations, and different national political factions. An Europe-only portfolio would also miss possible gains from American technology, artificial intelligence, entrepreneurial activity, and any other region that becomes a future growth leader.
Q: Why could US stocks remain attractive despite high valuations?
US stocks could remain attractive because America combines a large population of 340 million people, extensive natural resources, a strong money-making culture, immigrant talent, and many of the world's leading technology and artificial intelligence companies. The country has also recovered from difficult periods including the Great Depression, the stagflation of the 1970s, the dot-com bubble, and the Great Recession. These strengths could continue supporting corporate growth despite current vulnerabilities.
Q: How does a global stock ETF diversify a portfolio?
A global stock ETF or index fund distributes money across countries according to the market capitalization, or size, of each national stock market. The speaker uses global ETFs that include small, midsized, and large companies around the world for family investments. This approach provides broad participation in global economic growth, but it still places approximately 60–70% of the portfolio in American stocks because of the US market's global weight.
Q: When does a European home bias make sense?
A European home bias can make sense when an investor wants less dependence on American stocks, reduced currency risk, or greater exposure to assets closer to home. The strategy described allocates roughly 30–40% of the portfolio to European equities while keeping the remainder globally diversified. For eurozone investors, European holdings can limit currency exposure, and nearby investments may face less perceived risk of foreign holdings being confiscated in exceptional historical circumstances.
Summary & Key Takeaways
-
European stocks have recently outperformed American stocks, while US equities represent over 60% of the global market despite the country producing only 25% of world GDP. Historical US returns, confidence in American capitalism, and the international revenues of US-listed corporations have encouraged European investors to hold substantial American exposure.
-
The case for Europe rests on lower valuations, possible economic reforms, defense investment, and closer political cooperation. American price-to-earnings ratios have risen sharply since 2010, while European valuations have remained lower. However, the speaker warns that valuation metrics are imperfect and doubts Europe will quickly become substantially more business-friendly.
-
The preferred strategy is broad global diversification through stock ETFs or index funds covering companies of different sizes worldwide. Because market-capitalization-weighted global funds still allocate 60–70% to American stocks, concerned European investors could introduce a 30–40% European allocation to reduce currency exposure and establish a measured home bias.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from Tom Crosshill 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator