How Did VCU Assess QE2 and the 2010 Economy?
TL;DR
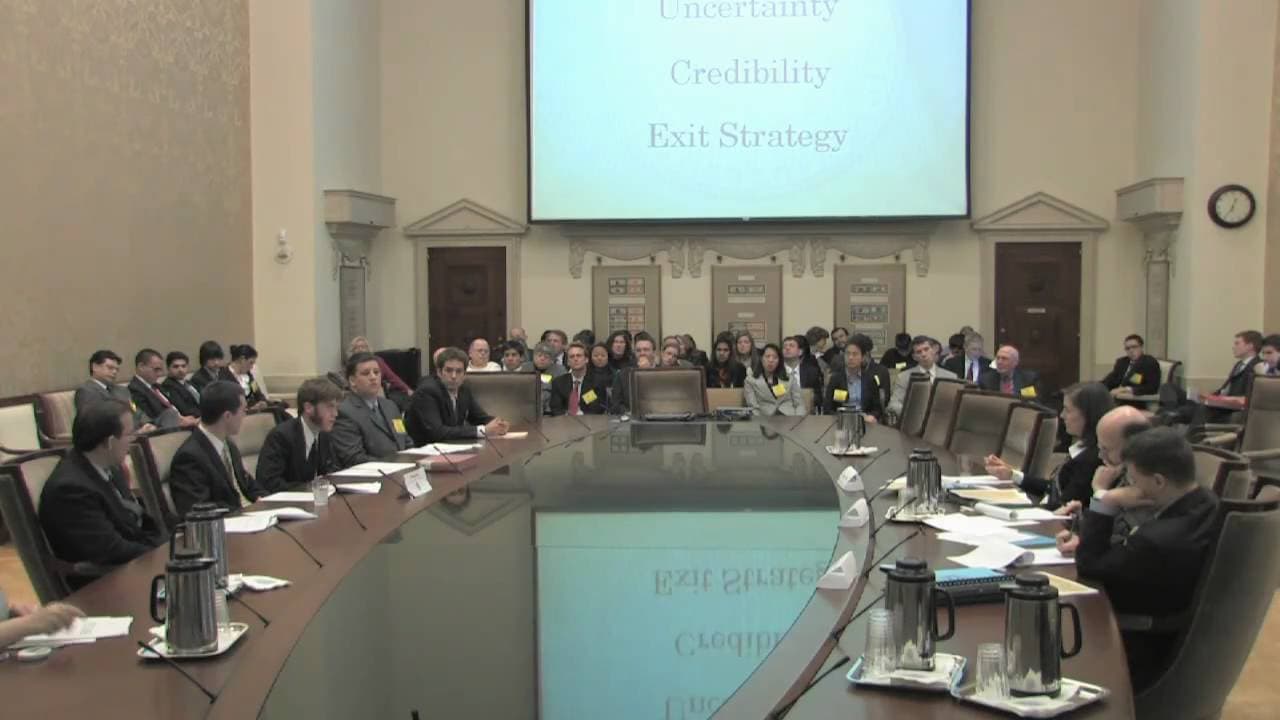
QE2 was presented as an important safeguard against rising deflation risk, but the team expected it to provide limited improvement amid slow growth and prolonged high unemployment. Their assessment pointed to weak final sales, low inflation, labor market slack, housing distress, structural employment mismatches, and uncertain government spending as major constraints on the recovery.
Transcript
[ Inaudible Remark ] Matthew Walper [phonetic]. Shawn Prietti [phonetic]. Andrew Stevenson. And my name is Logan Hodgins. Okay, and judges if you'd do the same. My name is Alex Olbrecht, I'm Associate Professor of Economics and Executive Director of the Eastern Economic Association. I was a High School Fed Challenge team member in high school of 19... Read More
Key Insights
- Real GDP growth was 2.5 percent in the third quarter, according to the BEA’s second estimate, placing growth at the lower bound of the team’s estimated potential-growth range of 2.5 to 2.8 percent.
- Inventory adjustment was responsible for more than half of the change in real GDP during the preceding five quarters. Because inventories cannot support growth indefinitely, the team emphasized that third-quarter real final sales growth of only 1.2 percent showed underlying weakness.
- Inflation was below the Federal Reserve’s generally preferred range of 1.6 to 2 percent. October headline PCEPI was 1.3 percent, core PCEPI was 0.9 percent, and core CPI was 0.6 percent over the preceding 12 months.
- Low aggregate demand was limiting upward pressure on prices as households repaired their balance sheets. Personal consumption represented about 70 percent of GDP, but a high personal savings rate and a downward trend in consumer credit suggested that consumption would continue growing slowly.
- Labor costs were providing little inflationary pressure because the employment cost index rose only 0.5 percent in the second quarter and 0.4 percent in the third. Unit labor costs declined slightly more than 2 percent over the year, while real wages stagnated or declined slightly.
- Productivity growth was supporting profits without producing strong hiring. Third-quarter preliminary estimates showed output per hour rising 2.5 percent from a year earlier, while businesses favored investment in equipment and software and cost cutting instead of adding workers amid uncertain demand.
- The labor market was weaker than the 9.6 percent unemployment rate alone suggested. Many people were working part time for economic reasons, and the mean duration of unemployment reached an unprecedented 33.9 weeks since the Great Depression.
- Housing distress was restricting geographic mobility and sustaining economic weakness. Underwater mortgages discouraged households from selling, existing-home inventory equaled 10.5 months of supply in October, and nearly one-fourth of housing sales showed signs of mortgage distress.
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: Why did the VCU team support QE2 despite limited expected benefits?
The team described QE2 as an important safeguard against a rising risk of deflation, even though it believed quantitative easing was unlikely to improve economic conditions substantially. Its judgment reflected an economy facing slow growth, prolonged high unemployment, inflation below the Federal Reserve’s generally preferred range, weak labor costs, and substantial uncertainty surrounding the policy’s effects.
Q: What did third-quarter GDP data reveal about the recovery?
The BEA’s second estimate placed third-quarter real GDP growth at 2.5 percent, which was the lower bound of the team’s estimated potential-growth range of 2.5 to 2.8 percent. More than half of the change in real GDP over five quarters came from inventory adjustment, while real final sales increased only 1.2 percent, indicating weak underlying demand.
Q: Which components were contributing to economic growth?
Personal consumption, nonresidential investment, and government expenditure were the principal contributors to growth in the two most recent periods discussed. Revised data showed stronger consumption of goods and increased investment in equipment and software. Net exports improved in the second estimate, but they remained a drag on growth during the preceding three quarters.
Q: Why did residential investment decline in the third quarter?
Residential investment declined after the first-time home buyer tax credits ended in April. The team argued that stronger housing sales in the second quarter probably reflected buyers advancing their purchases to qualify for those credits. Once that temporary incentive expired, residential housing investment began subtracting from growth during the third quarter.
Q: Why was inflation considered too low in late 2010?
Inflation measures were below the Federal Reserve’s generally preferred range of 1.6 to 2 percent. The 12-month seasonally adjusted headline PCEPI for October was 1.3 percent, core PCEPI was 0.9 percent, and core CPI was 0.6 percent. The team concluded that these rates were too low to align with maximum employment and price stability.
Q: How were productivity and business investment affecting employment?
Output per hour was estimated to have risen 2.5 percent over the year through the third quarter, slightly above its long-term trend. Businesses also maintained high investment in equipment and software. The team interpreted these developments as evidence that firms facing uncertain demand and price-sensitive consumers preferred capital deepening and cost cutting over hiring additional workers.
Q: Why did the team believe unemployment was understated?
The official unemployment rate was 9.6 percent, but the large number of people working part time for economic reasons suggested broader labor underutilization. The mean unemployment duration was also 33.9 weeks, an unprecedented level since the Great Depression. These conditions indicated that the headline unemployment rate did not fully capture labor market weakness.
Q: How did housing problems contribute to structural unemployment?
Low housing sales and underwater mortgages made households reluctant to sell their homes at a loss, limiting their ability to relocate for available jobs. The team connected this geographic immobility with an outward movement of the Beveridge curve. It acknowledged that cyclical unemployment remained dominant, but identified skills and location mismatches beyond monetary policy’s scope.
Summary & Key Takeaways
-
Virginia Commonwealth University’s shadow committee described the economy as entering a long period of slow growth and prolonged high unemployment. It considered QE2 unlikely to improve conditions substantially, yet viewed the policy as an important safeguard because indications of deflation risk had increased. The team emphasized that considerable uncertainty surrounded the Federal Reserve’s move.
-
Third-quarter real GDP growth was estimated at 2.5 percent, matching the lower bound of the team’s 2.5 to 2.8 percent potential-growth range. Inventory adjustments produced more than half of real GDP’s change over five quarters, while real final sales grew only 1.2 percent, making the apparent recovery less sustainable.
-
Inflation remained below the Federal Reserve’s generally preferred range, while unemployment stood at 9.6 percent and average unemployment duration reached 33.9 weeks. Weak wage growth, falling unit labor costs, productivity gains, distressed housing, underwater mortgages, and geographic or skills mismatches reinforced the team’s expectation of a slow and uneven recovery.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from Federal Reserve 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator