Why Could Japan Lead the Next Startup Era?
TL;DR
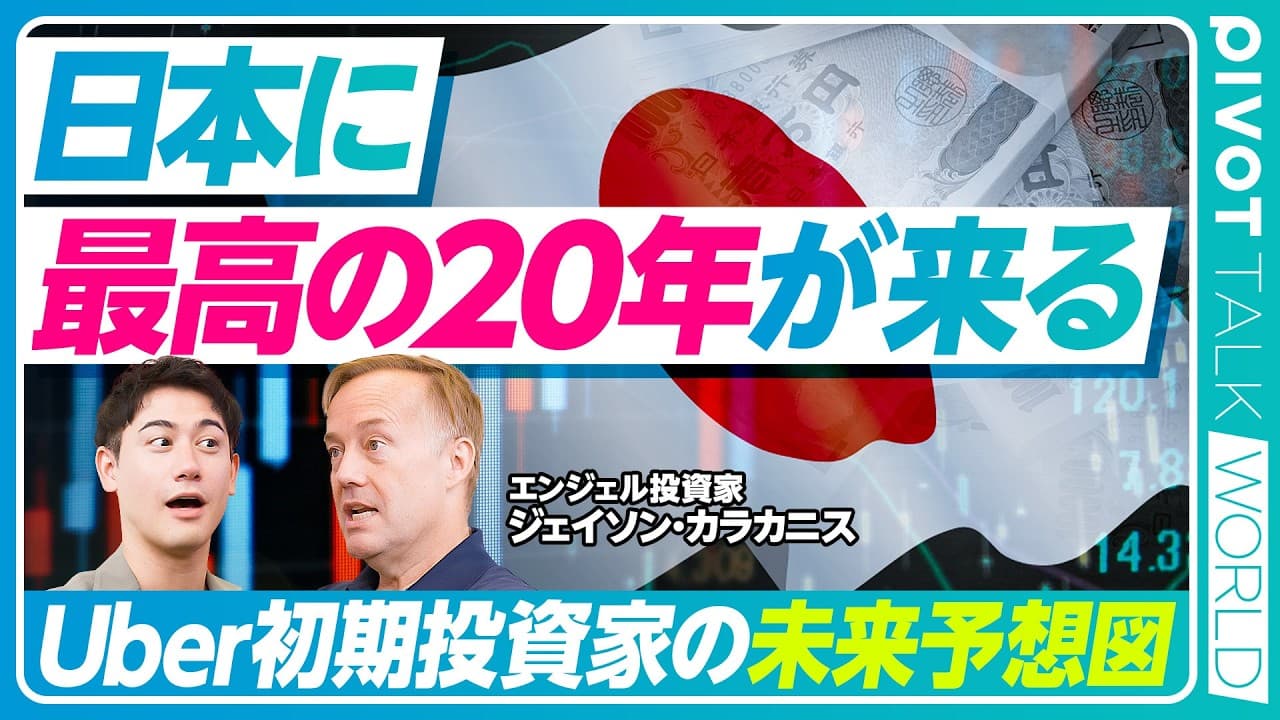
Japan could enjoy its strongest startup period over the next 20 years because its culture already values craftsmanship, design, continuous improvement, and persistence. Jason Calacanis argues that fear of failure is declining across generations, while AI investment should be understood through power-law returns, where a few enormous winners can compensate for many failed companies.
Transcript
Do you think it's bubble or just the beginning of AI era? I don't see it as negative. And are people overspending? Yes. But the people who are making all these investments in America can afford to lose it. The capital allocators in America, they understand something called the power law. reports suggest that OpenAI and Anthropic alone account for n... Read More
Key Insights
- Japan's working culture is highly compatible with entrepreneurship because pride in work, attention to aesthetics, careful execution, kaizen, purpose, and responsibility are visible across many occupations, not only among startup founders.
- Fear of failure is a major constraint on Japanese entrepreneurship because the cultural weight attached to honor can make an unsuccessful company feel personally damaging, even though startup progress often requires repeated attempts and changes in direction.
- Japan's entrepreneurial outlook is improving because younger families increasingly view startup experience as valuable rather than treating stable, long-term corporate employment as the only desirable path for their children.
- Startup failure can create valuable human capital because founders learn quickly through building companies, and even several unsuccessful attempts can prepare someone to become an unusually capable employee at a large organization.
- Founder persistence is presented as the decisive survival factor because companies can recover from lost customers, weak products, or depleted funding when leaders continue experimenting, find initial customers, adjust pricing, and refine the business.
- The idea maze is a model of entrepreneurial discovery in which founders repeatedly navigate combinations of markets, customer problems, and products until they find a workable route instead of abandoning the search.
- AI investment follows a power-law logic because a small number of extraordinary outcomes can return more capital than an entire portfolio cost, even when most funded companies fail and markets consolidate around one or two leaders.
- AI tokens may become largely free because smaller models are expected to run locally on laptops and phones, moving most token processing away from paid centralized services and weakening token-based revenue opportunities.
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: Why could Japan have a strong startup era?
Japan could have its strongest 20-year startup period because many qualities needed for company building are already embedded in its culture. These include pride in work, attention to detail, strong design instincts, kaizen, a sense of purpose, and persistence. A generational shift is also making entrepreneurship more acceptable, while Japanese companies and creative industries are again demonstrating global reach.
Q: What holds Japanese entrepreneurs back from taking risks?
A strong fear of failure can hold Japanese entrepreneurs back because failure may carry a heavy sense of shame or dishonor. Calacanis contrasts this with American startup culture, where unsuccessful founders commonly try again. He argues that Japanese entrepreneurs already possess discipline and product focus, but need greater willingness to pursue bold global ambitions and treat failed attempts as learning rather than permanent defeat.
Q: Why can startup failure still improve a founder's career?
Startup failure can improve a founder's career because building companies accelerates learning about products, customers, hiring, pricing, and adaptation. Calacanis argues that someone who attempts several startups and later joins a large company may become an unusually valuable employee. The experience is therefore not necessarily wasted, even when the ventures themselves never achieve lasting commercial success.
Q: Is the current AI boom a bubble or the start of an era?
The AI boom can involve bubble-like overspending while still resting on an important technological shift. Calacanis prefers to describe such cycles as waves: enthusiasm attracts many participants, some fail, and some discover durable businesses. A market correction does not erase the underlying progress if successful companies and technologies survive and continue changing how people work or use software.
Q: How does power-law investing work in startups?
Power-law investing assumes that a very small number of companies will generate most portfolio returns. Calacanis illustrates this with 100 companies raising $10 million each. If 99 fail but the remaining company becomes worth $10 billion, the original $1 billion invested across the group has turned into $10 billion in aggregate value. Widespread failure can therefore coexist with strong returns.
Q: Why do startup markets often produce only a few winners?
Startup markets often narrow to one or two large winners, sometimes accompanied by smaller companies serving specialized segments. Investors fund many competing attempts because they cannot know in advance which team will prevail. Under power-law economics, the value created by the leading company can outweigh losses from numerous failures, so a crowded market is not automatically evidence that investment was irrational.
Q: What is the idea maze in entrepreneurship?
The idea maze describes the search through possible combinations of markets, customer problems, and products. Some founders enter this maze and quit when their original approach fails. Others keep changing direction, learning from customers, and testing alternatives until they discover a workable path. Calacanis connects this persistence with companies that recover after losing customers, struggling with products, or running short of money.
Q: Why could most AI tokens eventually become free?
Most AI tokens could eventually become free because smaller models are expected to run directly on personal devices. Calacanis predicts that models will first operate on laptops and later become small enough for phones. If 90% of tokens are processed locally rather than through paid centralized infrastructure, companies may earn little or no direct revenue from those token operations.
Summary & Key Takeaways
-
Jason Calacanis sees Japanese culture as naturally compatible with entrepreneurship because workers demonstrate pride, attention to detail, aesthetic sensitivity, continuous improvement, purpose, and persistence. Japan's primary constraint has been an unusually heavy stigma around failure, which can discourage founders from taking bold risks or pursuing opportunities in global markets.
-
Attitudes toward entrepreneurship are changing across generations in Japan. Parents who once preferred prestigious, stable employment may now welcome their children starting companies. Even repeated startup failures can produce rapid learning and valuable experience, making former founders attractive employees if they later join an established corporation.
-
AI investment may contain overspending without making the underlying opportunity unimportant. American capital allocators expect many ventures to fail because returns follow a power law. Calacanis also predicts that smaller AI models will increasingly run on laptops and phones, making most locally processed tokens free rather than a lasting source of revenue.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from PIVOT 公式チャンネル 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator