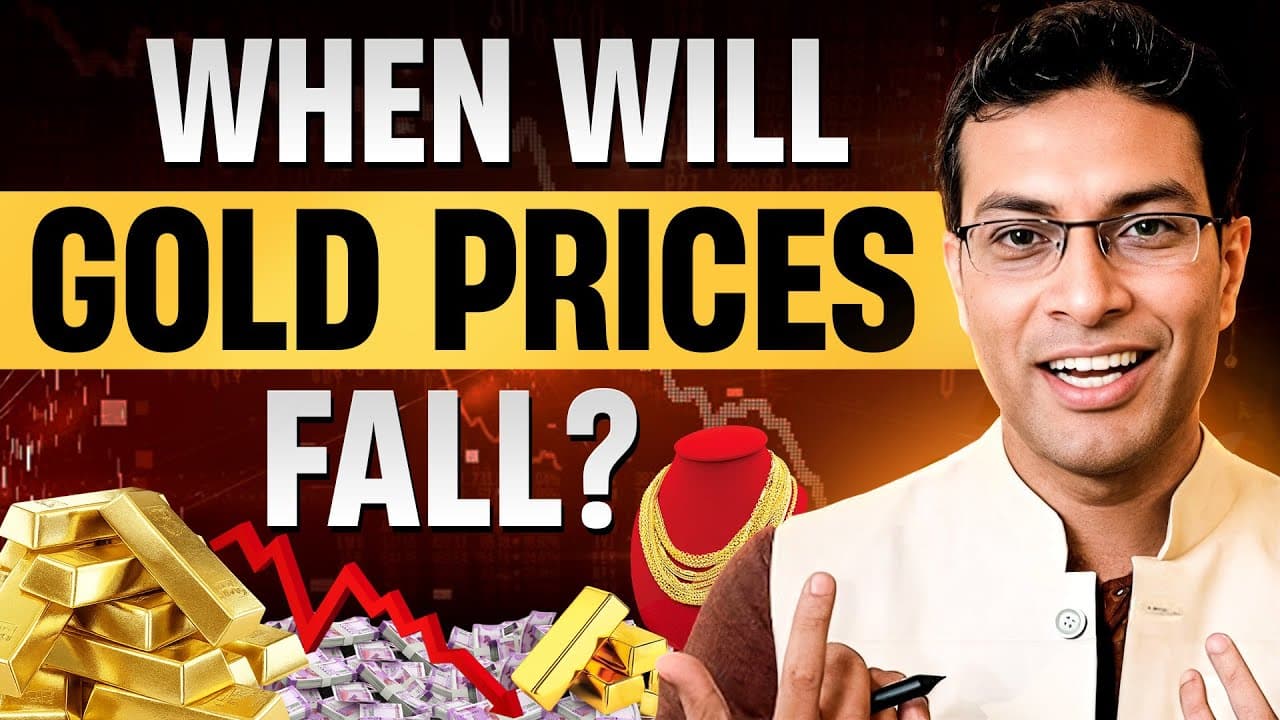
Why Could Gold Prices Fall 20% in 2026?
TL;DR
Gold could correct by 20% if policy conditions stabilize, the US dollar strengthens, corporate earnings improve, investors shift money toward stocks, or governments sell reserves. The forecast is presented as a possibility rather than a certainty, with the speaker choosing to wait for a substantial correction before entering instead of chasing prices after their post-2020 rise.
Transcript
Hi everyone. So here is the 100redyear history of gold and on this video I'm going to help you understand why is it that gold prices rises, why is it does it fall and we'll talk about some recent historic episodes. Why is it that I'm waiting for a 20% price correction on gold and only then I will enter. I'll give you a complete macroeconomic breakd... Read More
Key Insights
- Gold has historically gained during periods of crisis, including the 1930s depression, the 1970s inflation crisis, the dotcom crisis, and the COVID crisis. Wars, excessive money creation, and bond or currency concerns can increase demand for gold as uncertainty rises.
- Gold can experience corrections exceeding 20%, and the transcript identifies three major historical drawdowns. The post-1980 decline exceeded 50%, demonstrating that strong crisis-driven advances do not prevent gold from losing substantial value when economic and market conditions change.
- The 2012–2017 correction took gold from approximately $1,800 to $1,100. The speaker attributes the decline partly to economic and policy stabilization after quantitative easing supported gold following the 2008 crisis, showing that investors may lose considerable time as well as money.
- Policy stabilization could pressure gold in 2026 if trade tensions ease and confidence improves. According to the speaker, even a short-term resolution could stabilize or strengthen the US dollar, creating conditions for gold to correct despite persistent concerns about long-term trust in the United States.
- The DXY measures the US dollar against an aggregate of other currencies, rather than measuring its purchasing power against gold. The speaker sees the dollar near a strong pivot point and considers a rebound possible, while explicitly acknowledging that its future direction cannot be predicted with certainty.
- The 1996–2000 gold decline moved prices from roughly $400 to $275, a correction of about one third. The speaker connects this fall to rapid US economic growth, strong stock-market performance, technology enthusiasm, capital moving from gold into stocks, and government gold sales.
- Government reserve activity can materially affect gold demand and supply. Recent purchases by countries such as China and India have supported demand, while substantial government selling in 2026 or 2027 could increase supply and contribute to a significant correction in the gold price.
- Corporate earnings could trigger a shift away from gold if aggregate results from companies such as Microsoft, Nvidia, and Tesla continue improving. Stronger earnings may convince investors that economic conditions are healthier, encouraging stock purchases and weakening demand for crisis-oriented gold exposure.
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: Why could gold prices fall by 20% in 2026?
Gold could fall by 20% if several conditions develop: trade and economic policies stabilize, the US dollar strengthens, the US economy performs better than expected, corporate earnings keep improving, investors move money from gold into stocks, or governments sell gold reserves. The speaker treats these as plausible scenarios rather than guaranteed outcomes and is therefore waiting for a substantial correction before entering.
Q: Why does gold usually rise during economic crises?
Gold tends to rise during crises because wars, excessive government money creation, inflation, and concerns about bonds or currencies can increase demand for it. The transcript points to advances associated with the 1930s depression, the 1970s inflation crisis, the dotcom crisis, and the COVID crisis. Continued geopolitical and policy complications after 2020 are also presented as support for recent prices.
Q: How large have previous gold price corrections been?
Previous gold corrections have exceeded 20% and, in one cited case, exceeded 50%. After trading near $700 in 1980, gold fell to roughly $350. Another decline took gold from approximately $1,800 in 2012 to $1,100 by 2017. Between 1996 and 2000, it dropped from about $400 to $275, representing a correction of roughly one third.
Q: Why did gold decline between 2012 and 2017?
Gold had gained momentum after the 2008 crisis because the US government used quantitative easing, described as injecting or printing substantial money into the economy. By 2012, the economy and related policies had begun to stabilize. Gold subsequently declined from approximately $1,800 to $1,100 by 2017, producing both a major price loss and a prolonged waiting period for holders.
Q: How could a stronger US dollar affect gold prices?
A stronger US dollar could contribute to a gold correction because policy stabilization may improve confidence in the currency and reduce some demand for gold. The speaker uses DXY to assess the dollar against an aggregate of other currencies and sees it near a strong pivot point. A rebound is considered possible, although the transcript explicitly avoids claiming that such strengthening will certainly occur.
Q: Why did gold fall from 1996 to 2000?
Gold fell from roughly $400 in 1996 to about $275 by 2000 as the US economy grew rapidly, technology enthusiasm increased, funding expanded, and the stock market performed strongly. Investors redirected money from gold into stocks. Government gold sales also added pressure, illustrating how economic optimism, attractive equity returns, and additional official supply can combine to weaken gold prices.
Q: How could government gold sales cause a correction?
Government transactions can change the balance between demand and supply in the gold market. Purchases by governments such as those of China and India have increased demand because gold is being added to their treasuries. If a government, including the US government in the speaker's hypothetical scenario, sells a large quantity of reserves in 2026, the resulting increase in selling could push prices lower.
Q: What economic signal could trigger investors to leave gold for stocks?
Rising aggregate corporate earnings could become the trigger. Companies such as Microsoft, Nvidia, and Tesla report earnings every three months, and continued improvement could persuade investors that the US economy is healthier than feared. That change in confidence may encourage people to buy stocks instead of gold, especially if AI and semiconductor investment also supports stronger US economic performance in 2026 or later.
Summary & Key Takeaways
-
Gold has historically risen during major crises, including the 1930s depression, the 1970s inflation crisis, the dotcom era, and the COVID crisis. The speaker links these advances to economic instability, wars, excessive money creation, and currency or bond concerns, while emphasizing that gold can also experience severe and prolonged corrections.
-
Past drawdowns illustrate the downside risk. Gold fell from approximately $1,800 in 2012 to $1,100 by 2017, declined from about $400 in 1996 to $275 by 2000, and suffered a correction exceeding 50% after trading near $700 in 1980. Investors can lose both capital and time.
-
A possible 2026 correction could follow policy stabilization, a stronger US dollar, improving corporate earnings, renewed demand for stocks, government gold sales, or stronger US economic performance driven by AI and semiconductor competition. These outcomes remain estimates, so the speaker plans to wait for a 20% decline before purchasing gold.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from Akshat Shrivastava 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator