How to Avoid Tax Mistakes That Trigger Audits
TL;DR
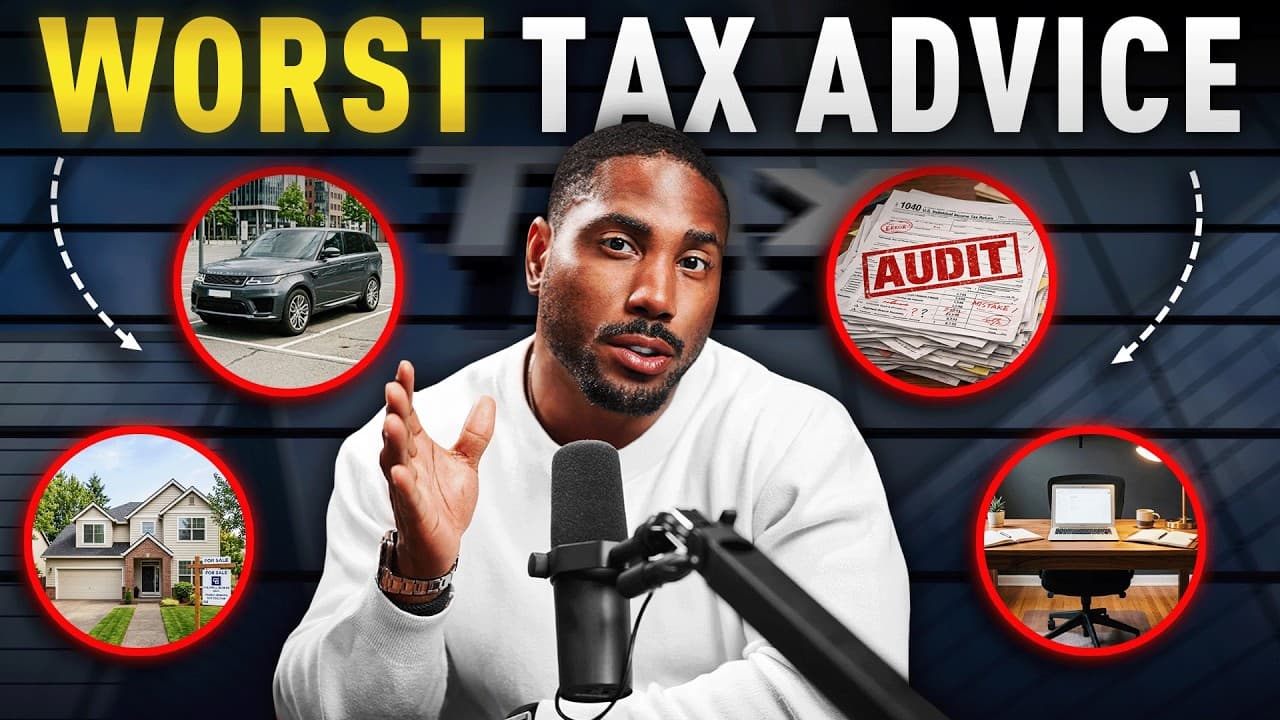
Avoid tax shortcuts that lack a genuine business purpose, proper qualification, or contemporaneous documentation. Safer planning means reporting all income, deducting only legitimate business use, paying reasonable S corporation compensation, tracking real estate participation carefully, and recognizing that entity formation or a purchase alone does not automatically create tax savings.
Transcript
Here's the truth. Good tax advice is a powerful wealth building multiplier. [music] But bad tax advice is a wealth destroyer. So today, I'll walk you through the top 10 tax traps [music] that quietly drain your wealth, that trigger audits, and create long-term financial damage. Knowing [music] how to avoid these traps can help you make confident, i... Read More
Key Insights
- Land is not depreciable, so purchasing a property with a high land-to-building ratio can reduce depreciation rather than increase it. Investors seeking larger depreciation deductions should focus on the quality and proportion of depreciable improvements instead of buying acreage solely for tax reasons.
- A business vehicle deduction requires genuine business use and careful records of mileage, trips, and the division between business and personal use. Unsupported claims of 90 or 100 percent business use, especially for luxury vehicles or SUVs, may be disallowed and can increase audit exposure.
- An S corporation requires an owner-employee to receive reasonable compensation before taking distributions. The salary should be comparable to pay for similar work in the same field, and skipping payroll or using an unrealistically low wage can lead to reclassified distributions, back taxes, penalties, and interest.
- A basic LLC does not automatically produce tax savings. A single-member LLC is treated like a sole proprietorship unless it makes a specific tax election, while a multi-member LLC is a partnership, so meaningful tax changes depend on elections and planning rather than the LLC label alone.
- The home office deduction requires a space used exclusively and regularly for business. A dual-purpose room, shared family area, or occasionally used desk in a bedroom does not satisfy the stated criteria, and an unsupported claim can lead to scrutiny of other deductions on the return.
- Most entertainment expenses are non-deductible under the Tax Cuts and Jobs Act of 2017. Sporting events, concerts, golf outings, and luxury boxes generally cannot be written off as entertainment, and relabeling them as meals, marketing, or client development creates additional risk.
- Real estate professional status requires at least 750 hours of material participation in real estate and more than half of the taxpayer's working time in a real estate business. Clear time records are essential because intent, verbal explanations, and estimates prepared after the fact are inadequate.
- Side hustle income must be reported even when it is not a taxpayer's main source of earnings. Information from 1099s and payment platforms makes omissions easier to detect, so the safer approach is to report the income and apply legitimate deductions and planning strategies.
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: How can real estate investors maximize depreciation deductions?
Real estate investors seeking depreciation should focus on properties with a high building-to-land ratio and valuable depreciable improvements. Land itself is not depreciable, so a purchase price allocated heavily to land leaves a smaller depreciable basis. Buying extensive acreage merely to obtain a larger deduction misunderstands the rule and may actually reduce the available depreciation.
Q: What records are needed to deduct a business vehicle?
A vehicle deduction should be supported by careful records showing mileage, individual trips, business purposes, and the percentage of use attributable to business rather than personal activity. Purchasing a vehicle does not create an automatic write-off. Claims of 90 or 100 percent business use without proof, particularly for luxury vehicles and SUVs, can be disallowed and may attract audit attention.
Q: Why must an S corporation owner receive a reasonable salary?
An owner-employee of an S corporation must receive reasonable compensation before taking distributions. Salary is subject to payroll taxes, while distributions are not, which creates potential savings within the rules. If the owner skips payroll or reports an unrealistically low wage, the IRS may reclassify distributions as wages and assess back taxes, penalties, interest, and related fees.
Q: Does forming an LLC automatically reduce taxes?
Forming a basic LLC does not automatically reduce taxes. A single-member LLC remains equivalent to a sole proprietorship unless a specific tax election is made, while a multi-member LLC is treated as a partnership. Without further planning, the owner may receive no new tax benefit while taking on annual fees, compliance obligations, administrative work, and other costs.
Q: When does a home office qualify for a tax deduction?
A home office qualifies only when the space is used exclusively and regularly for business. A shared family room, a dual-purpose room, or a desk in a bedroom used only occasionally does not meet the stated requirements. The deduction is legitimate when properly supported, but stretching the definition can cause disallowance and broader scrutiny of deductions elsewhere on the return.
Q: Are client entertainment expenses tax deductible?
Most entertainment expenses are not deductible under the Tax Cuts and Jobs Act of 2017. Examples identified include sporting events, concerts, golf outings, and luxury boxes. Certain meal expenses may remain partially deductible in some circumstances, but entertainment cannot safely be disguised as meals, marketing, or client development because misclassification can lead to penalties if discovered.
Q: How do taxpayers qualify for real estate professional status?
A taxpayer must spend at least 750 hours materially participating in real estate and devote more than half of all working time to a real estate business. Clear documentation of qualifying time is essential. Intent, verbal descriptions, and estimates created after the fact do not establish eligibility, and without adequate records the claimed treatment can collapse when questioned.
Q: Do taxpayers have to report income from a side hustle?
Side hustle income must be reported even when the activity is small, part-time, or unrelated to a person's main job. The IRS does not distinguish between primary and side income for this purpose, and 1099s, payment platforms, and expanded information reporting make omissions easier to identify. Taxpayers should report earnings and then use legitimate deductions and strategies.
Summary & Key Takeaways
-
Effective tax planning depends on understanding what actually qualifies for deductions. Land cannot be depreciated, personal vehicle use cannot be treated as business use, and a home office must be used exclusively and regularly for business. Transactions chosen mainly for hoped-for write-offs can instead reduce deductions or attract scrutiny.
-
Business structures create tax benefits only when paired with appropriate elections, operations, and compliance. A basic LLC does not automatically change federal tax treatment, while an S corporation requires reasonable owner compensation before distributions. Ignoring these distinctions can produce annual costs, reclassified wages, back taxes, penalties, and interest.
-
Strong records support defensible tax positions. Real estate professionals must document qualifying hours and material participation, side hustle income must be reported, and vehicle deductions require business-use records. Tax return preparation also differs from forward-looking strategy, which may involve entity structure, timing decisions, and coordination before opportunities disappear.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from Karlton Dennis 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator