How Does Implied Volatility Guide Options Trades?
TL;DR
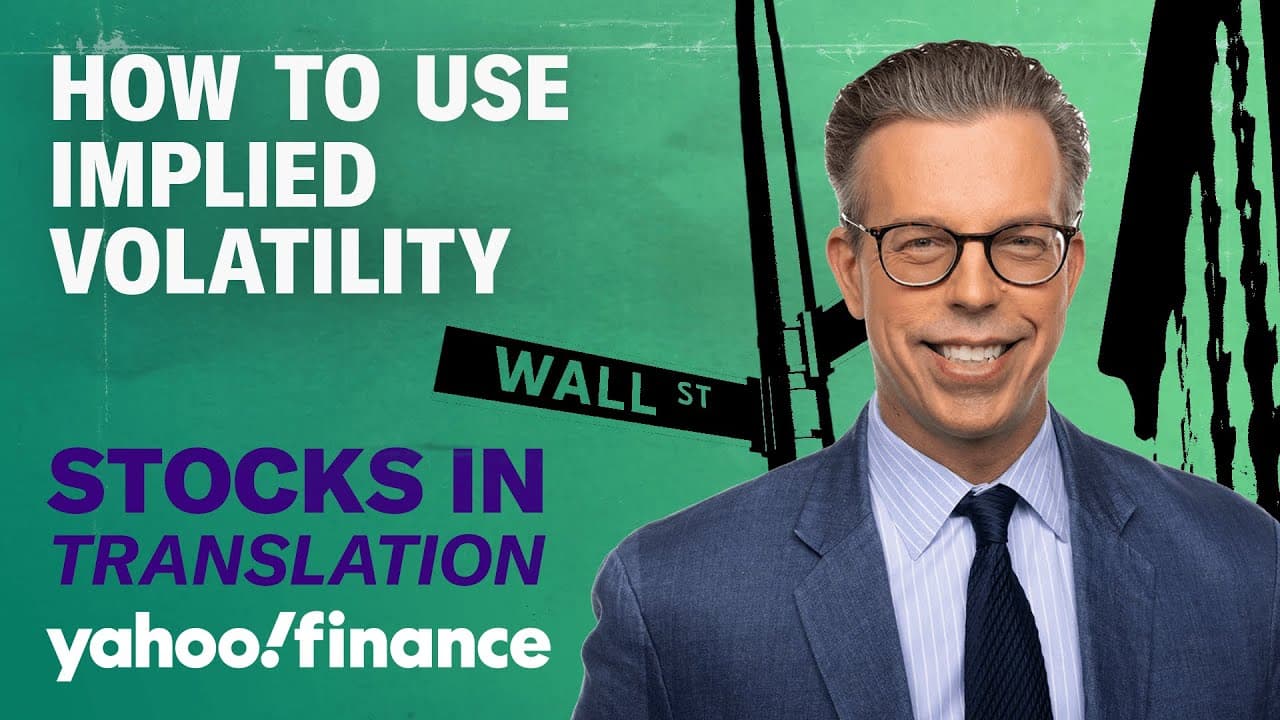
Implied volatility guides options trades by estimating the potential size, not the direction, of a price move. Tom Sosnoff adds context with implied volatility rank, a 0–100 scale on which he considers readings above 30 high, and uses expected-move boundaries to select strikes, targets, and exits. Read on to see how these measures support bullish, bearish, and premium-selling strategies while keeping risk small.
Transcript
welcome to stocks and translation broadcasting from New York New York I'm Jared blicker your host and once again I have the people's voice Sydney freed by my side first please like subscribe and comment on stocks and translation on Spotify Apple music Amazon or YouTube today we are welcoming back Tom snoff you know him as the founder of tasty trade... Read More
Key Insights
- Implied volatility is another way to express the market’s expected price move. A higher value indicates that the underlying asset may travel through a wider price range, but the measure does not predict whether that move will be upward or downward.
- A raw implied volatility number is difficult to interpret without context. Knowing that Tesla has implied volatility of 74 or IBM has implied volatility of 42 does not independently reveal whether either reading is unusually high or low for that particular stock.
- Implied volatility rank is a 0–100 scale that gives current volatility a comparative context. Sosnoff cites Tesla with implied volatility of 74 and a rank of 77, making it potentially interesting for traders seeking a large move or selling option premium.
- An implied volatility rank above 30 is considered high in Sosnoff’s framework. Higher-ranked opportunities appeal to premium sellers because volatility helps determine where they can establish short calls, short puts, call spreads, or put spreads around the expected price range.
- Expected move is useful beyond options trading because it provides a reference range for stock positions. A bullish trader can use that range to choose a reasonable profit target, while also placing a mental exit based on the market’s projected movement.
- Short-term market prices incorporate widely available information under Sosnoff’s efficient-market view. He therefore gives less weight to macroeconomic narratives and company fundamentals, concentrating instead on his subjective assessment of price extremes, implied volatility rank, and expected-move levels.
- Options strategies are combinations of a limited set of basic structures. Sosnoff divides them broadly into vertical and horizontal approaches, then uses variations such as selling puts to become bullish and selling calls to establish bearish exposure.
- Small position size is the first risk-control principle for beginning traders. Sosnoff argues that keeping trades small also keeps potential risk small, while controlling ego helps prevent the position growth that can cause even knowledgeable traders to fail.
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: What does implied volatility mean for options traders?
Implied volatility represents the market’s expected price move. A higher reading indicates a wider potential move, while a lower reading suggests calmer expectations. It measures potential magnitude rather than predicting direction.
Q: Does implied volatility predict whether a price will rise or fall?
No. Implied volatility describes a plus-or-minus expected range without indicating whether the move will be upward or downward. Bullish, bearish, and premium-selling traders can therefore use the same reading in different ways.
Q: Why is a raw implied volatility number difficult to use?
A raw reading does not show whether volatility is unusually high or low for that specific asset. Sosnoff illustrates this with Tesla at 74 and IBM at 42, noting that those figures alone lack context. A comparative measure such as implied volatility rank makes the readings more useful.
Q: What is implied volatility rank?
Implied volatility rank places current volatility on a 0–100 scale to provide comparative context. Sosnoff considers anything above 30 high. He cites Tesla with implied volatility of 74 and an IV rank of 77, making it potentially interesting for a large-move trade or premium sale.
Q: How can expected move help set trading targets and exits?
Expected move provides a reference range for how far an asset may travel during a chosen period. A bullish stock trader can use that range to select a reasonable profit target and establish a mental exit. It also helps define risk parameters rather than guaranteeing a particular result.
Q: How does a premium seller use implied volatility?
A premium seller can use implied volatility rank to identify underlyings with relatively elevated volatility and expected-move levels to choose trade locations. Sosnoff considers higher volatility more attractive for premium selling. His structures include short calls, short puts, call spreads, and put spreads.
Q: What trading approach does Tom Sosnoff follow?
Sosnoff follows an efficient-market perspective, believing widely known short-term macroeconomic and company information is already reflected in prices. He instead emphasizes subjective price extremes, implied volatility rank, and expected-move boundaries. He sells puts for bullish exposure and calls for bearish exposure.
Q: How should beginners manage risk when trading options?
Sosnoff’s first principle is to keep every position small because small size keeps potential risk small. He also advises controlling ego so growing confidence does not lead to oversized positions. Even traders who understand strategies and market mechanics can fail when their positions become too large.
Summary & Key Takeaways
-
Implied volatility can be understood as expected move: a higher reading indicates a wider potential move in either direction. That wider range can create more opportunity for bullish, bearish, and premium-selling traders, but the raw volatility number needs context before it can meaningfully guide a trading decision.
-
Implied volatility rank places current volatility on a 0–100 scale. Sosnoff considers a rank above 30 high and uses the measure to identify potentially attractive premium-selling opportunities. Expected-move estimates can also help stock traders establish reasonable profit targets, mental exit points, and risk parameters over a chosen period.
-
Sosnoff follows an efficient-market perspective, believing widely known macroeconomic and company information is already reflected in short-term prices. His decisions instead emphasize subjective price extremes, implied volatility rank, and expected-move boundaries. He sells puts to express bullish exposure, sells calls for bearish exposure, and advises beginners to trade small.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from Yahoo Finance 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator