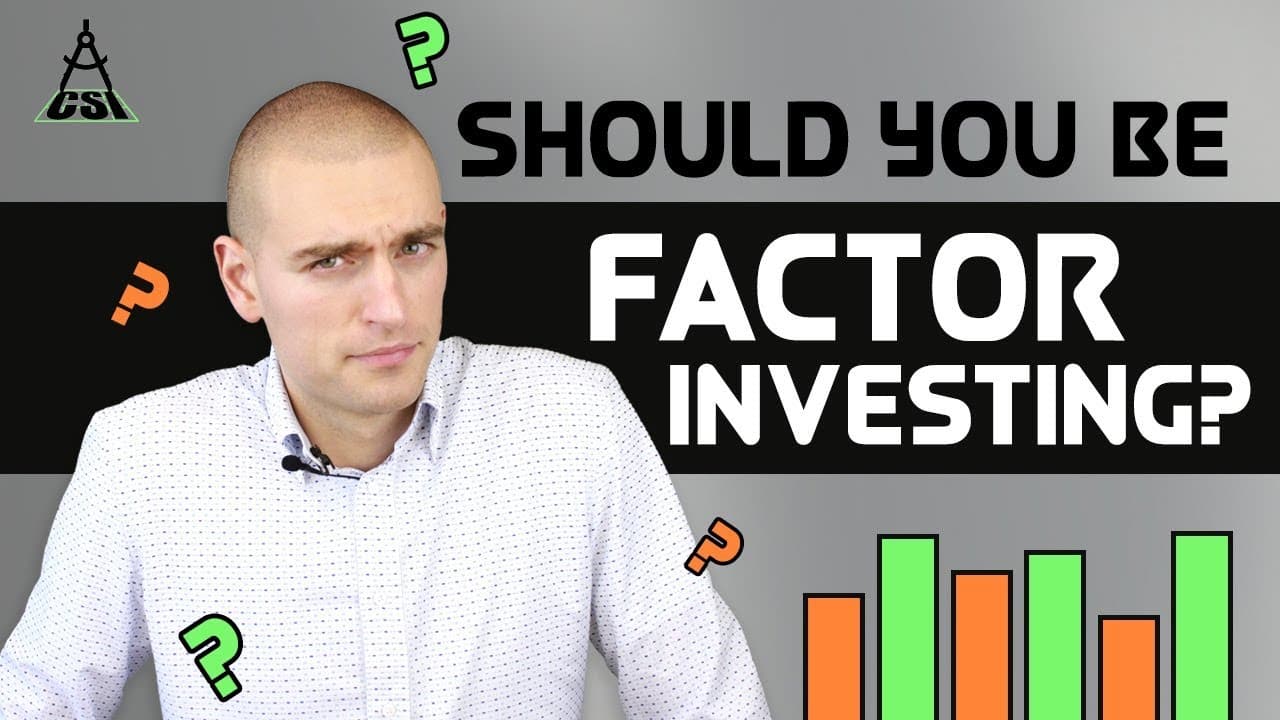
Should You Be Factor Investing?
TL;DR
Factor investing can help investors pursue market-beating returns without stock picking or market timing, but only when the targeted factors are persistent, pervasive, robust, investable, and sensible. Factor models explain over 95% of return differences between diversified portfolios, while more than 300 proposed factors have appeared in academic literature. Read on to understand which factors have evidence and why implementation costs matter.
Transcript
Factor investing is currently one of the hottest terms used to sell financial products. You may have also heard the term smart beta, which is referring to the same concept. A simple way to think about factors is that they are quantitative characteristics shared across a set of securities. The reason that we care about factors is that those ... Read More
Key Insights
- 🧑🏭 Factors are quantitative characteristics that drive asset returns and can be used to outperform the market.
- 🧑🏭 Active fund managers' outperformance can often be explained by factor exposure instead of skill.
- 🧑🏭 Factor models explain over 95% of the return differences between diversified portfolios, limiting the benefits of active management.
- 💓 Investing in factor index funds can save investors on fees and capture market-beating returns.
- 💨 Factor research has become important in financial understanding and a way for researchers to make a name for themselves.
- 👿 More than 300 factors have been identified, but many do not pan out or lack robustness.
- 🧑🏭 Dimensional Fund Advisors is a company that effectively implements factor research in their products.
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: Should you use factor investing?
Factor investing can structure a portfolio to pursue market-beating returns without relying on stock picking or market timing. However, some products marketed around factors may be detrimental, so investors should seek factors that are persistent, pervasive, robust, investable, and sensible.
Q: What is factor investing, and is it the same as smart beta?
Factors are quantitative characteristics shared across a set of securities, and factor investing uses those characteristics to structure a portfolio. Smart beta refers to the same concept.
Q: Which factors are included in the major factor models?
The discussed factors include market, size, relative price, profitability, investment, and momentum. Fama and French’s 2014 five-factor model combines market, size, relative price, profitability, and investment while omitting momentum.
Q: How much of portfolio performance can factor models explain?
Factor models currently explain over 95% of the return differences between diversified portfolios. Five factors identified through the research discussed also explain over 95% of those differences.
Q: Can factor exposure explain active fund managers’ outperformance?
Yes, factor exposure can explain outperformance that might otherwise be attributed to manager skill. In Justin Bender’s 2015 analysis of several market-beating mutual funds, factor exposure fully explained the outperformance in most cases and mostly explained it in one case.
Q: Why can factor index funds cost less than active funds?
An active fund may beat the market simply by holding more small-cap and value stocks rather than by selecting or timing stocks skillfully. An index investor can replicate that exposure at a fraction of the cost of an actively managed fund, saving on fees.
Q: How can investors judge whether a factor is worth pursuing?
A credible factor should be persistent through time, pervasive across countries, regions, and sectors, and robust when its definition changes slightly. It should also be cost-effectively investable and have a sensible explanation for its returns.
Q: Why shouldn’t investors pursue every identified factor?
Researchers have identified over 300 factors in academic literature, but many do not pan out or merely repackage the original factors. Momentum also shows why evidence alone is insufficient: its high turnover makes it expensive to implement in a portfolio.
Summary & Key Takeaways
-
Factors are quantitative characteristics that can be used to structure an investment portfolio for better returns.
-
Factor investing emerged when diversified portfolios of small stocks outperformed larger stocks, leading to the discovery of certain characteristics that explain return differences.
-
Active fund managers' ability to beat the market is often explained by factor exposure rather than skill, making factor index funds a cost-effective alternative.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from Ben Felix 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator