How Does Infrastructure Investing Create Wealth?
TL;DR
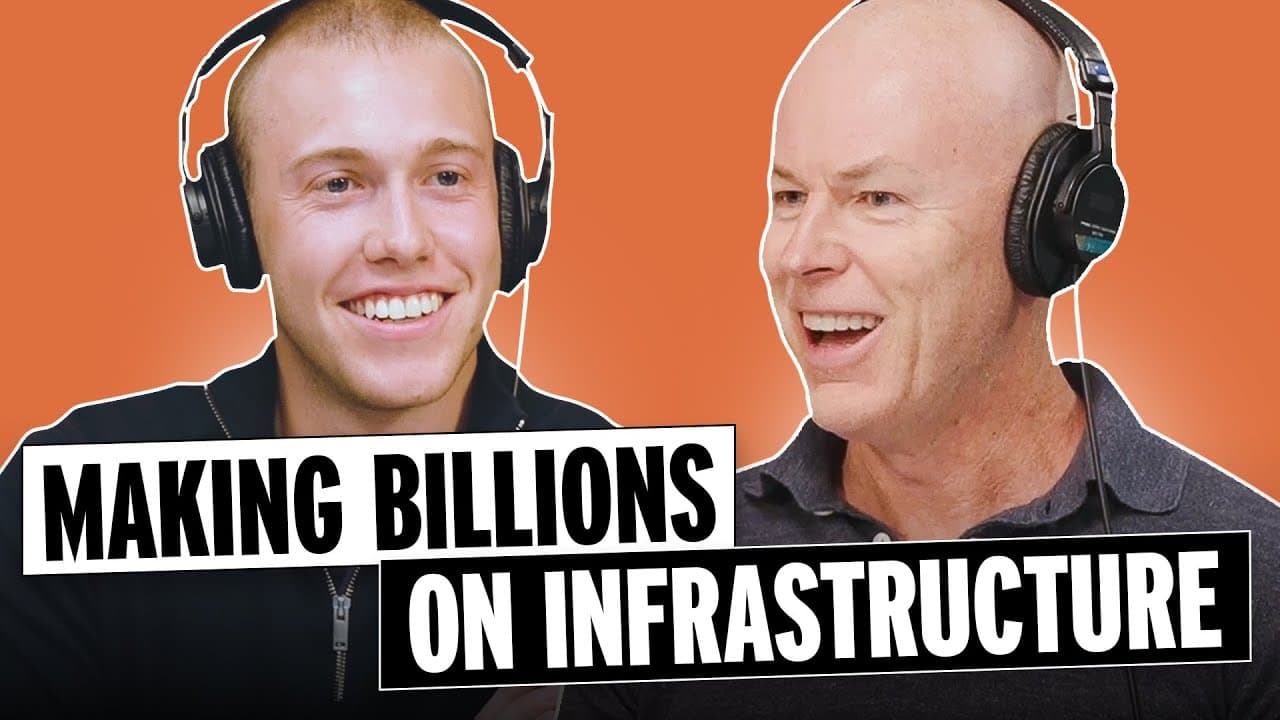
Infrastructure investments can generate stable, long-term, partly inflation-linked cash flows because essential assets often face limited competition and operate under regulated pricing. Stonepeak focuses on energy, communications, and transportation infrastructure, where data growth, the energy transition, and changing supply chains support demand. The firm manages a $73 billion portfolio and, according to the introduction, has never lost money on an investment.
Transcript
Welcome to First Time Founders. I'm Edson. Most of us don't think twice about the things that make our lives run. Highspeed internet, lights that switch on instantly, or even clean water from the tap. But behind all of that is infrastructure, the invisible backbone of modern life. And while most people ignore it, my next guest saw an opportunity hi... Read More
Key Insights
- Infrastructure assets are essential economic building blocks, including airports, toll roads, utilities, communications networks, energy systems, ports, and railways. Their importance supports durable demand because households, businesses, and governments depend on the services they provide throughout ordinary economic activity.
- Natural monopolies are common in infrastructure because competing directly with an established airport, toll road, or utility can be impractical. These barriers create large competitive moats, although governments often regulate pricing to prevent asset owners from exploiting their unusually strong market positions.
- Infrastructure cash flows are relatively predictable because essential demand persists and regulated pricing paths can provide visibility. These qualities can produce stable, long-term, somewhat inflation-linked returns that are easier to forecast than the future earnings of many faster-changing businesses.
- Private infrastructure investing developed in Australia when state governments began selling assets during the late 1980s and early 1990s. Macquarie raised outside capital to acquire airports, toll roads, utilities, and communications assets, then helped extend the model into Europe, Canada, and the United States.
- Infrastructure investing spans three broad categories: energy, communications, and transportation. Energy includes pipelines, wind, and solar assets. Communications includes data centers, towers, and fiber cables. Transportation includes railways, toll roads, ports, and logistics-related facilities.
- Digital infrastructure demand is supported by rapidly increasing data consumption, which the interview says compounded at roughly 50 percent annually over about two decades. AI added further demand, increasing the need for data centers, fiber cables, cell towers, and related systems.
- Energy infrastructure requires investment in both transition technologies and traditional systems. Wind turbines and solar projects benefit from the energy transition, while conventional energy assets still require maintenance and upkeep, creating opportunities across old and new parts of the energy system.
- Infrastructure occupies the investment space between private credit and private equity. Mature roads and airports can resemble long-term bonds through forecastable cash flows, while data centers with 15-year customer contracts can offer downside visibility alongside characteristics associated with private equity.
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: What is infrastructure investing?
Infrastructure investing is the ownership or financing of essential assets that support society and the economy. Examples include airports, toll roads, electric utilities, pipelines, renewable energy projects, data centers, cell towers, fiber cables, railways, ports, and logistics facilities. These businesses often have durable demand, large competitive moats, regulated pricing, and relatively visible long-term cash flows.
Q: Why can infrastructure assets produce predictable cash flows?
Infrastructure assets can produce predictable cash flows because their services are essential, demand often remains durable, and direct competition may be limited by large barriers to entry. Regulation can also establish a reasonably clear pricing path. Together, these features make future revenue easier to forecast than revenue for businesses exposed to rapid technological change or intense competitive pressure.
Q: Why are infrastructure businesses often regulated?
Infrastructure businesses are often regulated because many operate like natural monopolies. A local airport, toll road, or utility may face little realistic competition, giving its owner significant pricing power. Governments therefore restrict what these businesses can charge. Regulation limits potential abuse while also helping investors understand the likely pricing framework and forecast long-term cash flows with greater confidence.
Q: What types of assets count as infrastructure investments?
Infrastructure investments fall mainly into energy, communications, and transportation. Energy assets include oil and gas pipelines, wind turbines, and solar projects. Communications assets include data centers, cell phone towers, and fiber-optic cables. Transportation assets include airports, railways, toll roads, ports, and logistics facilities. Utilities and systems supporting food provision also fit within the broader essential-services category.
Q: How did private infrastructure investing develop?
Private infrastructure investing developed in Australia after state governments began selling government-owned businesses in the late 1980s and early 1990s. Macquarie raised capital from outside investors through listed acquisition vehicles, including a vehicle designed to bid for Sydney Airport. It repeated the approach across toll roads, utilities, airports, and communications assets before taking the model to other countries.
Q: How is infrastructure investing different from private equity and credit?
Infrastructure sits between private credit and traditional private equity. A mature toll road or airport can resemble a long-term bond because its cash flows can be forecast with considerable accuracy, although not with certainty. A data center can have more equity-like characteristics, but a 15-year contract with a major customer can still provide visibility into a potential downside scenario.
Q: Why are data centers attractive infrastructure assets?
Data centers benefit from rising data consumption and increased demand connected to AI. They can also secure long-term customer agreements. The interview describes Microsoft, Google, or Amazon providing 15-year contracts for data-center capacity. Such contracts do not eliminate investment risk, but they can provide meaningful visibility into revenue and help investors estimate a plausible worst-case outcome.
Q: What trends are supporting infrastructure investment opportunities?
Three broad trends support infrastructure demand. Digital data consumption requires more data centers, fiber cables, and cell towers. The energy transition requires wind, solar, and related systems, while traditional energy infrastructure still needs upkeep. Transportation and logistics networks are also changing as geopolitical fractures encourage reshoring and friendshoring, altering supply chains and the assets needed to support them.
Summary & Key Takeaways
-
Infrastructure includes essential assets such as airports, toll roads, electric utilities, pipelines, renewable energy projects, data centers, cell towers, fiber cables, railways, ports, and logistics facilities. Many possess large competitive moats or natural monopoly characteristics because constructing a viable alternative can be impractical, expensive, or impossible within the same market.
-
Infrastructure became accessible to private capital after Australian state governments began selling government-owned assets in the late 1980s and early 1990s. Macquarie helped establish the asset class by raising investor capital through listed vehicles, acquiring assets such as airports and toll roads, and expanding the investment model internationally across Europe, Canada, and the United States.
-
Infrastructure occupies an investment spectrum between private credit and traditional private equity. Mature airports and toll roads offer relatively predictable cash flows, while contracted data centers combine downside visibility with equity-like potential. Stonepeak invests amid three major trends: rising data consumption, energy transition and maintenance, and supply-chain changes driven by reshoring and friendshoring.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from The Prof G Pod – Scott Galloway 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator