How Fed Rate Cuts Could Affect Stocks and Bonds
TL;DR
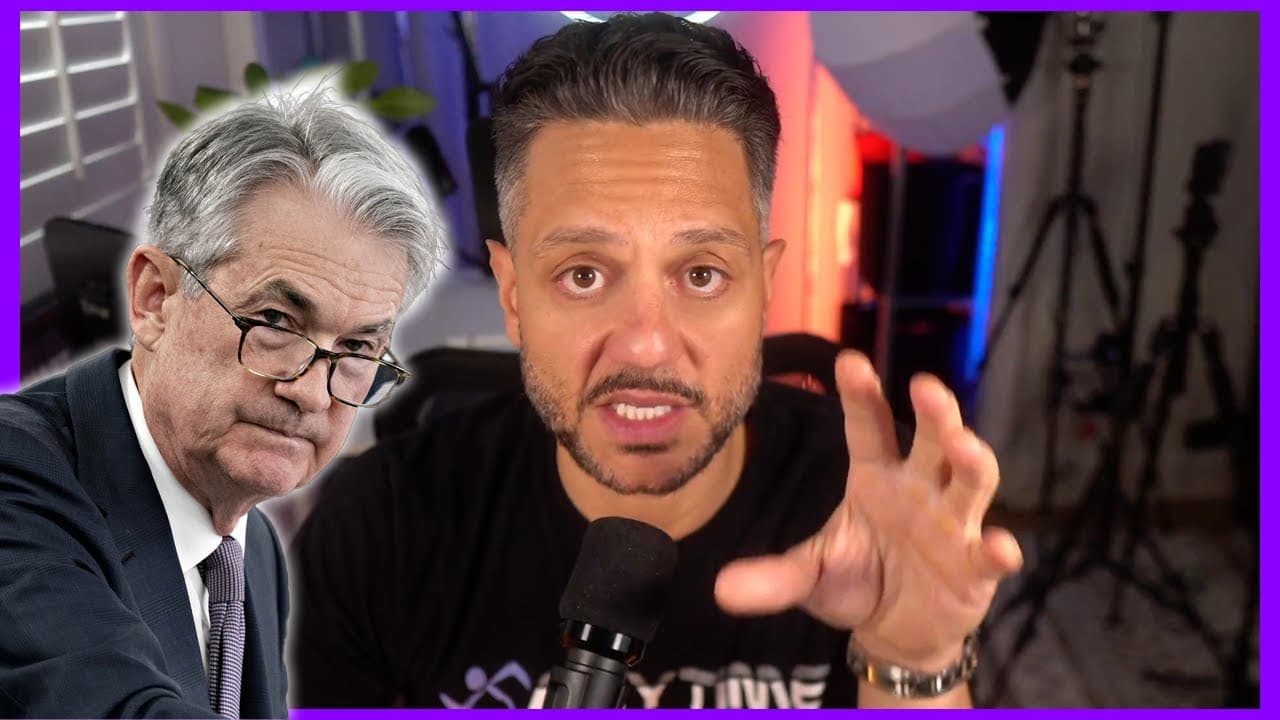
The presenter expects the Federal Reserve to skip a March rate cut and considers a 25-basis-point cut in May more likely. He believes stocks could rise modestly if Apple, Amazon, and Meta provide decent guidance, but plans to reduce recently purchased winners and increase exposure to bond ETFs as yields potentially decline.
Transcript
we just wrapped up the fomc meeting and Jerome Powell let the cat out of the bag as to what the FED is expected to do in March this is a huge deal if you are tracking the markets and you are interested in what happens to the markets as well as your portfolio I'm going to be telling you based on history at this juncture when we are when we have had ... Read More
Key Insights
- Powell’s stated base case was that the Federal Reserve would probably not have enough confidence to identify March as the appropriate time for a rate cut. The presenter interprets this as strong support for skipping a March reduction.
- A May rate cut is the presenter’s central expectation, with a 25-basis-point reduction considered more likely than a 50-basis-point move. His market outlook is therefore organized around the possibility that rates remain unchanged through March before declining in May.
- The 10-year yield is presented as a leading signal for Federal Reserve policy. The presenter points to patterns from 2000, 2007, and the period since 2018, arguing that the yield commonly turns lower before the federal funds rate does.
- The historical sequence described is the 10-year yield declining first, the Federal Reserve cutting rates second, and the stock market weakening afterward. The presenter says stocks can continue rising temporarily because lower rates initially provide support before economic weakness becomes more important.
- Corporate guidance from Apple, Amazon, and Meta is identified as the immediate test for the rally. Decent guidance could support modest gains toward the S&P 500’s psychological 5,000 level, while weak guidance could signal that the rally is approaching its end.
- Peak interest rates combined with stock-market highs are the presenter’s principal concern. He does not treat record market levels alone as a bearish signal, but argues that historically the combination of peak rates and elevated stocks has not favored sustained further gains.
- Recently purchased stocks with exceptional gains are candidates for sale in the presenter’s portfolio. Older holdings with unusually low cost bases may instead be retained, especially when he believes the market is unlikely to offer those entry prices again.
- Bond ETFs are a preferred destination for part of the portfolio rotation. The presenter began increasing exposure to TLT and TMF in November and expects these positions to continue benefiting over the longer term if yields move lower.
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: Why does the presenter expect the Fed to skip a March rate cut?
Jerome Powell said he did not think the committee would probably reach the required level of confidence by the March meeting to identify that month as the right time to cut rates. The presenter therefore treats a March reduction as unlikely and notes that expectations shifted toward the Federal Reserve leaving rates unchanged at that meeting.
Q: When does the presenter expect the Federal Reserve to cut rates?
The presenter expects the Federal Reserve to cut rates in May rather than March. He says expectations for May were close to complete confidence in a reduction, although traders differed over whether the move would be 25 or 50 basis points. His own view favors the smaller 25-basis-point cut as the more likely outcome.
Q: How does the 10-year yield signal future Federal Reserve policy?
The presenter argues that the 10-year yield tends to move before the Federal Reserve changes its policy rate. He cites patterns from 2000, 2007, and the period since 2018 in which the yield began falling before rate cuts. In his framework, a rolling-over 10-year yield suggests that policy rates may eventually follow lower.
Q: What is the expected sequence between bond yields, Fed cuts, and stocks?
The historical hierarchy described by the presenter begins with the 10-year yield turning lower. The Federal Reserve then reduces the federal funds rate, and the stock market may weaken afterward when the economic slowdown or recession behind the cuts becomes clearer. Stocks can still rise temporarily between the initial yield decline and the later market downturn.
Q: Could the S&P 500 continue rising before a May rate cut?
The presenter believes the S&P 500 could continue rising incrementally and potentially reach the psychological 5,000 level before May. That outlook depends heavily on corporate guidance, particularly from Apple, Amazon, and Meta. If those companies provide decent guidance, he expects the rally could continue slightly longer, rather than ending immediately after the Federal Reserve meeting.
Q: Why are Apple, Amazon, and Meta earnings important to the market outlook?
Apple, Amazon, and Meta are treated as crucial because their forward guidance could reveal whether major companies expect business conditions to remain supportive. The presenter emphasizes guidance rather than reported earnings. Decent outlooks could extend the rally toward May, while poor outlooks from these three large companies could signal that the S&P 500’s advance is nearing its end.
Q: Why is the presenter selling some stocks but keeping others?
The presenter distinguishes between recent purchases that have risen sharply and older positions acquired at very low cost bases. He is willing to sell recent winners after exceptional gains. For long-held shares whose entry prices may not return, he prefers retaining the positions and potentially selling calls against them instead of disposing of the underlying stocks.
Q: Why is the presenter increasing exposure to TLT and TMF?
The presenter expects yields to decline over the longer term and believes bond ETFs can rally under that scenario. He says he began increasing exposure to TLT and TMF in November, before bonds became a more obvious focus. These holdings form part of his planned rotation away from recently purchased stocks that have already appreciated substantially.
Summary & Key Takeaways
-
Jerome Powell said a March rate cut was probably not the committee’s base case, shifting expectations toward no March cut. The presenter instead expects action in May, most likely a 25-basis-point reduction, and argues that the declining 10-year yield may provide an early signal about the Federal Reserve’s eventual decision.
-
The presenter describes a historical sequence in which the 10-year yield turns lower first, the federal funds rate follows, and stocks weaken afterward as economic conditions deteriorate. Stocks can initially benefit from falling rates, however, so he believes the S&P 500 could still rise incrementally toward the psychological 5,000 level.
-
Portfolio positioning depends on purchase timing and cost basis. The presenter plans to offload some recently purchased stocks that appreciated sharply, while retaining older low-cost holdings and potentially selling calls against them. He is also rotating toward TLT and TMF because he expects bond ETFs to benefit if yields decline over time.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from The Traveling Trader 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator