Should I Pay Off My Mortgage Early or Invest in Stocks? Tax Expert Explains
TL;DR
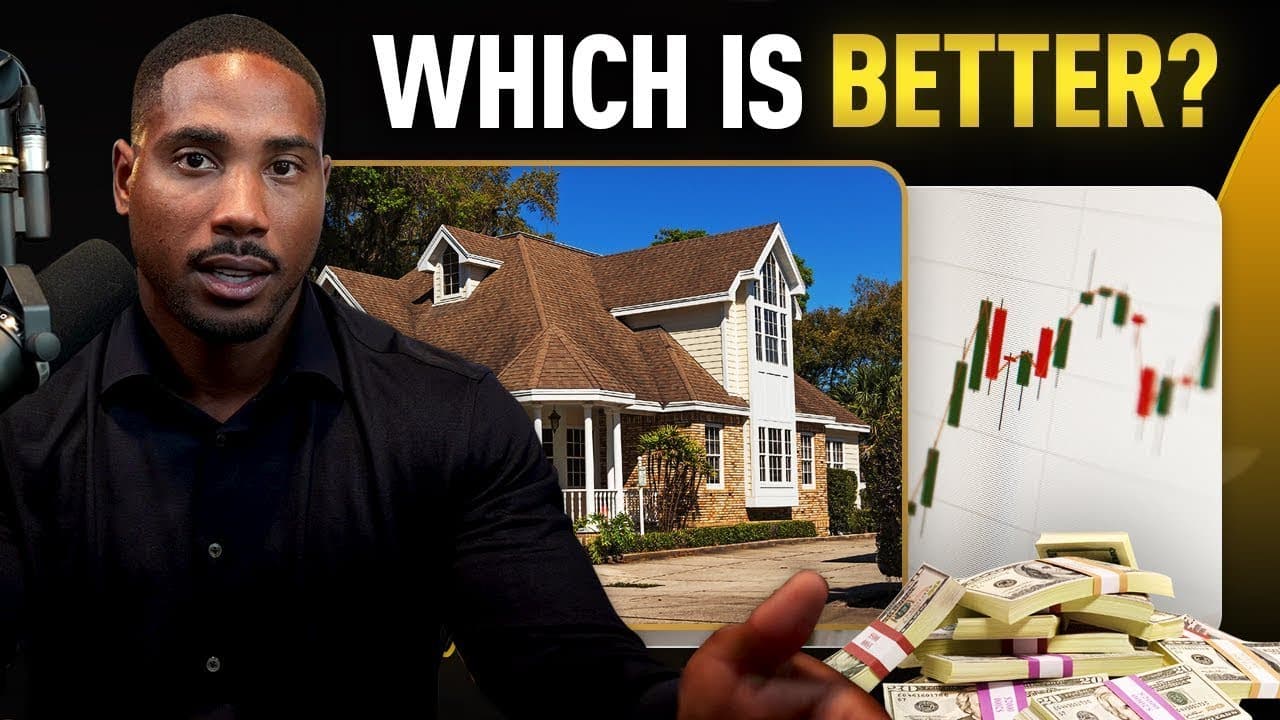
Whether you should pay off your mortgage early or invest in stocks depends mainly on your mortgage rate, expected after-tax investment return, risk tolerance, and need for peace of mind. Paying extra principal offers predictable interest savings, while stocks offer uncertain potential gains. Biweekly payments may shorten a typical 30-year mortgage by an average of 4 to 6 years. Read on to compare the strategies, risks, and tax considerations.
Transcript
should I pay off my mortgage early or should I invest in stocks every year millions of people have to make this decision and for many of these people it is one of the most important financial decisions they will ever make if you choose wrong it could potentially cause you to miss out of tens of hundreds of thousands of dollars that you would have o... Read More
Key Insights
- The best financial choice depends on the homeowner's mortgage rate, investing ability, tax situation, risk tolerance, and desire for peace of mind. Neither mortgage repayment nor stock investing is automatically superior for every person, so the comparison must reflect individual circumstances.
- Paying off a mortgage early creates a predictable benefit by reducing future interest expense and converting debt into home equity. It can also lower financial stress because required mortgage payments disappear after the loan is fully repaid, although property taxes remain payable.
- Stock investing offers potentially higher returns than early mortgage repayment, but those returns are not guaranteed. Individual-stock selection is especially risky, while an S&P 500 index fund spreads money across a collection representing 500 of America's largest companies by market capitalization.
- The mortgage interest rate is the central benchmark for comparing the two choices. With a 7.5% mortgage rate, investments must generate more than 7.5% after taxes to outperform early repayment, while a substantially lower mortgage rate makes investing comparatively more attractive.
- Biweekly mortgage payments can reduce principal faster and lower long-term interest costs when the lender permits them. The transcript states that this approach can shorten a typical 30-year mortgage by an average of 4 to 6 years, even without large additional monthly payments.
- Refinancing can change the mortgage-versus-investing calculation when interest rates fall. A borrower with a high mortgage rate may refinance into a lower-rate loan, reducing the interest burden and potentially making it more reasonable to direct extra cash toward stock investments.
- Market risk has different consequences at different life stages. People in their 20s and 30s may have decades to recover from a crash, while retirees and people nearing retirement may find a major portfolio decline more difficult to absorb.
- Retirement accounts can improve the tax treatment of stock investing. Traditional 401(k) and IRA contributions use pre-tax dollars and may lower taxable income, while Roth 401(k) and IRA contributions use after-tax dollars and can grow and be withdrawn tax-free.
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: How do I decide whether to pay off my mortgage early or invest in stocks?
Compare your mortgage interest rate with the investment return you could reasonably earn after taxes. Then consider your investing experience, risk tolerance, age, and desire for peace of mind. A high mortgage rate strengthens the case for repayment, while a low rate can make diversified stock investing more attractive.
Q: When does paying off a mortgage early make more sense?
Early repayment may make more sense when your mortgage rate is high, investing feels overwhelming, or you prefer predictable savings over uncertain gains. Additional principal payments reduce future interest and build home equity faster. After the mortgage is fully repaid, principal and interest payments disappear, although property taxes continue.
Q: When can investing be better than paying off a mortgage early?
Investing can produce a better financial result when your mortgage rate is low and your after-tax investment return exceeds that rate. Stocks offer potentially higher returns, but profits are not guaranteed and depend on investment skill, strategy, taxes, and market performance. Your ability to tolerate losses also matters.
Q: Why is the mortgage interest rate important in this decision?
Paying additional principal effectively saves interest at your mortgage rate, making that rate the benchmark for comparison. With a 7.5% mortgage rate, investments must earn more than 7.5% after taxes to outperform early repayment. A substantially lower rate makes investing comparatively more attractive.
Q: Are index funds less risky than individual stocks?
Index funds reduce the risk of relying on a single company because they hold a collection of stocks. The transcript uses an S&P 500 index fund as an example; the index represents 500 of America’s largest companies by market capitalization. It states that the S&P 500 returns an average of around 10% annually, though investment profits are not guaranteed.
Q: Can biweekly payments help pay off a mortgage faster?
Biweekly payments can reduce principal faster and lower long-term interest costs when the lender permits them. According to the transcript, this approach can shorten a typical 30-year mortgage by an average of 4 to 6 years, even without making large additional monthly payments. Ask your lender whether biweekly payments are allowed.
Q: How does refinancing affect whether I should invest or repay my mortgage?
Refinancing from a high mortgage rate to a lower one reduces the interest burden and changes the comparison with investing. Because the new rate is lower, investments need a lower return to outperform accelerated mortgage repayment. This may make directing extra money toward stocks more reasonable.
Q: What tax benefits can retirement accounts provide when investing?
Traditional 401(k) and IRA contributions use pre-tax dollars, may reduce taxable income, and grow tax-deferred. Roth 401(k) and IRA contributions use after-tax dollars and can grow and be withdrawn tax-free. These tax benefits can affect the comparison between investing and accelerating mortgage payments.
Summary & Key Takeaways
-
The decision depends on personal circumstances rather than a universal rule. Early mortgage payments reduce debt, save interest, and build home equity faster. Stock investing can produce greater returns, but results are uncertain and depend on investment skill, strategy, taxes, market performance, and the investor's ability to tolerate losses.
-
Mortgage interest rates provide a useful comparison point. Investments must earn more after taxes than the mortgage rate to produce a better financial result. High-rate borrowers may favor repayment, low-rate borrowers may favor investing, and borrowers with rates between 4% and 6% may benefit from using payoff calculators.
-
Peace of mind, age, and tax strategy also matter. A paid-off mortgage removes required principal and interest payments, although property taxes continue. Investors nearing retirement may find market crashes harder to tolerate. Traditional and Roth retirement accounts can add tax benefits when stocks are chosen instead of accelerated mortgage repayment.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from Karlton Dennis 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator