Why Are AI, SaaS, and Bitcoin Markets Volatile?
TL;DR
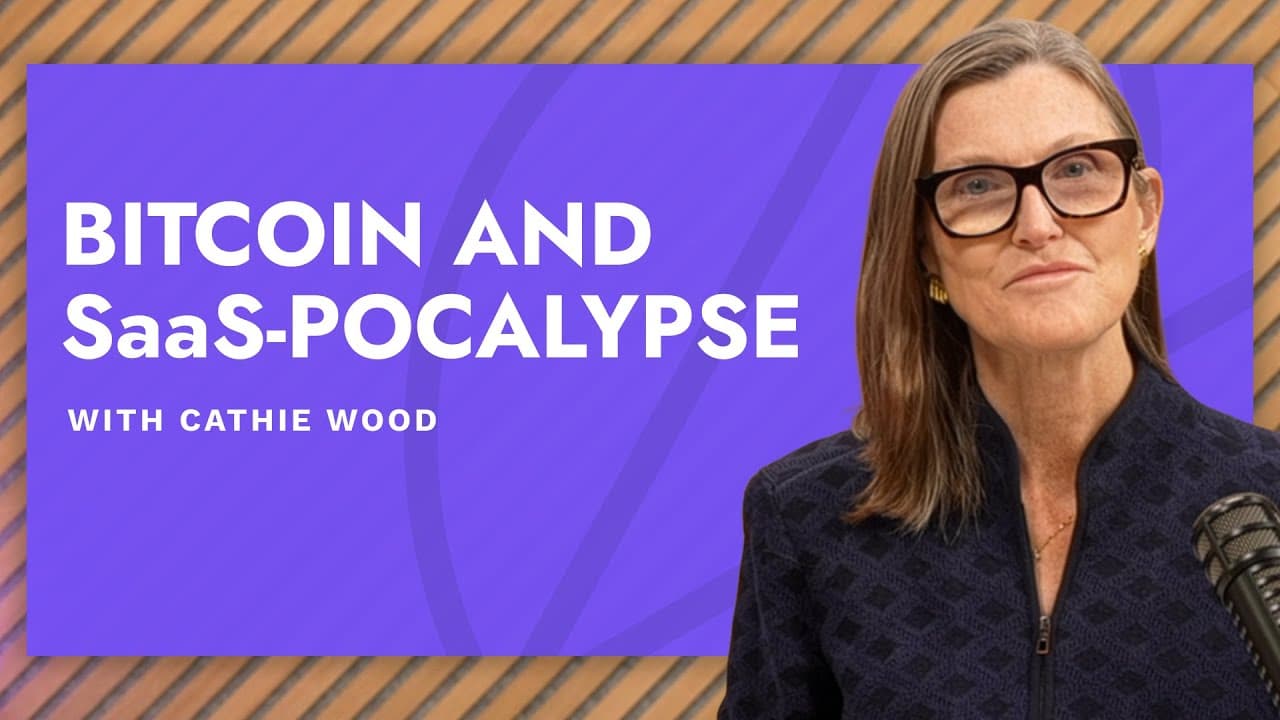
AI investment appears driven by active demand for computing capacity, but the rapid shift toward platforms and away from traditional software is unsettling investors. Bitcoin volatility, changing liquidity expectations, and unusually aggressive hyperscaler spending are adding uncertainty, while ARK views technological disruption and shareholder turnover as more informative than simple bubble comparisons.
Transcript
Greetings, everyone. This is Cathie Wood, CEO and CIO of Ark Invest. It is employment Friday, uh, but there's no employment report. Uh, we will have that next week. But given all of the fireworks, uh, in the market and all the drama recently, uh, uh, I felt it was important, uh, to, to do In The Know, or at least on the-- In The Know: Part One toda... Read More
Key Insights
- Artificial intelligence is shifting economic value across the technology stack. ARK expects infrastructure, platforms, and applications to grow, but believes platform-as-a-service companies are gaining incremental share while traditional software-as-a-service providers face a faster and more severe competitive challenge than previously anticipated.
- Palantir is presented as an important platform winner in the AI revolution. Its reported growth in the United States commercial business exceeded ARK's earlier assumptions, suggesting that demand for effective AI platforms may be accelerating beyond forecasts that had already appeared ambitious.
- Traditional SaaS is becoming a victim of the AI transition. ARK expects some providers to survive and consolidate their markets, but its earlier forecast underestimated both the scale and speed of the share movement away from application software and toward AI-centered platforms.
- Hyperscaler capital spending is creating shareholder turnover. Many benchmark-sensitive investors are accustomed to technology companies holding large cash balances and producing substantial free cash flow, so rapidly expanding investment budgets and new debt issuance challenge the financial profile they previously expected.
- Benchmark sensitivity shapes how traditional portfolio managers control risk. A manager can express a negative view merely by holding slightly less of a company than its index weight, because performance is judged relative to peers and benchmarks rather than solely by long-term conviction.
- Data center investment accelerated after the emergence of ChatGPT. ARK views current spending announcements as broadly consistent with its forecast for a sustained expansion in data center systems, while noting that widely cited capital expenditure totals include more than data center equipment alone.
- Semiconductor market share may shift from GPUs toward ASICs. ARK expects strong overall appetite for chips but sees the possibility that suppliers associated with specialized chips gain share from major GPU providers as artificial intelligence infrastructure evolves.
- AI infrastructure differs from the unused fiber associated with the technology and telecommunications bubble. Data centers are requesting more computing capacity, and installed GPUs are actively used, although Cathie Wood still expects that shortages could eventually produce an inventory glut in the chip market.
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: Why are investors worried that artificial intelligence is a bubble?
Investors see technology-sector capital spending approaching levels associated with an earlier market bubble, while hyperscalers are rapidly expanding budgets for data centers, chips, and related infrastructure. The comparison creates anxiety, especially among experienced investors who remember the technology and telecommunications collapse. ARK argues that current computing equipment is meeting active demand, unlike fiber capacity that remained unused for a long period.
Q: How is artificial intelligence affecting software-as-a-service companies?
Artificial intelligence is moving growth and competitive advantage away from parts of the traditional application layer and toward platform providers. ARK believes SaaS will lose more share, and lose it sooner, than its earlier forecasts suggested. Some SaaS providers may survive by consolidating their markets, but the group as a whole faces pressure from a technological transition that is progressing unusually quickly.
Q: Why does ARK view Palantir as an important AI platform company?
ARK identifies Palantir as a major beneficiary of the shift toward platform as a service. The company reported exceptionally rapid growth in its United States commercial business, surpassing what ARK had expected from public software companies. That performance suggests organizations are adopting AI platforms quickly and raises the possibility that ARK's own long-term growth assumption for Palantir may be too conservative.
Q: Why are hyperscaler spending plans unsettling shareholders?
Many large technology shareholders became accustomed to companies maintaining substantial cash reserves and generating significant free cash flow. Large increases in capital spending, combined in some cases with debt issuance, represent a major change in financial behavior. Benchmark-sensitive managers may therefore reduce relative exposure even when the spending could be strategically sound, producing turnover in the shareholder base and additional market volatility.
Q: How does benchmark sensitivity influence technology investing?
Benchmark-sensitive portfolio managers evaluate holdings relative to an index and to competing managers. A manager can effectively bet against a company by owning a smaller position than its benchmark weight, even while still holding the stock. This structure discourages large deviations from major index companies and helps explain why shareholder changes may remain limited despite concerns about rapidly rising capital expenditure.
Q: Why does ARK think current AI infrastructure spending may be justified?
ARK believes hyperscalers are responding to strong demand for computing capacity rather than building equipment with no immediate use. GPUs are arriving in data centers that continue to request more chips and capacity. This contrasts with the earlier telecommunications cycle, when substantial fiber infrastructure remained inactive. ARK therefore sees meaningful demand behind the spending, while still acknowledging that overinvestment can eventually create excess inventory.
Q: How could the AI semiconductor market change?
ARK expects demand to remain strong across the chip market, but it also anticipates a change in market share between processor types. GPUs may surrender some share to ASICs as artificial intelligence systems evolve and specialized computing becomes more important. This could shift relative opportunity among chip suppliers without implying that overall demand for processors will disappear.
Q: What risks remain if demand for AI chips stays strong?
Persistent shortages can encourage suppliers and customers to order aggressively, increasing the possibility of excess inventory later. Cathie Wood expects a semiconductor glut at some point because shortages often lead to overbuilding, but she does not believe it is imminent. Demand for chips and power remains strong, and data centers continue seeking more capacity, making the timing of any eventual correction uncertain.
Summary & Key Takeaways
-
ARK identifies AI enthusiasm, cryptocurrency weakness, and shifting macroeconomic signals as the main narratives unsettling markets. Cathie Wood argues that investors should distinguish structural technological change from temporary market fear, particularly as artificial intelligence redirects revenue growth, capital investment, and competitive advantage across infrastructure, platforms, applications, and semiconductor providers.
-
The AI software stack is changing faster than ARK previously expected. Platform providers such as Palantir are gaining momentum, while traditional software-as-a-service businesses face pressure from artificial intelligence. Some SaaS companies may survive by consolidating their markets, but the application layer appears likely to lose more share and lose it sooner than anticipated.
-
Hyperscalers are sharply increasing capital spending to satisfy demand for data centers, chips, and power. That shift is uncomfortable for shareholders accustomed to large cash reserves and strong free cash flow. ARK believes much of the spending is strategically justified because installed processors are being used, although eventual semiconductor oversupply remains a recognized risk.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from ARK Invest 📚


Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator