What is P/E Ratio? [and Why it SUCKS!]
TL;DR
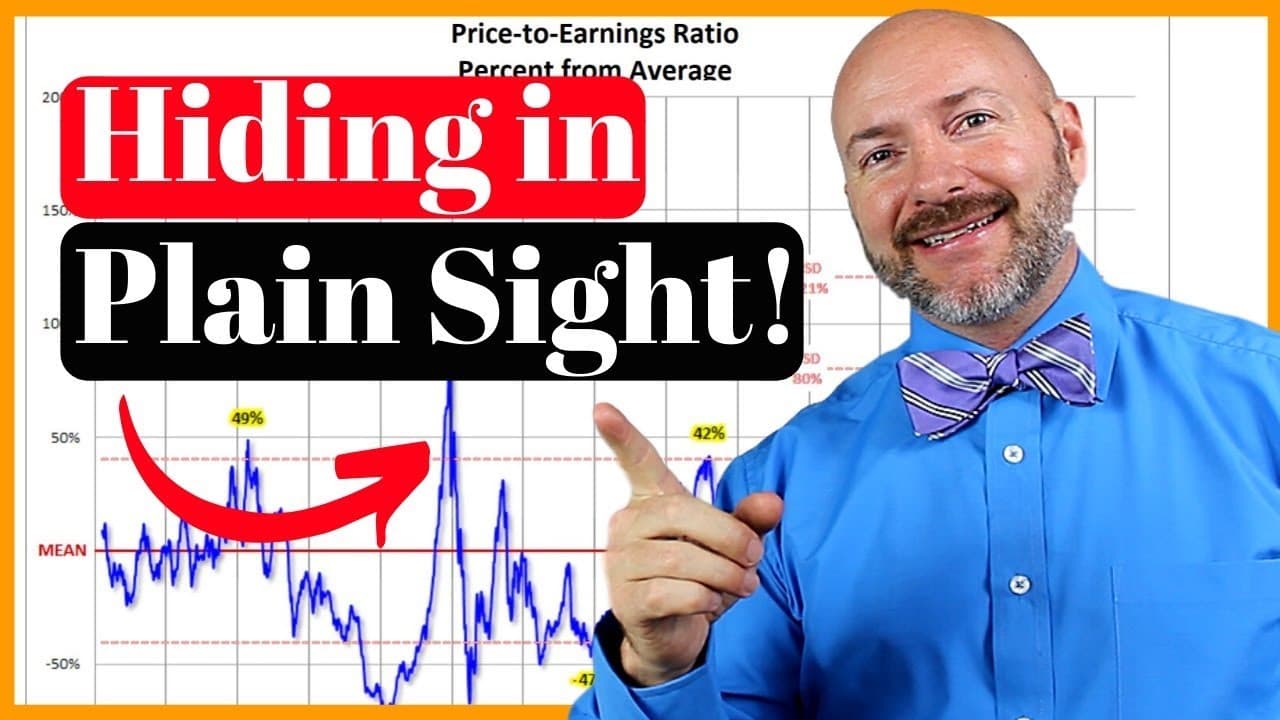
The P/E ratio divides a stock’s price by its earnings, but it cannot reveal a stock’s true value when used alone. In the Apple example, a $242.46 share price divided by $11.73 in annual earnings produces a P/E ratio of 20.6. The distinction between trailing and forward earnings, plus comparisons with relevant companies and alternative ratios, explains why investors should read on.
Transcript
What is the PE ratio and how does it lose investors money? Why is the most popular measure in stock investing almost completely useless? Beat debt. Make money. Make your money work for you. Creating the financial future you deserve. Let's Talk Money. In this video, I’ll show you why the PE ratio is a sewer of information, how company management tri... Read More
Key Insights
- Simplicity creates false confidence: The P/E ratio compresses a company and its stock into one easily understood number. That convenience can fool investors into thinking they know the stock’s true value. Hogue’s objection is not merely that people calculate it incorrectly, but that the measure is too simplistic to support a complete valuation by itself.
- Price and earnings form P/E: The calculation uses a share’s market price as the numerator and the company’s earnings or profits as the denominator. The earnings figure usually covers the previous year. Its widespread appeal comes from a formula that investors can calculate quickly using figures available through an investing platform or the company’s financial statements.
- Quarterly reports supply earnings: Every company with publicly traded shares releases an earnings report every three months to describe its finances and performance during the quarter. Investors pay particular attention to the earnings figure because shares represent ownership stakes in company profits. This attention helps explain why earnings became the foundation of the market’s most popular valuation ratio.
- Apple illustrates the arithmetic: Apple’s four cited quarterly earnings figures were $2.18, $2.46, $4.18 and $2.91 per share. Their total was $11.73 for the year. Dividing the recorded share price of $242.46 by those annual earnings yielded a P/E of 20.6, commonly described as approximately 20 times annual profits.
- The multiple reflects willingness: A P/E of about 20 does not mean investors receive an immediate 20-fold return. In Hogue’s explanation, it means investors are currently willing to pay about 20 times Apple’s annual profits for one share. That share is an ownership interest in the company’s future profits, which makes expectations important to the price.
- Trailing P/E uses actual results: The trailing price-to-earnings ratio, identified as the version investors see most often, divides the current share price by earnings from the last year. Its denominator comes from reported performance rather than a forecast. That distinction matters because it separates documented profits from assumptions about what the company might earn next.
- Forward P/E depends on estimates: Forward price-to-earnings replaces the previous year’s actual profits with analysts’ expected profits for the coming year. Hogue emphasizes that these estimates may not be very good. Investors therefore need to recognize when an apparently attractive valuation is based on optimistic expectations rather than profits the company has already reported.
- Forecasts can lower the multiple: Wall Street’s earnings expectations are described as almost always higher than a company’s past performance. Even when analysts expect a decrease, the transcript says it is rarely more than one or two percent. Higher expected earnings create a lower forward P/E, which can make the same current share price look cheaper.
- A lower forward figure warns: Shares trading at 20 times last year’s earnings might be described as trading at about 15 times expected earnings. The price has not become lower in that comparison. Instead, optimistic projected profits enlarge the denominator, producing a more appealing ratio and potentially making shares that look expensive on trailing earnings appear reasonable.
- Relative does the real work: Saying Apple trades at 20 times earnings does not independently establish whether the stock is cheap or expensive. The ratio becomes interpretable only through comparison. Hogue highlights the word “relatively” because a conclusion such as Apple being less expensive than Microsoft depends entirely on the chosen comparison and does not establish absolute value.
- Relevant comparisons improve context: The existing analysis calls for comparing a stock with its own historical average and with similar companies in the same industry. The example contrasts Apple’s P/E of 20 with Microsoft’s 27, supporting only the conclusion that Apple is relatively less expensive by that measure. A standalone multiple cannot answer whether either stock is attractively valued.
- Three alternatives broaden valuation: Hogue identifies price-to-sales, price-to-book and price-to-cash-flows as alternatives to relying solely on P/E. These measures respectively examine company revenue, assets and debts, and cash flow from operations. The broader lesson is to combine multiple measures with historical and relevant company comparisons instead of allowing one earnings-based ratio to determine an investment judgment.
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: What is the P/E ratio, and why does it suck as a stock valuation measure?
The P/E ratio is a stock’s price divided by the company’s earnings or profits, usually measured over the previous year. It is easy to calculate and understand, but Hogue considers it overly simplistic and almost worthless when used alone. The ratio can create false confidence because investors may mistake a convenient comparison for knowledge of a stock’s true value. It also becomes especially misleading when optimistic forecasts or irrelevant company comparisons make shares appear cheaper than they are on reported earnings.
Q: How do you calculate the P/E ratio using Apple’s figures?
First, add Apple’s four cited quarterly earnings-per-share figures: $2.18, $2.46, $4.18 and $2.91. They total $11.73 in earnings per share for the previous year. Divide the recorded share price of $242.46 by $11.73 to obtain a P/E ratio of 20.6. This indicates that investors were willing to pay approximately 20 times Apple’s annual profits for a share representing ownership in future profits.
Q: What is the difference between trailing and forward P/E ratios?
Trailing P/E divides the current stock price by the company’s actual earnings from the previous year. Forward P/E instead divides the price by the profits analysts expect the company to make during the coming year. The distinction matters because one denominator reflects reported performance, while the other relies on an estimate that may prove inaccurate. Hogue therefore warns investors to be careful when analysts emphasize forward P/E.
Q: Why is the forward P/E ratio usually lower than the trailing P/E ratio?
The transcript says Wall Street’s expected earnings are almost always higher than a company’s past performance. A larger expected earnings figure lowers the result when the same current share price is divided by it. Consequently, shares trading at 20 times actual earnings could be presented as trading at about 15 times expected earnings. This lower figure can make an expensive stock look more reasonable without changing its current price.
Q: Does a P/E ratio of 20 mean a stock is cheap or expensive?
No, a P/E ratio of 20 does not independently show whether a stock is cheap or expensive. Hogue says a P/E ratio is good or bad only when compared with another relevant ratio. Investors should consider the stock’s historical average and similar companies in the same industry to establish context. The need for comparison is why he stresses that any conclusion based on P/E is relative.
Q: Why can Apple look cheaper than Microsoft based on P/E?
The example places Apple at approximately 20 times earnings and Microsoft at 27 times earnings. On that single comparison, Apple is relatively less expensive because investors pay a lower multiple of earnings for its shares. The conclusion is limited to relative P/E values and does not establish Apple’s true or absolute value. Hogue uses this distinction to show why the word “relatively” is crucial in valuation discussions.
Q: What alternatives to the P/E ratio does Joseph Hogue recommend?
Hogue identifies three alternatives: the price-to-sales, price-to-book and price-to-cash-flows ratios. Price-to-sales evaluates value using company revenue, while price-to-book focuses on assets and debts. Price-to-cash-flows examines cash flow from operations. These measures broaden the analysis because they assess company value through information other than the earnings figure used in P/E.
Q: How should investors use P/E without being misled?
Investors should never trust the P/E ratio alone as a statement of what a stock is worth. They should first determine whether the quoted figure is trailing P/E based on actual earnings or forward P/E based on projected profits. They should then compare the ratio with the stock’s historical average and similar companies in the same industry. Finally, they can add price-to-sales, price-to-book and price-to-cash-flows measures to create a more comprehensive assessment.
Summary & Key Takeaways
-
Introducing the P/E problem: Joseph Hogue of the Let’s Talk Money channel calls the price-to-earnings ratio overly simplistic and almost worthless when treated as a complete valuation. Although hedge fund managers, television analysts and the channel itself use it, the ratio can fool investors into believing they know what a stock is worth. Hogue argues that its simplicity makes it an effective media sound bite that entertains investors, encourages trading and can contribute to losing money.
-
Calculating the basic ratio: The P/E ratio is a stock’s price divided by the company’s earnings or profits, usually from the previous year. Companies with publicly traded shares release an earnings report every three months covering their finances and quarterly performance. Because a share represents an ownership stake in company profits, investors focus heavily on earnings. The calculation is popular because it is easy to perform, easy to understand and produces a convenient point of comparison between stocks.
-
Working through Apple’s figures: Apple reported quarterly earnings per share of $2.18, preceded by $2.46, $4.18 and $2.91. Together, those figures produced $11.73 in earnings per share over the last year. With Apple shares trading at $242.46 when Hogue recorded the discussion, dividing the share price by annual earnings produced a P/E ratio of 20.6. That result means investors were willing to pay approximately 20 times Apple’s annual profits for an ownership share in its future profits.
-
Separating trailing from forward: Trailing P/E divides the current price by actual earnings from the last year, while forward P/E divides it by the profits analysts expect during the coming year. Hogue warns that Wall Street earnings expectations are almost always higher than past performance, making the forward ratio generally lower. A stock trading at 20 times past earnings might therefore be presented as trading at only about 15 times expected earnings, making expensive shares appear more reasonable.
-
Treating valuation as relative: A P/E ratio is not inherently good, bad, cheap or expensive. It gains meaning only when compared with another relevant ratio, such as the stock’s historical average or ratios for similar companies in the same industry. Apple at 20 times earnings may look relatively less expensive than Microsoft at 27 times, but the word “relatively” is essential. Hogue recommends never trusting P/E alone and identifies price-to-sales, price-to-book and price-to-cash-flows as three alternative valuation measures.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from Let's Talk Money! with Joseph Hogue, CFA 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator