How Does David Friedberg Identify Power Law Winners in Investing?
TL;DR
Investors identify power law winners by seeking the few companies whose superior technology, business engines, or network effects let them compound faster and capture an outsized share of the market. David Friedberg argues that simply buying a venture index misses this return profile; examples include Palantir adding about $420 billion in equity market value during its first five years as a public company. Read on for the fund, IPO, and compounding evidence behind his argument.
Transcript
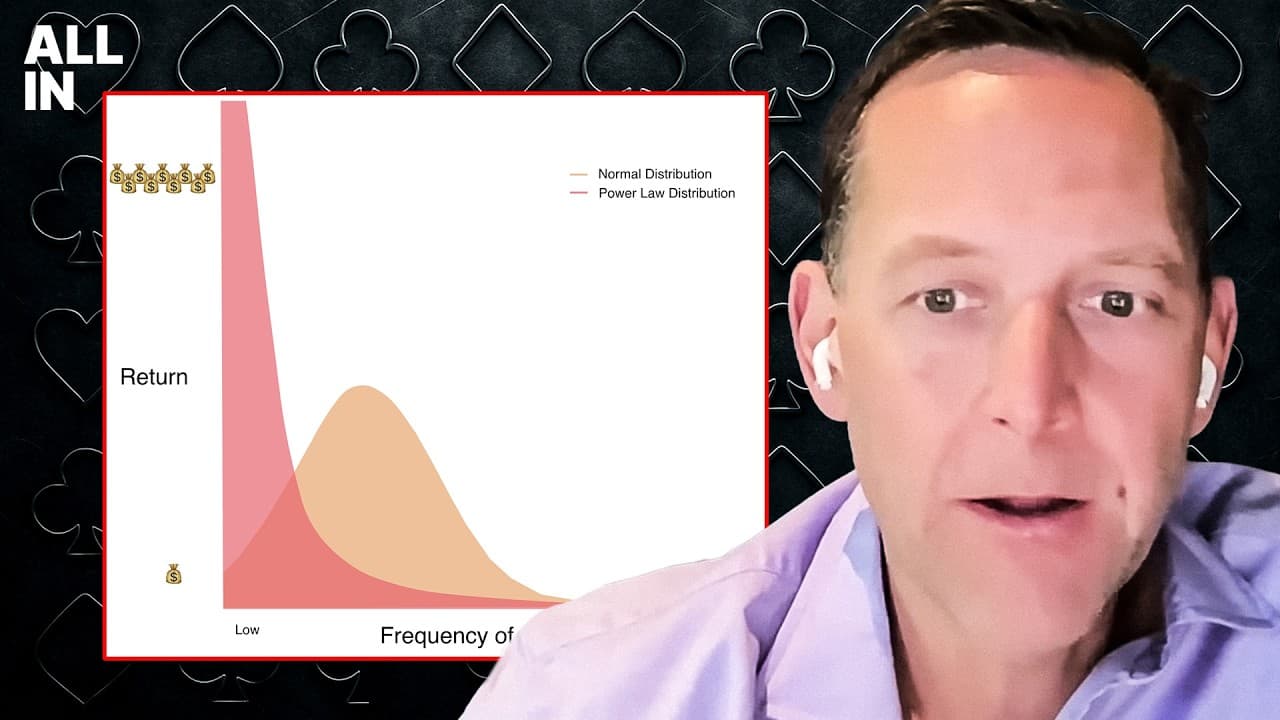
I pulled some data together, Nick, if you could pull up the basics. I know we talk about this a lot, but I thought it would be good to show the difference between kind of a normal distribution and a power law distribution. like venture returns or I don't like to call it venture returns but I do think the returns generally in free markets create val... Read More
Key Insights
- The power law distribution means a few investments account for most returns.
- Compounding is a powerful force in market value accumulation.
- Venture investing focuses on finding the few big winners, not indexing.
- Smaller funds often perform better by capturing winners early.
- Public companies can continue to accrue significant value post-IPO.
- Investors should leverage their knowledge of private companies when they go public.
- The venture industry is transitioning, resembling more public-private investing.
- Consistency in generating power law returns across funds is challenging.
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: What is a power law distribution in investing?
A power law distribution means that a few investments account for the vast majority of capital appreciation and value creation. David Friedberg says this pattern appears broadly in free markets and specifically in technology venture investing.
Q: How can investors identify power law winners?
Friedberg says investors should look for companies with a better technology engine, a better business engine, or a strong network effect. These advantages can create a runaway flywheel in which gaining market share helps the company gain even more market share until competitors cannot catch up.
Q: Why does compounding create outsized investment winners?
A superior company can compound its advantages and accumulate an increasing share of its market over time. As that share grows, the company can move even faster, producing an outsized concentration of value in a small number of winners.
Q: Why does David Friedberg argue against buying the venture index?
He argues that the investor's job is to find the power law winners, not buy the venture index. In his view, broad exposure includes too many weak investments and dilutes the impact of the small number of companies responsible for most returns.
Q: Why might smaller venture funds outperform larger funds?
The discussion says smaller funds are less diversified, making them more likely to capture meaningful exposure to individual winners. They may also invest earlier at lower valuations and avoid having their winners diluted by index-like diversification.
Q: What did the venture-fund example show about flat or down rounds?
At an LP conference, one large venture fund reported that 45% of its capital went into flat or down rounds across 13 funds, producing a negative net return on that allocation. The fund indicated that avoiding those investments would have doubled its overall IRR.
Q: How did the top 10 Nasdaq companies compare with the broader Nasdaq?
An analysis shared in 2023 showed that holding only the top 10 Nasdaq companies produced a 24x multiple over 24 years. Over a 10-year period, owning those top 10 companies produced a 9x multiple, supporting the argument that leading companies drive disproportionate returns.
Q: Do power law returns continue after a company goes public?
Yes, the examples presented show substantial value creation after IPO. Palantir went public after 17 years at a $16 billion market capitalization and reached $436 billion five years later, while Uber rose from $75 billion at its public debut to $190 billion six years later.
Summary & Key Takeaways
-
Investing success often follows a power law distribution, where a few investments generate most of the returns. This means that investors should focus on finding these 'power law winners' rather than diversifying across many investments. This approach applies both in private venture investing and the public markets, where companies continue to accumulate value post-IPO.
-
Smaller venture funds tend to perform better as they capture winners early and avoid dilution by indexing. Public companies often see significant value appreciation after going public, making them attractive for long-term investment. Understanding the power law and its implications can guide better investment decisions.
-
The venture industry is undergoing a transition towards a model that blends private and public investing. While finding power law winners is key, maintaining consistent success across multiple funds is challenging. Investors can benefit from leveraging their insights from private investments when these companies enter the public market.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from All-In Podcast 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator