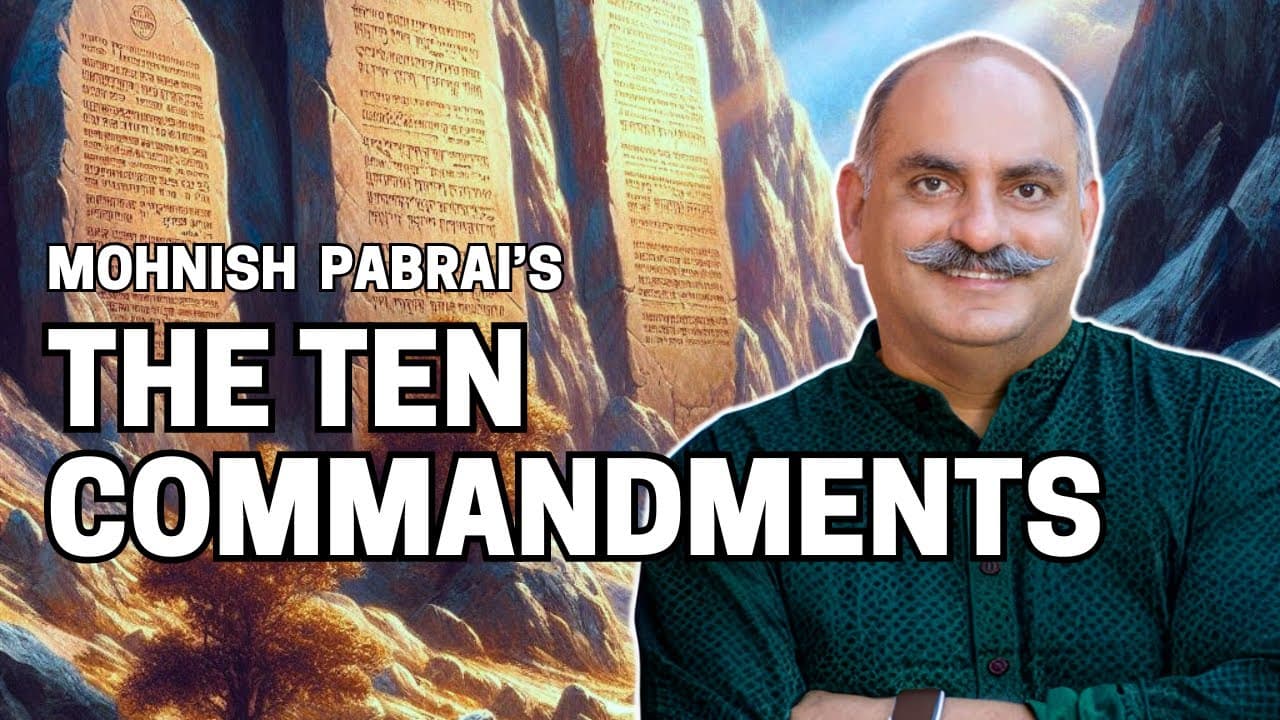
What Are Mohnish Pabrai’s 10 Commandments Investment Strategy Rules?
TL;DR
Mohnish Pabrai’s investment strategy emphasizes fair manager fees, independent analysis, humility about failed picks, simple valuation, resilience, and intense focus. His examples include Buffett’s 0-6-25 partnership structure, an expectation that at least four of ten stock picks may disappoint, and the search for a hidden PE of 1. Read on to understand how these commandments translate into practical investment decisions.
Transcript
A few thousand years ago, Moses went up to the top of Mount Sinai and came back with God’s 10 commandments that were inscribed in a stone tablet So that’s the story I know, that’s probably the story you know but according to Mohnish Pabrai when Moses was coming down the hill, he dropped the tablet which shattered it and the real commandments were l... Read More
Key Insights
- Fair investment fees are based on alignment rather than automatic extraction. Pabrai argues that managers should not exploit clients by taking fixed fees regardless of results and then adding performance charges, while investors should examine the complete fee structure of every basic or complex financial product.
- Investing is an individual pursuit because no two people have identical circles of competence. Research or idea lists can provide useful starting points, but each investor should investigate independently, narrow the candidates, and construct a thesis consistent with personal knowledge, philosophy, and judgment.
- Market disagreement is necessary for a trade to occur because buyers and sellers hold different expectations about price direction. Investors therefore gain little from attacking opposing views and may instead benefit when disagreement creates an opportunity to buy more cheaply or sell at a higher price.
- Stock selection is an inexact science with a high error rate because many factors can move in different directions. Pabrai suggests that at least four stocks in a group of ten may behave unexpectedly, so humility is necessary even when an investor has unusually strong conviction.
- A few major winners can offset numerous failed selections under the numerical scenario presented. If three of ten holdings become at least 10-baggers over ten years while the remaining seven fall to zero, the portfolio can still produce a 20% compound annual growth rate.
- A hidden PE of 1 is a company whose current valuation appears higher but could become extremely cheap relative to future earnings. The search focuses on credible profit expansion, not mechanically screening for reported PE ratios near 1 that may reflect exceptional income, liquidation, or unusable accounting results.
- Simple investment analysis is preferable when the essential economics can be estimated mentally. If profits or free cash flows grow around 10% while the investor expects a 20% long-term share-price return, the mismatch can be recognized without a detailed discounted cash flow spreadsheet.
- A psychological rope is a source of hope, resilience, or resourcefulness that helps an investor endure severe adversity. Market downturns and poor performance can test resolve, but attention to future potential, positive outcomes, and creative solutions can support persistence and eventual recovery.
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: What are the main ideas in Mohnish Pabrai’s 10 Commandments investment strategy?
The commandments emphasize fair investment-management fees, independent research, acceptance of stock-picking errors, and simple valuation analysis. They also encourage investors to seek a hidden PE of 1, maintain a psychological rope during severe setbacks, and develop Arjuna-like focus on the essential investment target.
Q: How should investment managers structure fees fairly?
Managers should avoid extracting fixed fees regardless of results and then adding performance charges. Buffett’s former 0-6-25 partnership structure charged nothing when performance was below 6%; above 6%, he received 25% of the excess profit. The principle is to align the manager’s compensation with useful results for clients.
Q: Why does Pabrai describe investing as an individual pursuit?
No two people have identical circles of competence, interpretations, or investment theses. Research and idea lists can offer starting points, but each investor should investigate independently and select opportunities that fit their own knowledge, philosophy, and judgment.
Q: How should investors respond to opposing investment opinions?
Investors should treat disagreement as a normal part of markets rather than a personal attack. A trade requires different expectations between the buyer and seller, and disagreement can create an opportunity to buy more cheaply or sell at a higher price. Disciplined decisions matter more than defending one’s ego.
Q: Why should investors expect some stock selections to fail?
Investment analysis is an inexact science involving many factors that can move in different directions. Pabrai says that at least four stocks in a group of ten may not behave as expected. Investors should therefore remain humble even about their highest-conviction ideas.
Q: Can a portfolio succeed when most stock picks fail?
A few exceptional winners can outweigh numerous failures in the scenario presented. If three of ten holdings become at least 10-baggers over ten years while the remaining seven fall to zero, the portfolio can still produce a 20% compound annual growth rate.
Q: What does a hidden PE of 1 mean in Pabrai’s strategy?
A hidden PE of 1 describes a business whose future annual earnings could grow until they approximately equal its current market capitalization. Investors should assess credible profit expansion rather than mechanically buying stocks with reported PE ratios near 1, since those earnings may reflect exceptional income, liquidation, or unusable accounting results.
Q: Why does Pabrai favor simple investment analysis over complex spreadsheets?
The essential economics of an attractive investment should be simple enough to estimate mentally. If profits or free cash flows grow around 10% while the investor expects a 20% long-term share-price return, the mismatch can be recognized without a detailed discounted cash flow spreadsheet. An opportunity that needs a complicated model to appear attractive may be too convoluted.
Summary & Key Takeaways
-
Pabrai’s framework begins with alignment between investment managers and clients. Managers should avoid exploiting investors through excessive fixed and performance fees. The discussion contrasts common fee structures with Buffett’s former 0-6-25 partnership model and encourages investors to understand charges across mutual funds, insurance products, annuities, PMS offerings, smallcases, hedge funds, and private equity funds.
-
Investing is presented as an individual pursuit because people have different circles of competence and must ultimately form their own theses. Disagreement should be welcomed rather than treated as a personal conflict. Investors should also accept frequent errors, since even high-conviction ideas can disappoint and a few exceptionally successful holdings may drive overall portfolio returns.
-
The preferred analytical process is simple enough to perform mentally. Investors should search for companies whose future profit growth could reduce an apparently ordinary valuation toward a hidden PE of 1. They should reject opportunities dependent on complicated models, preserve a psychological rope during severe downturns, and develop Arjuna-like focus on the essential investment target.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from Shankar Nath 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator