Is XRP a Good Investment Compared With Bitcoin?
TL;DR
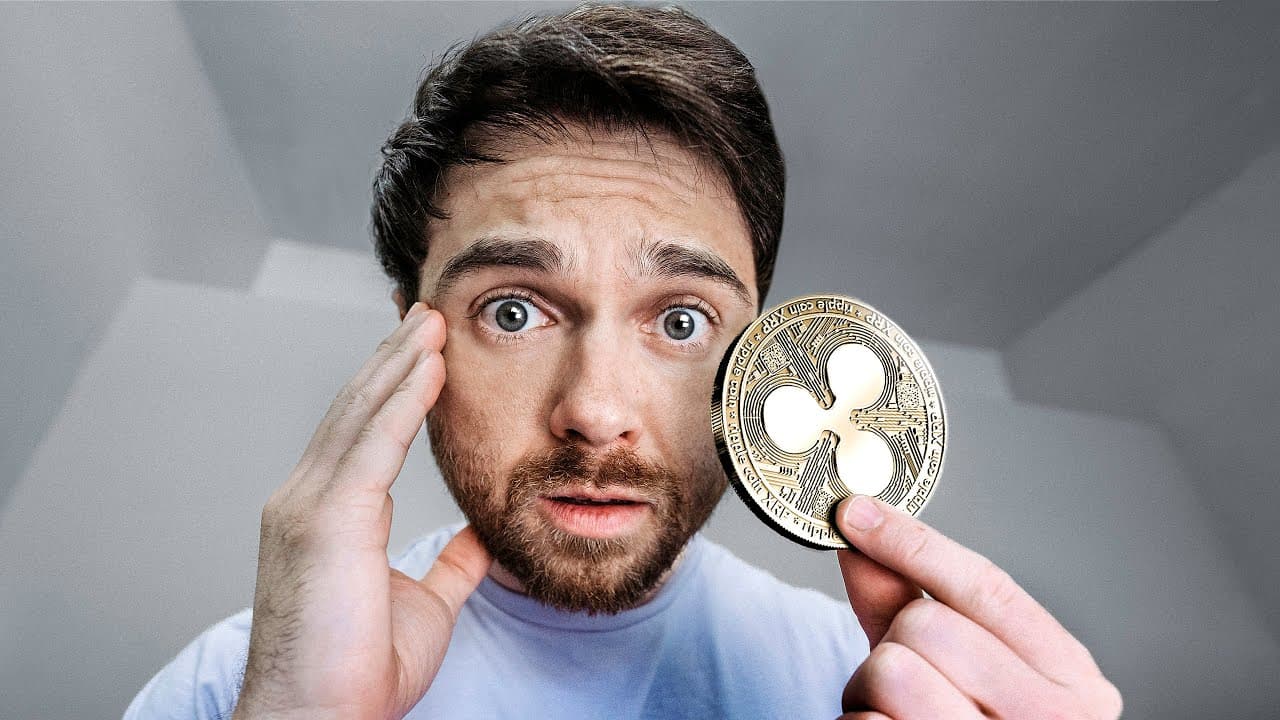
XRP provides fast, inexpensive settlement, but using Ripple’s banking technology does not require banks to use the token itself. The central concern is that Ripple is a company and XRP may face classification as a security, which could impose stricter regulation and unsettle the broader crypto market. The creator therefore views XRP as a centralized bet on bank adoption rather than a decentralized alternative to finance.
Transcript
Man, these cryptocurrencies are out of control. Listen to this. 20 trillion coins in circulation, with the top 1% of wallet addresses owning 30.4% of the entire supply, with roughly a third, or 35%, being printed in just the last 10 months alone, and there's an unlimited amount of coins that can exist. If that doesn't sound like a scam, I don't kno... Read More
Key Insights
- XRP and Ripple are different: Ripple Labs is the company that developed the network technology, while XRP is its proprietary token. Confusing the company’s technical progress with growth in token demand can lead investors to assume a connection that the creator argues is not guaranteed.
- XRP transactions are described as settling within three to five seconds, costing roughly two ten-thousandths of a penny, and supporting up to 1,500 transactions per second. These figures are presented as advantages over Bitcoin’s roughly 10-minute settlement, possible fees above $50, and three transactions per second.
- Ripple targets international banking infrastructure rather than the same markets as Bitcoin and Ethereum. Its closest comparison in the discussion is SWIFT, which communicates payment instructions between banks but does not itself move the money and is said to handle $6 trillion in transactions per day.
- Ripple’s xCurrent technology seeks to improve four areas: bidirectional bank messaging, worldwide technical standardization through the Interledger Protocol, rapid agreement on currency exchange rates, and transfer reliability. Together, these improvements are intended to make cross-border payments more transparent, inexpensive, stable, and nearly instantaneous.
- XRP was created to provide liquidity for banks by supporting pre-funded channels and settlement on Ripple’s proprietary blockchain. However, the token is not presented as a prerequisite for using Ripple’s payment technology, since banks could theoretically use another currency while benefiting from the same infrastructure.
- The Howey Test examines whether something involves an investment of money, a common enterprise, an expectation of profit, and profit arising from the efforts of others. A generally affirmative result indicates a security, which faces stricter regulation than a commodity or currency.
- An XRP security classification could affect the broader crypto market because many speculative tokens are issued by centralized sources and purchased with expectations of profit. The creator expects an unfavorable outcome to generate fear, selling, and uncertainty, although he believes prices could eventually recover.
- XRP is characterized as a bank-oriented and centralized alternative to permissionless cryptocurrencies. The creator sees buying it as a hedge against the decentralized thesis behind Bitcoin and Ethereum because Ripple’s corporate ownership conflicts with the decentralization, immutability, and equal participation he values in crypto.
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: What is the difference between Ripple and XRP?
Ripple refers to Ripple Labs, the company that developed the payment network and related technology. XRP is the company’s proprietary token. The distinction matters because banks can potentially adopt Ripple’s technology without using XRP. Technical partnerships or improvements involving Ripple therefore do not automatically mean that institutions must buy the token or that XRP demand will rise.
Q: How fast and inexpensive are XRP transactions?
XRP transactions are described as settling in three to five seconds and costing roughly two ten-thousandths of a penny, making their direct cost effectively negligible in the comparison presented. The network is also said to process up to 1,500 transactions per second. Bitcoin is contrasted with roughly 10-minute settlement, three transactions per second, and fees that can exceed $50.
Q: What banking problem is Ripple trying to solve?
Ripple aims to make international bank transfers faster, cheaper, more transparent, and more reliable. Its technology targets one-way messaging limitations, incompatible systems across countries, the need to agree quickly on exchange rates, and failed transfers that create delays and costs. It seeks to provide standardized communication and settlement capabilities without depending on the same middlemen used in existing arrangements.
Q: How does Ripple compare with the SWIFT payment system?
Ripple is compared with SWIFT because both address communication between financial institutions. SWIFT is described as the world’s largest payment processor, handling $6 trillion per day, although it sends coded instructions rather than moving money directly. Ripple seeks to improve that model with bidirectional communication, standardized connections, better exchange-rate coordination, and cheaper, nearly instantaneous transfers of value.
Q: Do banks need XRP to use Ripple technology?
Banks do not need XRP to use the Ripple technology described in the discussion. XRP was designed to supply liquidity, enable pre-funded channels, reduce foreign exchange concerns, and settle activity on Ripple’s proprietary blockchain. However, another currency could theoretically perform the monetary role. Consequently, adoption of Ripple’s banking infrastructure does not necessarily translate into institutional use or appreciation of XRP.
Q: How could the Howey Test apply to XRP?
The Howey Test asks whether there is an investment of money, participation in a common enterprise, an expectation of profit, and reliance on the efforts of others to produce that profit. If the answers are generally affirmative, the asset may be treated as a security rather than a commodity. That outcome would subject it to substantially stricter securities regulation.
Q: Why could XRP regulation affect other cryptocurrencies?
An XRP security classification could create a precedent or market expectation affecting other crypto projects issued by centralized sources and purchased for anticipated profit. Even though the discussion says the SEC does not consider Bitcoin a security, an unfavorable outcome for Ripple could still spread fear, uncertainty, and doubt across crypto markets, prompting investors to sell unrelated assets before conditions recover.
Q: Why does the creator consider XRP a centralized investment?
The creator considers XRP centralized because Ripple is a company, owns XRP, and can influence the system in ways that differ from permissionless networks. He views the token as designed for banks rather than as a rejection of the existing financial system. In his interpretation, XRP’s success could weaken the decentralization and immutability principles that attract people to Bitcoin and Ethereum.
Summary & Key Takeaways
-
Ripple Labs developed payment technology intended to improve international bank transfers through bidirectional messaging, standardized connections, rapid currency exchange, and more reliable settlement. The network promises greater transparency and cheaper, nearly instantaneous movement of value, positioning Ripple against SWIFT, a payment messaging system said to handle $6 trillion per day.
-
XRP is Ripple’s proprietary token, but it is not required to use Ripple’s underlying technology. The token was designed to provide liquidity, support pre-funded channels, and create a settlement standard that reduces foreign exchange concerns. Because banks could theoretically use another currency, adoption of Ripple technology does not necessarily create demand for XRP.
-
The regulatory dispute matters beyond XRP because the Howey Test could classify centrally issued crypto investments as securities when buyers invest money in a common enterprise, expect profit, and depend on others’ efforts. The creator believes an adverse result could frighten markets, while his deeper objection is XRP’s company-linked centralization and alignment with banks.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from Andrei Jikh 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator