How Ron Conway Evaluates Internet Startups
TL;DR
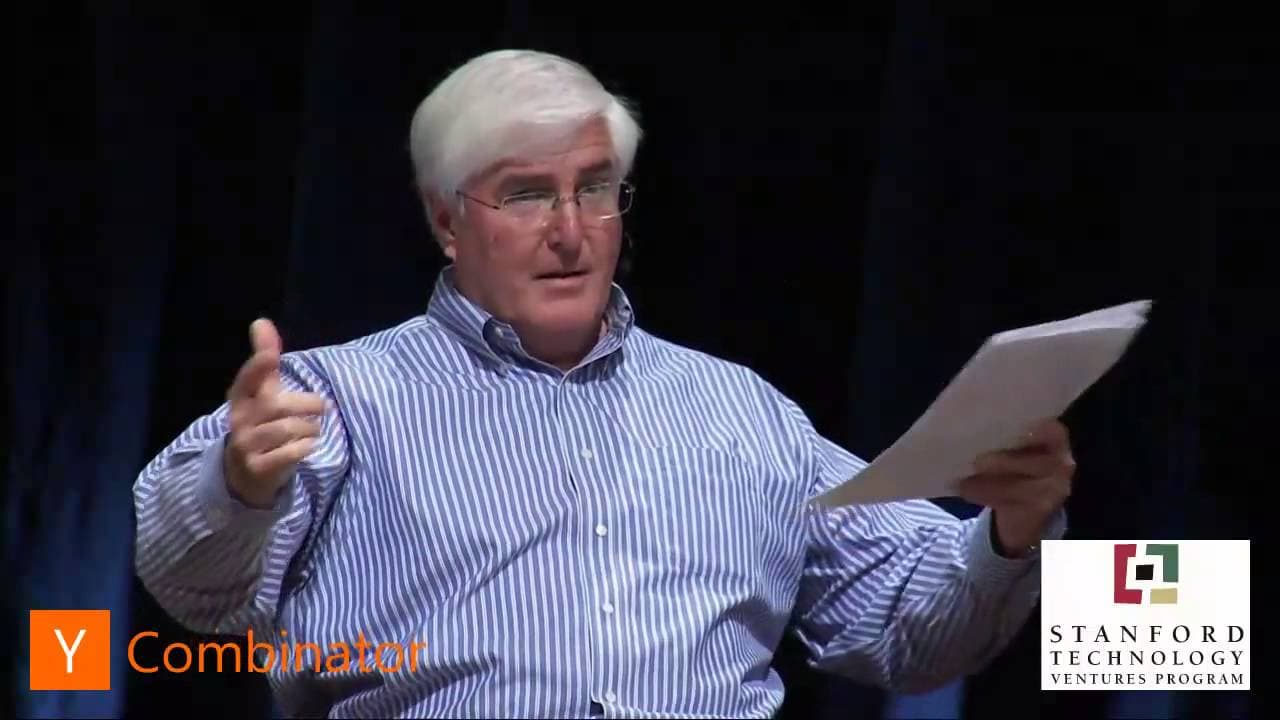
Invest in determined entrepreneurs pursuing forward-thinking ideas in rapidly growing, disruptive sectors, even when familiar patterns do not apply. Ron Conway credits his focus on internet software for decades of opportunities, while his biggest misses show that investors can underestimate unfamiliar markets, reject high valuations too quickly, or let a difficult prior experience distort a new decision.
Transcript
The funny thing is, we're, we're sitting in the back saying, "Which, which stories can we tell and which ones are too secret?" Because for every ... Ron Conway's like an iceberg. For every story where, where you, where you hear how he saved the day, there's a bunch where you can never tell how he saved the day. Um, have you guys ever seen Pulp Fict... Read More
Key Insights
- Conway's investment philosophy is to evaluate the entrepreneur first. He says SV Angel invests in the human being, particularly when a founder presents a forward-thinking idea that does not fit familiar patterns but still appears worth pursuing.
- Determination, conviction, and leadership are enduring requirements for startup founders. Conway emphasizes that building a company remains difficult, and his experience co-founding Altos Computer and two other startups informs his respect for what entrepreneurs endure.
- Conway's central sector decision was to invest only in internet software beginning in 1994. He and Ben Rosen chose a field expected to grow rapidly and disrupt existing industries because they believed innovation and growth were closely connected.
- Startup priorities changed as the industry moved from hardware toward internet software. Conway recalls that hardware businesses emphasized shipping products and handling defective returns, while modern companies need to pay much closer attention to product quality and consumer satisfaction.
- Internet commerce represented a major continuing opportunity in Conway's 2012 assessment. He believed the Internet remained in its infancy and argued that adding e-commerce, supported by platforms that help companies find customers, could create another large field of growth.
- Investment mistakes often arise from underestimating market size or novelty. Conway passed on Palantir because he did not understand the market's scale and declined Kickstarter because he did not yet grasp crowdsourcing, which he later described as vital for many startups.
- Prior negative experiences can distort later investment decisions. Conway declined Pandora partly because Napster had ended in bankruptcy and left him cautious about music, showing how a difficult outcome in one company can influence judgment about a different opportunity.
- Pattern recognition can work against venture investors when an idea is genuinely new. Conway cites Pinterest and Twitter as concepts that many investors struggled to understand, despite venture capital's stated willingness to accept risk and support innovation.
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: How does Ron Conway evaluate startup investments?
Ron Conway says SV Angel invests in the entrepreneur first and evaluates the human being behind the company. He looks for determination, conviction, leadership, and willingness to pursue a forward-thinking idea. This approach matters because genuinely new products may not resemble previous successes, making conventional pattern recognition less useful and potentially causing investors to reject important innovations.
Q: Why did Ron Conway focus on internet software?
Conway and Ben Rosen reasoned that innovation depends on growth and often disrupts existing industries. They therefore sought a sector that was already expanding rapidly or was likely to do so. In 1994, they committed entirely to internet software, then commonly discussed alongside TCP/IP and email, because they expected the Internet to become deeply disruptive.
Q: What startup qualities does Ron Conway consider timeless?
Conway identifies determination, conviction, leadership, and a focus on growth as qualities that have not changed. He stresses that startups are difficult to build and says his experience co-founding Altos Computer and two other startups gave him lasting respect for entrepreneurs. These traits remain important even as products, markets, and workplace practices evolve.
Q: How did startup building change from hardware to software?
Conway recalls that hardware companies could concentrate heavily on shipping units, even when products might later need repair or replacement. Altos maintained a large return material authorization department for defective products. He contrasts that environment with internet software, where he believes companies must place much greater emphasis on the product itself and on consumer satisfaction.
Q: Why do investors miss genuinely innovative startups?
Conway argues that investors often rely on pattern recognition even though venture capital is supposed to involve risk. A completely new idea may not match an established category, so investors struggle to assess it. He cites Pinterest's virtual pin board and Twitter's original concept as examples of unfamiliar ideas that encountered difficulty attracting investment.
Q: What were Ron Conway's biggest missed investments?
Conway names Salesforce.com, Pandora, Palantir, and Kickstarter among his significant misses. He thought Salesforce.com's $30 million valuation was too high, became cautious about music after Napster's bankruptcy, underestimated Palantir's potential market, and failed to understand crowdsourcing when Kickstarter was available. Each decision illustrates a different source of investment error.
Q: Why did Ron Conway pass on Pandora?
Conway passed on Pandora after his experience with Napster, which ultimately declared bankruptcy amid conflict involving the venture capital and music worlds. That experience made him hesitant about investing in music. He later characterized the decision as a mistake because his caution about the broader sector outweighed his stated preference for investing in the entrepreneur first.
Q: Why did Ron Conway become an angel investor?
After co-founding several companies and experimenting with angel investments, Conway discovered that he enjoyed mentoring entrepreneurs more than serving as an entrepreneur himself. In 1994, after selling his second company, he told his wife that angel investing would be his new lifelong job. He then pursued the strategy with Ben Rosen and focused on internet software.
Summary & Key Takeaways
-
Ron Conway moved from founding companies to angel investing because he preferred mentoring entrepreneurs. Drawing on experience at Altos Computer and two other startups, he developed respect for the difficulty of building companies. In 1994, he committed to internet software after identifying the Internet as a rapidly growing and disruptive sector.
-
Conway argues that determination, conviction, leadership, and attention to growth remain fundamental startup qualities. What changed from the hardware era is the importance of product and consumer satisfaction. Hardware companies could ship imperfect products and repair returns, while internet software created a different environment for serving customers and expanding businesses.
-
Conway's missed investments reveal how investors misjudge unfamiliar ideas. He passed on Salesforce.com over its valuation, Pandora after Napster's bankruptcy, Palantir because he underestimated its market, and Kickstarter because he did not understand crowdsourcing. He concludes that conventional pattern recognition can prevent investors from recognizing genuinely new products such as Pinterest and Twitter.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from Y Combinator 📚

Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator