$3.4k/Mo and Getting Married!! | Millennial Real Life Budget Review Ep. 3
TL;DR
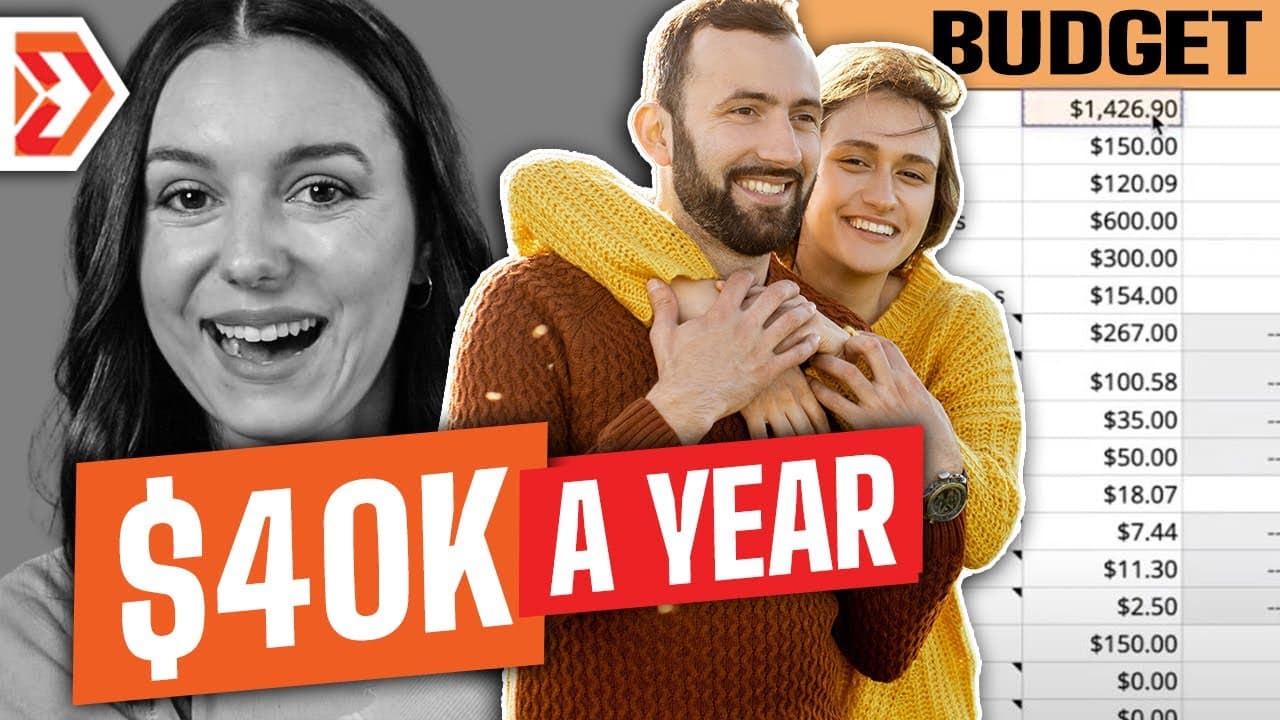
Millennial Real Life Budget Review Ep. 3 examines how an Ottawa couple can organize roughly $3,700 in monthly income while preparing for a $40,000 wedding and building financial security. Justine reviews their mortgage, groceries, utilities, subscriptions, irregular scholarship payments, and approximately $90,000 in savings and investments, then recommends structured emergency funds, automated goal-based savings, and careful transaction tracking. Read on for the specific budgeting priorities and account strategies.
Transcript
welcome to episode three of millennial real life budget review where we are actually going into somebody's real budget their real income and expenses and then helping them figure out exactly how to address their financial struggles and their goals stick around in this video hey guys it's Justine with debt free Millennials the channel to help you cr... Read More
Key Insights
- 💨 Establishing a structured emergency fund, beginning with $1,000, paves the way for financial security and stability.
- 🥅 Automating savings into separate accounts for specific financial goals enhances focus and discipline in achieving targets.
- 🍉 Prioritizing immediate expenses like weddings alongside long-term goals like building emergency funds balances short and long-term financial stability.
- 🦻 Detailed transaction tracking and reconciling physical vs. digital budgets aids in understanding spending habits and making informed financial decisions.
- 😨 Efficient budget allocation and strategic savings contribute to achieving financial milestones like buying a car, planning a vacation, and managing variable expenses effectively.
- 🤑 Setting clear financial goals and consistently monitoring budget performance leads to financial empowerment and successful money management.
- ❓ Developing a comprehensive budget strategy tailored to individual circumstances supports overcoming financial struggles and realizing financial aspirations effectively.
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: How should this Ottawa couple organize their roughly $3,700 monthly budget?
Their budget should first account for fixed costs such as the $1,400 mortgage, $600 for groceries, $300 for utilities, $150 for cell phones, and $120 for internet. The review then recommends directing available money toward wedding costs, an emergency fund, and separate savings goals while tracking each transaction against statements and receipts.
Q: What income does the couple have while they are in school?
The administrative and financial officer brings in $3,390.52, while the fiancé’s sister temporarily contributes $150 per month toward rent and groceries. The fiancé also receives about $1,800 in scholarship money for the school year at irregular times; spread across the year, that adds another $150 per month and brings estimated income to roughly $3,700.
Q: How much does the couple have in savings?
They reported approximately $90,000 in savings, including investments and their TFSA. The review considers these funds alongside their upcoming wedding expenses and goal of creating a large emergency fund.
Q: What emergency-fund strategy was recommended?
The review recommends starting with a structured $1,000 emergency fund. The next target is two to three months of living expenses, followed by building a fully funded emergency reserve.
Q: How should the couple prepare for their wedding expenses?
They are getting married in July 2023, roughly eight months after the recording, and expect expenses to arise periodically. With a wedding budget of around $40,000, the review recommends setting aside cash and prioritizing this near-term expense alongside longer-term emergency savings.
Q: How can the couple pay themselves first and save for a car or vacation?
The suggested approach is to automate contributions from each paycheck into separate accounts for specific goals. Treating car, vacation, and other savings contributions like required bills can make progress more consistent and focused.
Q: How can they reconcile a digital budget with physical statements and receipts?
The review recommends entering transactions carefully into the digital budget sheet and reconciling those entries with statements and physical receipts. This makes spending patterns clearer and helps the couple understand whether their real purchases match the amounts assigned in the budget.
Q: How should irregular or rollover expenses appear in the budget?
Irregular money, such as the fiancé’s scholarship, can be spread across months for planning even though it arrives sporadically. Running totals can also carry unused budgeted amounts into the next month for items such as taxes, while future purchases should be placed under the future-savings section rather than treated as fixed expenses.
Summary & Key Takeaways
-
A couple in Ottawa, Canada's budget review reveals $90,000 in savings, highlighted financial struggles, and goals like building an emergency fund and managing wedding expenses.
-
The couple's income from a non-profit job and a master’s student, along with expenses breakdown, drives recommendations to allocate funds to various financial goals.
-
Strategies to automate savings, set up emergency funds, and track physical vs. digital budgets are discussed to help the couple achieve financial stability.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from Debt Free Millennials 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator