Why JD.com (JD) Stock Will Reach $165 Per Share or $260 Billion Market Cap
TL;DR
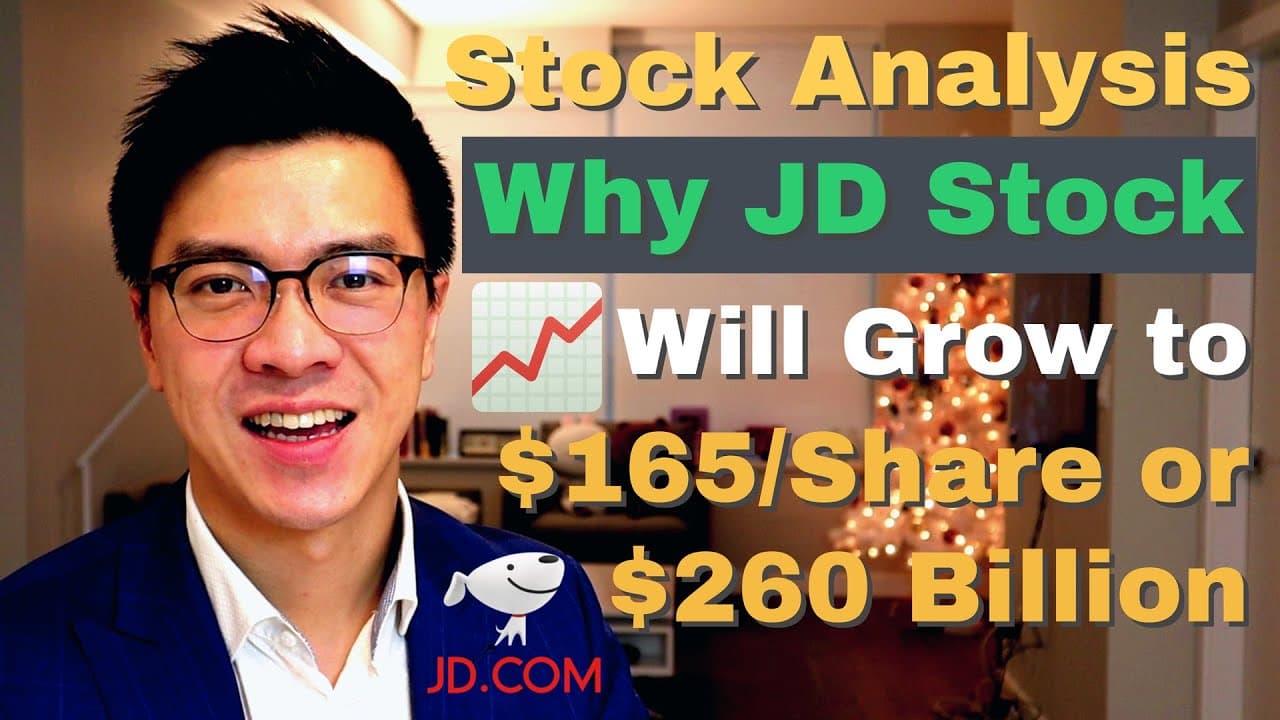
JD.com could reach $165 per share or a $260 billion market cap within three years if its revenue and free cash flow more than double, according to the presenter’s estimate. That case assumes roughly 28% annual growth and rests on JD’s nationwide logistics network, authentic products, and opportunities in China’s e-commerce market. Read on for the valuation calculation, competitive position, growth catalysts, and major risks behind this forecast.
Transcript
Hello everyone, this is Victor here. Welcome to the Intelligent Investor Channel, where you will learn about “stock investing and personal finance” that will help you become a great investor. In today’s video, I am going to talk about JD.com stock. I’m going to talk about “Why I believe JD stock will grow to $165 per share or $260 billio... Read More
Key Insights
- 👨💼 JD.com is similar to Amazon in terms of its business model and focus on B2C online retail.
- 🥶 The company's growing net revenues and positive free cash flow indicate a healthy core e-commerce business.
- 😌 JD.com's competitive advantages lie in its nationwide logistics network and its commitment to offering high-quality, genuine products.
- 🍉 China's large population and increasing e-commerce market present significant opportunities for JD.com's long-term growth.
- 💱 Regulatory risks, such as potential delisting from US stock exchanges, and competition from companies like Alibaba and Pinduoduo are important considerations.
- 🙂 JD.com's intrinsic value suggests that the stock is currently fairly valued or slightly undervalued.
- 🥶 Doubling revenue and free cash flow within the next 3 years is crucial for JD.com's stock to reach $165 per share or $260 billion market cap.
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: Why could JD.com stock reach $165 per share or a $260 billion market cap within three years?
The presenter estimates that JD.com could reach those levels if it maintains the same or a similar compound annual growth rate of about 28% for three years. Under that scenario, its revenue and free cash flow would more than double, supporting a doubling of the stock price or market capitalization through business fundamentals rather than market hype.
Q: What was JD.com’s estimated intrinsic value?
The presenter multiplies JD.com’s latest 12 months of free cash flow, $30.2 billion RMB, or $4.61 billion USD, by a multiple of 28.73. This produces an estimated fair value of approximately $132 billion, compared with a market capitalization of $128 billion at the time, suggesting the stock was fairly valued or slightly undervalued.
Q: How quickly were JD.com’s revenue and free cash flow growing?
JD.com’s net revenue grew at a compound annual rate of 34% between 2015 and 2019. Its free cash flow grew at a compound annual rate of 28.73% over the same period, although it was negative in 2018 because of capital expenditure totaling $21.4 billion RMB.
Q: What is JD.com’s primary business model?
JD.com primarily operates a business-to-consumer online retail store, buying inventory directly from suppliers and selling through its website and app. It verifies that products are genuine and owns its warehouses, fulfillment centers, and delivery networks.
Q: How important is online retail to JD.com’s business?
At the time described, JD.com earned 88.5% of its total net revenue from its online retail store. That business also generated all of the company’s operating income, offsetting other businesses such as JD Health and JD Logistics that were not yet profitable.
Q: How did JD.com’s Chinese e-commerce market share compare with Alibaba and Pinduoduo?
According to the cited eMarketer figures for 2019, Alibaba held 55.9% of China’s retail e-commerce market, JD.com held 16.7%, and Pinduoduo held 7.3%. Alibaba, JD.com, and Pinduoduo were projected to command a combined 83.6% in 2020, compared with 80.3% the previous year.
Q: What competitive advantages support JD.com’s long-term growth?
JD.com’s advantages include its nationwide logistics network, delivery within 24 hours, and emphasis on higher-quality, authentic products. Its direct control of warehouses, fulfillment centers, and delivery networks supports faster service and product reliability.
Q: What growth catalysts and risks affect the JD.com investment case?
Potential catalysts include China’s large population and e-commerce market, increased smartphone purchasing, and demand for authentic products and faster delivery. Major risks include competition from Alibaba and Pinduoduo and the possibility of delisting from U.S. stock exchanges.
Summary & Key Takeaways
-
JD.com is the second largest e-commerce company in China, known as the Amazon of China, primarily operating as a B2C online retail store.
-
JD's net revenues have been growing consistently at a compound annual growth rate of 34% between 2015 and 2019, with a positive free cash flow growth.
-
With its nationwide logistics network, higher quality products, and growing e-commerce market in China, JD has competitive advantages and catalysts for long-term growth.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from The Intelligent Investor 📚

Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator