How Banks Create Money From Customer Deposits
TL;DR
Banks keep only a portion of deposited money available while lending or investing the rest, allowing the same funds to support repeated transactions across the economy. This system expands credit and economic activity, but it depends on confidence because banks cannot return every deposit simultaneously. Government insurance helps discourage panic by protecting eligible deposits up to $250,000.
Transcript
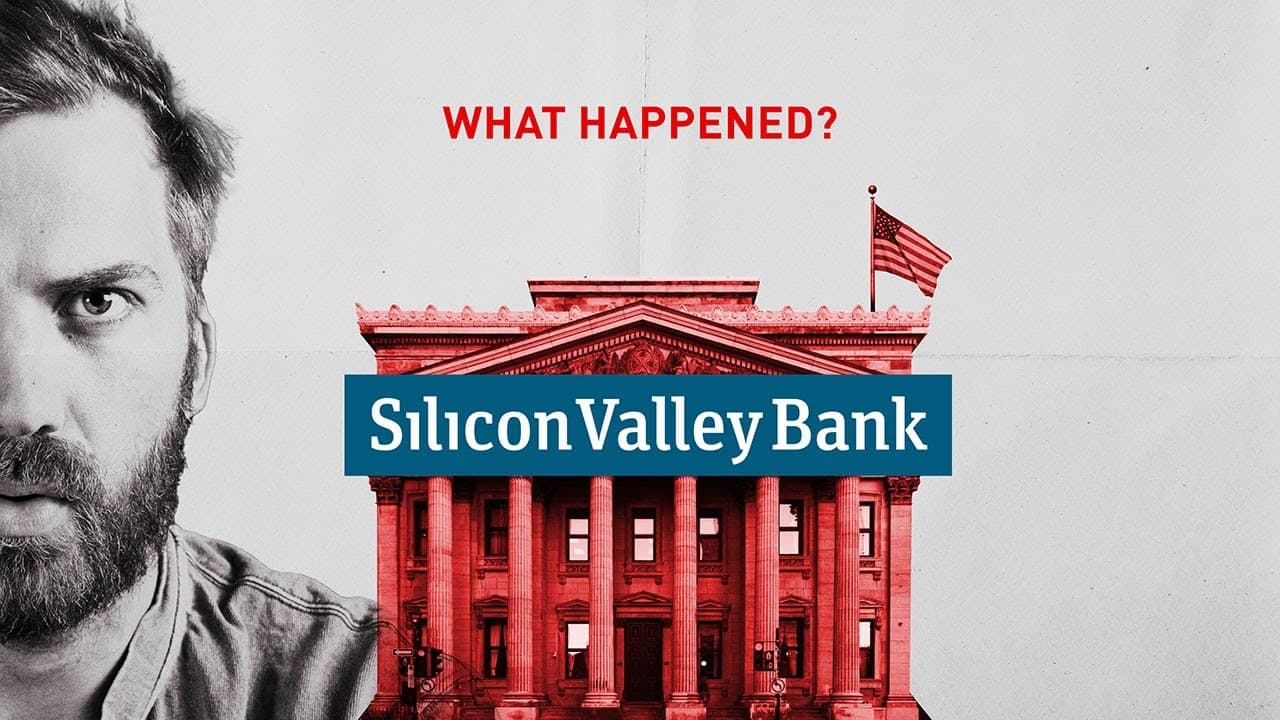
a rough week for the banking industry the collapse of Silicon Valley Bank is causing shock waves across the entire business world a big Bank just died we've all heard about it everyone's talking about it and we gotta talk about it because something big is going on here as of this morning Silicon Valley Bank or svb has gone under com... Read More
Key Insights
- Banks are financial intermediaries that keep only part of customer deposits available and put the remainder to work through lending or investing. Depositors still see their full account balances, even though much of the underlying money may be supporting loans elsewhere in the economy.
- The money multiplier effect is the repeated expansion of deposits and credit as borrowed funds are spent, received, redeposited, and lent again. A single original deposit can therefore support a much larger volume of transactions than its initial face value might suggest.
- The reserve ratio is the portion of deposits that a bank keeps rather than lending or investing. In the transcript's simplified example, a 10% ratio lets a bank use the remaining 90% to issue loans, purchase investments, and earn returns.
- A lower reserve ratio is associated with greater money creation because banks can lend a larger share of each deposit. It also increases vulnerability to withdrawals, while a higher reserve ratio limits credit expansion but leaves more money immediately available to depositors.
- A bank run is dangerous because banks do not keep enough cash to repay every depositor simultaneously. The banking model functions when customers trust that their balances remain accessible and avoid demanding all their money at the same time.
- Government deposit insurance is intended to preserve public confidence by promising that eligible customers will recover lost deposits when a bank fails. The transcript states that this protection reaches up to $250,000, which covers most ordinary depositors but may leave large business balances exposed.
- Silicon Valley Bank is presented as an example of how confidence can collapse around a financial institution. Its failure created concern because it served technology startups and venture capital clients, including businesses that needed large bank balances for recurring obligations such as payroll and rent.
- Bank lending is portrayed as economically productive because deposited money can finance equipment, homes, businesses, and other transactions. Keeping all money outside banks might reduce exposure to bank failures, but it would also remove funds from the credit process described in the transcript.
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: How do banks use money deposited by customers?
Banks keep a portion of customer deposits available and use much of the remainder for loans or investments. In the transcript's example, deposited money is lent to a business, which spends it on equipment. The seller then deposits the payment into another bank, allowing that bank to retain part and lend the rest again.
Q: What is the money multiplier effect in banking?
The money multiplier effect is the expansion of money and credit through repeated lending and redepositing. A customer deposits money, the bank lends most of it, and the borrower spends it. When the recipient deposits that payment into another bank, the process can repeat, so one initial deposit supports many additional loans and transactions.
Q: How does the reserve ratio affect money creation?
The reserve ratio determines how much deposited money a bank keeps available and how much it can lend or invest. A lower ratio allows more money to enter repeated cycles of lending and redepositing, producing greater credit expansion. A higher ratio restricts that expansion but gives the bank more resources for meeting customer withdrawals.
Q: Why can banks fail if many customers withdraw together?
Banks can struggle during simultaneous withdrawals because they do not hold every customer's full balance as readily available cash. Much of the deposited money has already been lent or invested. If many depositors demand repayment together, the bank may be unable to obtain enough liquid funds quickly, even though customers' accounts display their complete balances.
Q: Why does the banking system depend on public confidence?
Public confidence discourages depositors from trying to withdraw all their money at once. Banks can operate normally when withdrawals occur gradually because they retain some funds and receive repayments from loans and returns from investments. If confidence disappears, collective withdrawal demands can expose the gap between recorded deposit balances and immediately available bank funds.
Q: How does government deposit insurance reduce bank panic?
Government deposit insurance reassures customers that eligible deposits will be repaid if a bank fails. The transcript says the protection covers deposits up to $250,000. That promise makes ordinary customers less likely to rush to withdraw their money, helping prevent fear from turning an individual bank's problems into broader instability across the banking system.
Q: Why are businesses especially exposed to bank failures?
Businesses may keep large balances in banks because they need money for continuing expenses such as payroll and rent. Those balances can exceed the government insurance limit described in the transcript. When a bank fails, uncertainty about access to uninsured funds can therefore threaten a company's ability to pay workers, landlords, suppliers, and other obligations.
Q: Why not keep all personal money outside the banking system?
Keeping money outside banks could prevent a bank from lending or investing those particular funds, but the transcript argues that widespread withdrawals would weaken the broader economy. Bank deposits support loans for businesses, equipment, homes, and other purchases. Removing deposits on a large scale would reduce the credit expansion and economic transactions enabled by repeated lending.
Summary & Key Takeaways
-
Banks do not simply store every customer's money in a vault. They retain a portion and use the remainder for loans and investments. Borrowers spend those funds, recipients deposit the payments into other banks, and those banks repeat the process, allowing an original deposit to support much more economic activity.
-
The money multiplier effect describes how repeated lending and redepositing expand the amount of money circulating through the economy. The reserve ratio influences both the scale and risk of that expansion. A lower reserve ratio permits more lending, while a higher ratio leaves banks better prepared to satisfy customer withdrawals.
-
Fractional banking depends heavily on confidence because deposited balances exceed the cash that banks keep immediately available. If many customers demand their money together, a bank may be unable to meet every request. Government deposit insurance helps maintain stability by promising repayment of eligible deposits up to $250,000 when a bank fails.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from Johnny Harris 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator