Are Big Banks Safe Compared to Silicon Valley Bank?
TL;DR
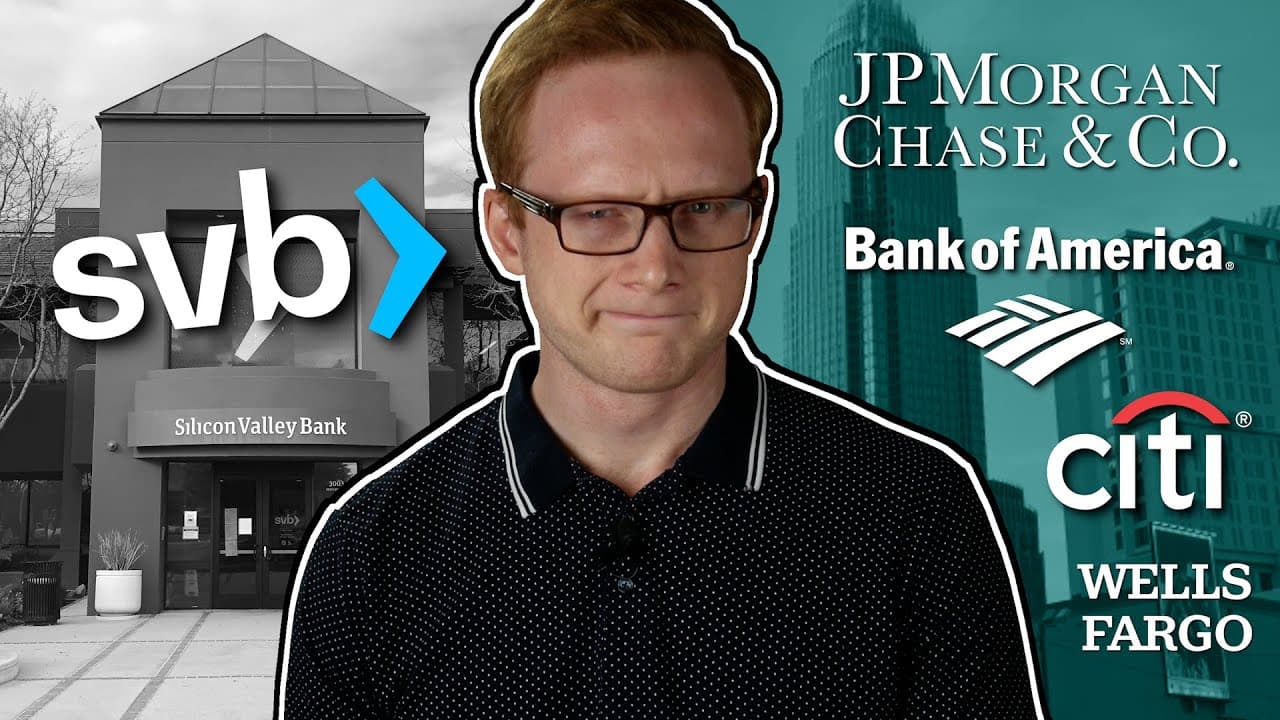
The largest US banks, including JP Morgan and Bank of America, are significantly more secure than Silicon Valley Bank due to their greater size, higher liquidity, and better risk management. While they do face unrealized losses on held maturity assets, their strong liquidity coverage ratios and diversified portfolios mitigate the risk of a bank run, making them less vulnerable than Silicon Valley Bank was.
Transcript
this video is sponsored by blinkist use the link in the description below to get 25 off the premium membership price plus seven days free ladies and gentlemen welcome to the plain bagel I'm your host Richard coffin we've gone three weeks without a major banking collapse so congratulations well done but even though the dust has settled quite a bit i... Read More
Key Insights
- 🏦 The major US banks are much larger and more diversified than Silicon Valley Bank, reducing the risk of a bank run.
- ✋ The banks have a considerable amount of high-quality liquid assets to meet depositors' needs.
- 🏦 The unrealized losses on held maturity assets in the major US banks are a concern, but their impact depends on various factors such as a bank run.
- 🖤 Poor risk management and lack of hedging played a significant role in Silicon Valley Bank's collapse.
- 😮 Banks benefit from rising interest rates, which can improve their profitability over the long term.
- ❓ Trust and transparency are crucial for the stability of the financial system.
- 🏃 The Federal Reserve has implemented lending programs to address liquidity pressures and decrease the risk of a bank run.
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: How do the sizes of the major US banks compare to Silicon Valley Bank?
The largest US banks have deposits ranging from $1.3 to $2.3 trillion, which is roughly ten times the size of Silicon Valley Bank.
Q: What is the level of high-quality liquid assets held by these banks?
Approximately a quarter to 42 percent of the banks' deposits are backed by high-quality liquid assets, which provides a significant level of liquidity to meet depositors' needs.
Q: What is the liquidity coverage ratio of these banks?
The liquidity coverage ratio sits at around 120 for most of these banks, except for JP Morgan, which has a ratio of 112 for the firm-wide and 151 specifically for its banking operation. This indicates that they can meet all expected net withdrawals within a 30-day stress period.
Q: How do the unrealized losses on held maturity assets compare between the major US banks and Silicon Valley Bank?
The major US banks do have unrealized losses on their held maturity assets, with Bank of America having the largest amount at over $100 billion. However, these losses are not as severe as those faced by Silicon Valley Bank.
Summary & Key Takeaways
-
The biggest US banks (JP Morgan, Bank of America, Citigroup, and Wells Fargo) are significantly larger than Silicon Valley Bank, with deposits ranging from $1.3 to $2.3 trillion.
-
These banks have a considerable amount of high-quality liquid assets, ranging from a quarter to 42 percent of their deposits.
-
Liquidity risk is evaluated using the liquidity coverage ratio, which measures the ability of a bank to meet withdrawals in stress conditions. The ratio sits at around 120 for these banks, except for JP Morgan, which has a ratio of 112 for the firm-wide and 151 specifically for its banking operation.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from The Plain Bagel 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator