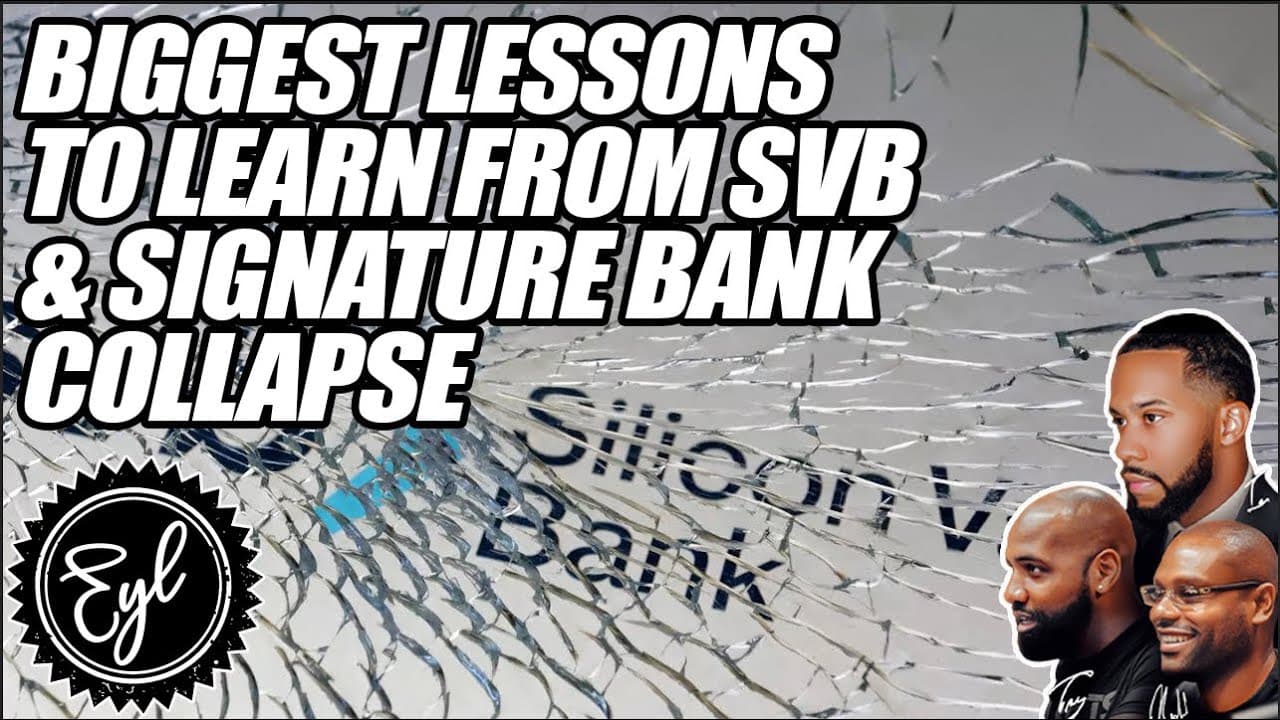
Biggest Lessons to Learn from SVB & Signature Bank Collapse
TL;DR
Silicon Valley Bank collapsed after investment losses and over-leveraging left it without enough money to meet withdrawals. The bank said it needed $2 billion to remain solvent, prompting frightened customers to rush for their funds and the FDIC to step in. Because SVB served startups and venture capital firms, the speakers expect wider pressure on smaller companies, regional banks, and bank stocks. Read on for their key lessons about risk, rates, and solvency.
Transcript
the first thing that we have to talk about is the biggest thing that has happened last week Silicon Valley Bank collapsed yeah um we'll give some some preference on this but uh this is the second Bank to collapse in a week yeah um one of the biggest uh Bank crises in American history yeah um since 2008 yep and this was the biggest bank to fail sinc... Read More
Key Insights
- 📼 Silicon Valley Bank's collapse highlights the risks of over-leveraging and investing in risky assets.
- ☠️ Low interest rates during loan disbursement can lead to potential losses when rates rise.
- 👨💼 Bank collapses can have a significant impact on the economy, causing a loss of jobs and affecting the financial stability of individuals and businesses.
- 🧡 Diversification is crucial to mitigate risks, and individuals should consider investing in a range of assets beyond traditional banks.
- 🥺 The collapse may lead to tighter regulations and risk controls for smaller banks, making it harder for them to provide loans to businesses.
- 🏦 Customers should be aware of the financial solvency of their banks and consider diversifying their investments.
- 🤨 The collapse of Silicon Valley Bank raises questions about the integrity and management of banks, emphasizing the importance of knowing the founders and leadership behind financial institutions.
Install to Summarize YouTube Videos and Get Transcripts
Explore YouTube Video Summarizer or Get YouTube Transcript Extractor
Questions & Answers
Q: What caused Silicon Valley Bank to collapse?
Silicon Valley Bank did not have enough money after over-leveraging itself and losing money on bonds and mortgage-backed securities as the Federal Reserve raised interest rates. When it announced that it needed $2 billion to remain solvent, customers rushed to withdraw their funds, but the bank could not meet the demand.
Q: How did rising interest rates contribute to Silicon Valley Bank's failure?
The speakers say SVB made loans to tech companies during a period of very low interest rates while trying to offset its risk with bonds and mortgage-backed securities. As rates rose, tech companies came under pressure and the bank's investments lost money, creating delayed consequences from the rate increases.
Q: What happened to Silicon Valley Bank customers after the collapse?
Customers became frightened and rushed to withdraw their money after SVB disclosed that it needed $2 billion. The speakers say FDIC-insured customers had received their money, while officials were working to address other customers within the following week.
Q: Why was Silicon Valley Bank important to startups and venture capital firms?
SVB was geared toward Silicon Valley startups and venture capital firms rather than ordinary customers opening small personal accounts. These companies and investors used the bank to borrow money and obtain capital, making its collapse especially disruptive to the startup ecosystem.
Q: How could the SVB collapse affect startup employees?
The speakers warn that startups banking with SVB could struggle to make payroll after the bank's dissolution. Because these companies employ people, a funding interruption could threaten jobs unless a bridge loan or another source of money becomes available.
Q: What was the immediate effect of the SVB collapse on bank stocks?
Bank stocks lost value after SVB failed, which the speakers describe as a ripple effect. They also predict that customers seeking safety could move toward larger institutions such as JP Morgan and Bank of America, allowing the biggest banks to become even larger.
Q: What risk-management lesson do the speakers draw from the SVB collapse?
Their central lesson is that risk-to-reward considerations matter. They describe lending to startups with between 1 and 100 employees and net margins of 3% to 15%, while offsetting that exposure with bonds and mortgage-backed securities, as an unsound business plan.
Q: How could the collapse change banking for small businesses?
The page's summary and insights say the failure may bring tighter regulations and risk controls for smaller and regional banks. That could make it harder for those banks to provide loans to small businesses, while more customers and market power shift toward the largest banks.
Summary & Key Takeaways
-
Silicon Valley Bank collapsed due to insufficient funds caused by investment losses in bonds and mortgage-backed securities, leading to a rush by customers to withdraw their money.
-
The bank, geared towards startup companies and venture capital firms, announced the need for $2 billion to remain solvent.
-
The collapse will have long-term effects on the stock market, with larger banks like JP Morgan and Bank of America expected to benefit.
Read in Other Languages (beta)
Share This Summary 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator
Explore More Summaries from Earn Your Leisure 📚
Summarize YouTube Videos and Get Video Transcripts with 1-Click
Try YouTube Summary with ChatGPT & Claude or YouTube Transcript Generator